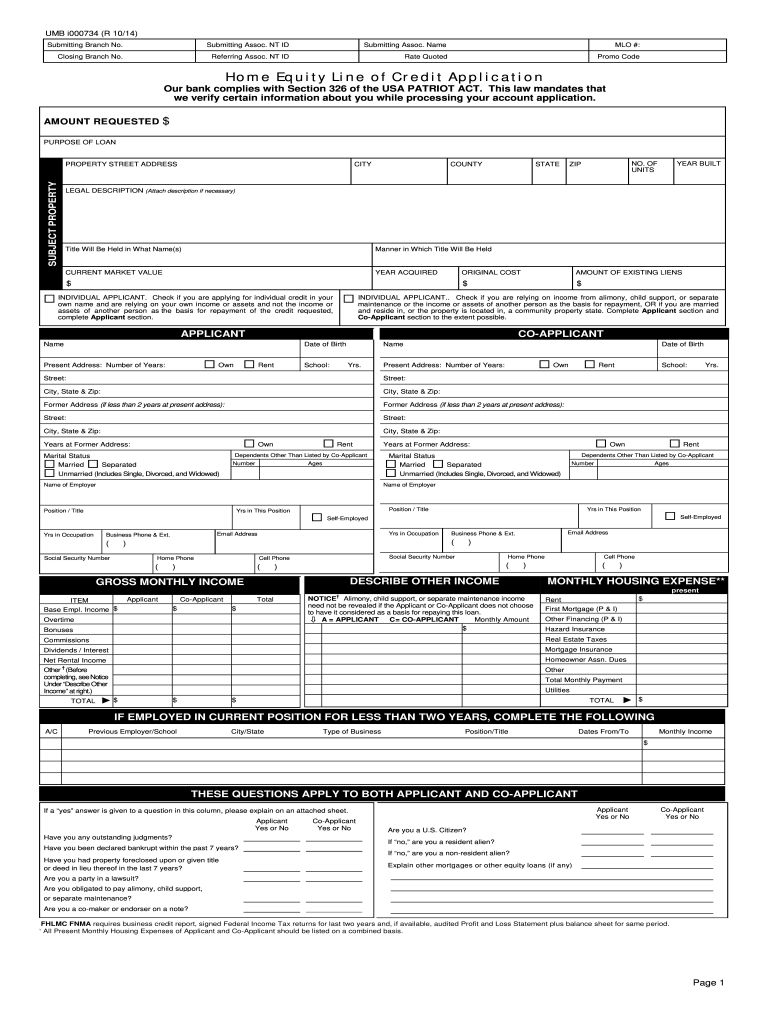
Home Equity Application Form
Use a Home Equity Application Form 2014 template to make your document workflow more streamlined.
What the home equity application form does
A Home Equity Application Form collects the borrower, property, income, existing-lien, requested-credit, and authorization information a lender needs to evaluate a home-equity loan or line of credit. The borrower supplies accurate financial and property details, reviews required disclosures, and signs the completed application. With signNow, a lender can upload the form, auto-detect fillable fields, assign borrower and co-borrower roles, send signature requests, and retain the completed PDF with its audit trail. Approval, appraisal, underwriting, recording, and final loan terms remain governed by the lender’s process and applicable state and federal law.
Business types using this application
The form is most useful where lenders must collect consistent borrower, property, and authorization information before reviewing home-equity credit.
A mortgage broker or community lender can send the application to a borrower and co-borrower, collect property and income details, and route acknowledgments in sequence before underwriting reviews the file. A regional bank or credit union can use a reusable template for home-equity applications, keeping required borrower fields, authorization language, and signature assignments consistent across branches and remote applicants. An enterprise mortgage operation can connect application workflows with its existing systems, use role-based administration, and preserve signed records for underwriting, servicing, quality control, and compliance review.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
Who uses this application form
Lenders and credit unions
Mortgage lenders, credit unions, and home-equity teams use the application to collect borrower identity, property, income, loan-purpose, and authorization details before underwriting. Required fields should match the institution’s approved credit policy and disclosures.
Borrowers and co-borrowers
Borrowers and co-borrowers complete the application remotely, review the requested credit terms, and sign applicable acknowledgments. A signNow workflow can route each signer separately while preserving the final document and audit trail.
Legal standing of the application
A signed Home Equity Application Form can support evidence of borrower intent, disclosures, and consent when the record is attributable, retained, and reproducible. ESIGN, 15 U.S.C. ch. 96, and applicable state UETA laws generally recognize electronic records and signatures, but they do not replace state rules for deeds, notarization, recording, or excluded documents such as wills and certain court filings.

How the application workflow works
The signNow workflow moves the home-equity application from an approved blank form to a signed, traceable lender record.
Upload the form: Upload the lender’s Home Equity Application Form to signNow and preserve the approved layout and disclosure text. Review detected fields: Use automatic field detection, then verify borrower, co-borrower, property, income, and signature assignments manually. Route to signers: Send the application to each signer in the lender’s required order using email or a controlled signing link. Store the completed record: Collect signatures, download the completed PDF, and retain its audit trail with the underwriting record.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Recommended application workflow setup
Configure the Home Equity Application Form around verified signer identity, traceable consent, protected borrower data, and the lender’s approved retention policy.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification with SMS authentication |
| Signature type | Typed or drawn electronic signature |
| Audit trail | Retain the completed signNow audit trail |
| Document retention | Follow lender policy and applicable federal rules |
| Encryption | TLS 1.2 or 1.3 and AES-256 |
Platform requirements for signNow
The Home Equity Application Form can be prepared and signed through supported versions of Chrome, Firefox, Safari, or Edge on Windows and macOS, with signNow mobile apps available for iOS and Android.
Supported browsers Chrome, Firefox, Safari, Edge Desktop systems Windows and macOS Mobile systems iOS and Android
Lenders should manage mobile access through approved devices and account controls when applications contain income, property, or credit information. Enterprise deployments may also configure API access, SSO provisioning, and authentication policies to align signNow with internal identity and records-management requirements.
Find and fill out the correct home equity application form
airSlate SignNow helps you fill in and sign documents in minutes, error-free. Choose the correct version of the editable PDF form from the list and get started filling it out.
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| *2014 UMB i000734 [2014-10] 2014 | 4.8 Satisfied (5066 Votes) |



Security for borrower records
Transport encryption:
Stored-data encryption:
Security reporting:
Information security:
Electronic signature law:
Privacy controls:
Home equity application processing stages
Processing time depends on borrower response, lender review, property documentation, and any required appraisal or state-specific closing steps.
Prepare the application
Deliver to signers
Track signer turnaround
Complete and archive
What the application audit trail records
The audit trail connects signer identity, actions, timestamps, document completion, and exported evidence for the Home Equity Application Form.
Authenticate signers:
Capture timestamps:
Check document integrity:
Seal the record:
Export evidence:
Archive securely:
Preserve home equity records carefully
Use an authority-based retention schedule, export the audit trail, and protect borrower information throughout the application lifecycle.
Apply an authority-based retention schedule
Export the audit trail with the application
Restrict access to borrower information
Check state recording and notarization rules
Home equity application troubleshooting
Resolve field, signer, consent, plan, and state-law issues before treating a completed application as ready for underwriting or closing.
On the Business plan, upload the approved Home Equity Application Form and check every detected field before sending. Automatic detection accelerates preparation, but the lender remains responsible for verifying borrower, property, income, and authorization fields.
Add the co-borrower as a separate recipient and assign that person’s required fields before sending. Review the recipient order and completion status in signNow so the application is not finalized with an incomplete authorization section.
Use signNow’s audit trail to review timestamps, signer actions, and completion history. Under ESIGN, 15 U.S.C. ch. 96, electronic records require attribution, intent, consent where applicable, and retention that permits later reproduction.
The Business Premium plan includes bulk send and kiosk mode, while Business includes templates and mobile apps. Choose the plan based on the lender’s workflow; do not assume bulk distribution is included in Business.
For a consumer-facing application, provide the ESIGN consumer disclosure required by 15 U.S.C. §7001(c), including paper-record access and consent-withdrawal procedures. Confirm the borrower can access the electronic record before signing.
Electronic signing does not replace state recording or notarization requirements for a deed or other security instrument. Check the relevant state law and county recorder process before treating the signed application as the complete closing package.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.