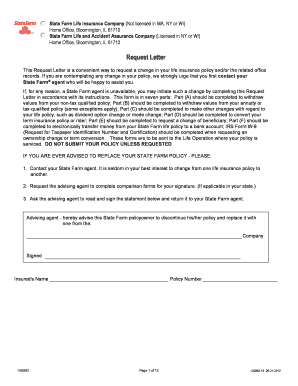
Life Insurance Cancellation Form Letter
Use a Life Insurance Cancellation Form Letter 2012 template to make your document workflow more streamlined.
Life Insurance Cancellation Form Letter overview
A Life Insurance Cancellation Form Letter is a written request telling an insurer to terminate a specified life insurance policy. It identifies the policyholder, insured person, policy number, requested effective date, and authorization for cancellation. The sender completes the letter, reviews its accuracy, and delivers it through the insurer’s required channel. A copy and delivery evidence should be retained. Under 15 U.S.C. ch. 96, electronic records can receive legal recognition, but ESIGN expressly excludes notices of life insurance cancellation, so the insurer’s instructions and applicable state law control signing and delivery.
Who uses this cancellation letter
Individual policyholders
Policyholders use the letter to request cancellation, identify the policy, state the effective date, and document delivery to the insurer.
Insurance operations
Insurance teams use the letter to organize cancellation requests, verify policy details, and retain evidence for customer-service and compliance reviews.
Complete the life insurance cancellation letter
Prepare the policy details, state the cancellation request clearly, and preserve evidence of delivery to the insurer.
Enter policy details:
Enter the policy number, insured person, owner, and requested cancellation date. State the request:
State the cancellation request and confirm the intended effective date. Attach supporting documents:
Attach required insurer documentation before sending the letter. Review and deliver:
Review the completed letter and follow the insurer’s delivery instructions. Archive the record:
Save the signed or printed copy with its delivery evidence.
Audit trail for cancellation documents
The audit trail records who handled the Life Insurance Cancellation Form Letter, what happened, and when each event occurred.
Authenticate signer:
Capture timestamp:
Hash document:
Seal document:
Log actions:
Export evidence:
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Recommended cancellation letter setup
Use insurer-approved signing, controlled access, and an exportable audit trail when preparing this cancellation request.
| Setting | Recommendation |
|---|---|
| Authentication method | Email access with SMS OTP |
| Signature type | Insurer-approved handwritten or electronic signature |
| Audit trail | Enable completion history and export |
| Document retention | Retain according to applicable record rule |
| Encryption and provisioning | TLS 1.2/1.3, AES-256, admin-managed users |
Find and fill out the correct life insurance cancellation form letter
airSlate SignNow helps you fill in and sign documents in minutes, error-free. Choose the correct version of the editable PDF form from the list and get started filling it out.
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| *2012 State Farm 1002822 [2012-06-21] 2012 | 4.8 Satisfied (8796 Votes) |
Signer authentication and certificates
PKI certificates:
X.509 certificates:
Two-factor authentication:
SMS OTP:
ID verification:
Signer attribution:
Privacy and disclosure pitfalls
Including the full policy number incorrectly can delay matching the cancellation request to the insurer’s account. Sending the letter without confirming the requested effective date can create disputes about coverage termination. Emailing personal and policy information without access controls can expose sensitive insurance data. Failing to preserve delivery evidence can make the cancellation request difficult to prove later.
Retention periods for signed cancellation records
Keep the completed letter and supporting records according to the rule that applies to the organization and information involved.
Six years for HIPAA records
Three years for tax records
Six years for broker records
Three years for payroll records
Five years for injury records
Best practices for cancellation records
Accurate policy details, insurer confirmation, and retention controls help establish what cancellation was requested, when, and through which channel.
Verify every policy detail
State the effective date clearly
Preserve delivery evidence
Apply the correct retention rule
Troubleshooting cancellation letter workflows
Resolve field, authentication, delivery, and legal-scope issues before treating the Life Insurance Cancellation Form Letter as effective.
Upload the letter as a PDF or supported document, then review signNow’s field detection. Confirm every policy number, date, and signer assignment manually before sending. Auto-detection assists placement but does not verify the insurer’s requirements or the legal accuracy of the cancellation request.
The Business plan includes templates and audit trails, while Business Premium adds bulk send. A single Life Insurance Cancellation Form Letter generally needs ordinary sending rather than bulk distribution. Select the plan based on user count, workflow controls, and signature-invite needs.
Use signer authentication appropriate to the policyholder and insurer’s instructions, such as email access or SMS OTP. For sensitive records, stronger identity proofing may be appropriate. Authentication evidence supports attribution but does not remove ESIGN’s exclusion for life insurance cancellation notices.
signNow provides audit trails that record timestamps, actions, and signer activity. Export the completed letter and audit trail together, then retain them under the applicable policy. The audit trail strengthens evidence of handling but cannot replace a required paper or insurer-specific submission channel.
Consumer-facing electronic records require an ESIGN disclosure explaining paper-record rights, electronic access, and withdrawal procedures under 15 U.S.C. §7001(c). More importantly, life insurance cancellation notices are excluded from ESIGN, so confirm whether the insurer requires wet-ink delivery.
If a recipient cannot open the signing link, verify the email address, resend the invitation, or provide the insurer’s required alternative delivery method. Do not assume a completed link proves cancellation; preserve confirmation from the insurer and the final document copy.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.