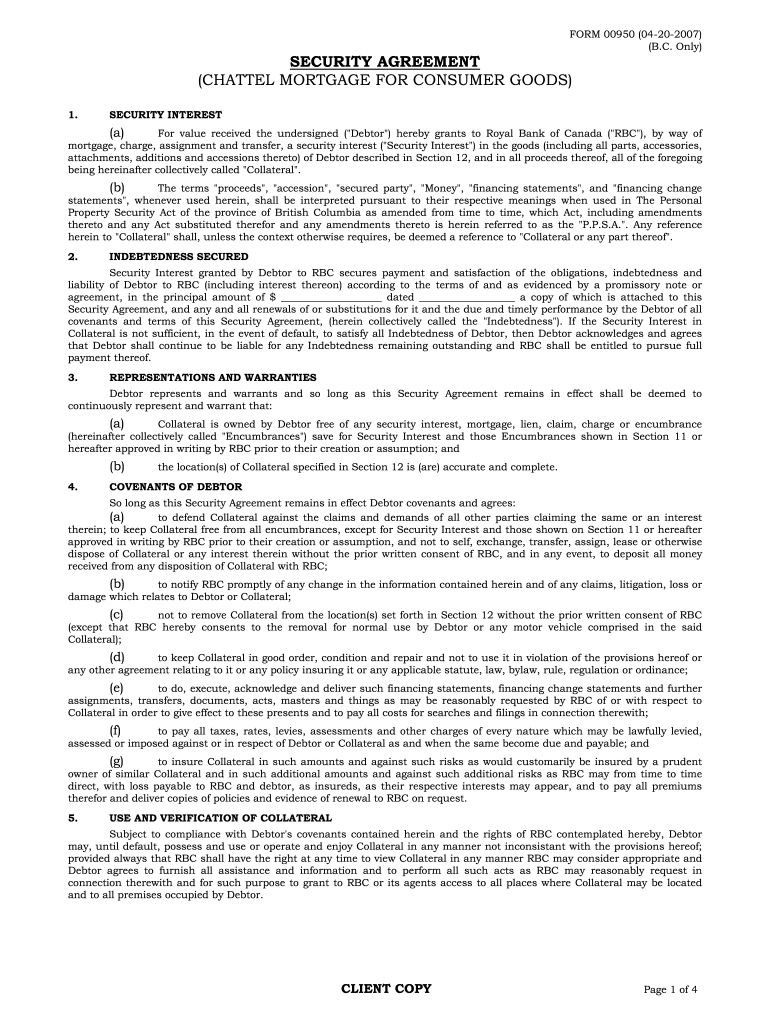
Chattel Mortgage
Use a Chattel Mortgage 2007 template to make your document workflow more streamlined.
What a Chattel Mortgage does
A Chattel Mortgage secures a debt with identified personal property rather than real estate. The document normally connects a borrower, lender, collateral description, repayment obligation, and enforcement rights, while state law determines execution, filing, perfection, and any notarization requirements. To prepare one in signNow, upload the lender’s Chattel Mortgage, review or place fields for the parties and collateral, route it to each signer, and preserve the completed copy with its audit trail. ESIGN and UETA can support electronic signatures, but they do not eliminate state filing or recording requirements.
Businesses that use Chattel Mortgage
Chattel Mortgages are most useful when financing is secured by identifiable business equipment, vehicles, or other movable property.
A farm equipment operator can use a Chattel Mortgage to document financing secured by tractors, combines, or other identified equipment while coordinating lender and borrower signatures remotely. A construction company can use the document for financed machinery or vehicles, preserving the collateral schedule and signed repayment terms before equipment enters active projects. A regional equipment lender can standardize Chattel Mortgage templates, route borrower and guarantor signatures, and retain each completed instrument with its audit trail for portfolio administration.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
How a Chattel Mortgage workflow works
A Chattel Mortgage becomes usable when its parties, collateral, obligations, signatures, and required filing steps align.
Define collateral: Identify the borrower, lender, debt, and movable collateral. Complete terms: Complete the collateral schedule and repayment terms. Send document: Route the Chattel Mortgage to required signers. Store evidence: Preserve the signed agreement and audit trail.
Complete a Chattel Mortgage in signNow
Use the actual collateral schedule and financing terms, then route the document through signNow for signatures and recorded completion evidence.
Upload document:
Upload the lender’s Chattel Mortgage PDF. Add fields:
Auto-detect or place fields for parties, collateral, dates, and signatures. Assign signers:
Assign borrower, lender, guarantor, or witness roles. Send for signing:
Send the document and monitor completion. Store records:
Download the executed document and audit trail.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Recommended Chattel Mortgage workflow setup
Configure signing, evidence, access, and retention around the collateral and filing requirements for the specific transaction.
| Setting | Recommendation |
|---|---|
| Authentication method | Email links with SMS OTP |
| Signature type | Legally binding electronic signatures |
| Audit trail | Capture and export signer history |
| Document retention | Apply the governing state schedule |
| Encryption | TLS 1.2/1.3 and AES-256 |
Find and fill out the correct chattel mortgage
airSlate SignNow helps you fill in and sign documents in minutes, error-free. Choose the correct version of the editable PDF form from the list and get started filling it out.
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| *2007 Canada RBC Royal Bank Form 00950 [2007-04-20] 2007 | 4.8 Satisfied (2821 Votes) |
Authenticate Chattel Mortgage signers
Email authentication:
SMS verification:
Two-factor authentication:
Identity verification:
PKI certificates:
X.509 certificates:
Privacy pitfalls in Chattel Mortgage workflows
Including full bank details, driver’s license data, or unnecessary personal identifiers exposes information beyond what the collateral transaction requires. Failing to capture electronic consent and intent can weaken evidence that the borrower knowingly signed the Chattel Mortgage. Allowing every workspace member to edit collateral descriptions can create unauthorized changes before execution. Sharing an unrestricted signing link can expose borrower and lender information to an unintended recipient.
Chattel Mortgage processing stages
Processing depends on document accuracy, signer availability, and any state filing or notarization requirement.
Prepare the document
Deliver to signers
Complete signer review
Archive and file
Legal standing of a Chattel Mortgage
A Chattel Mortgage may be admissible when the parties show intent, consent, attribution, and preserve an accurate electronic record under ESIGN and applicable UETA law. Electronic signing does not replace state filing or notarization rules. ESIGN exclusions include wills, certain court orders, family law decrees, and specified UCC instruments.

Chattel Mortgage signing questions and fixes
Resolve document-specific signing, authentication, plan, and compliance questions before treating a Chattel Mortgage as complete.
signNow Business includes legally binding eSignatures, templates, audit trails, and mobile apps. For a Chattel Mortgage, upload the completed document, place required signer fields, and send it through the signing workflow. ESIGN and UETA support electronic-signature validity, subject to applicable state filing and notarization rules.
Business Premium adds bulk send, but a single Chattel Mortgage normally requires individualized collateral, borrower, lender, and loan details. Use separate documents unless every recipient receives identical terms. Enterprise adds conditional and formula fields when variable calculations or signer routing require additional controls.
signNow’s audit trail records signer actions, timestamps, and document history, supporting evidence of intent and attribution. It does not replace state recording, UCC filing, notarization, or lender-specific requirements. Confirm the jurisdiction’s execution and perfection rules before relying on the completed document.
HIPAA compliance applies when protected health information is handled and requires a business associate agreement. A Chattel Mortgage usually concerns personal property and financing details, not PHI. Do not select a HIPAA workflow unless the transaction genuinely includes health information covered by HIPAA.
The Business plan is listed at $8 per user monthly with annual billing and includes 100 signature invites per user annually. A Chattel Mortgage workflow may incur overage fees after that allowance. Business Premium is listed at $15 and includes bulk send.
Electronic signing can satisfy ESIGN and UETA requirements when intent, consent, attribution, and record retention are established. Consumer transactions also require the disclosure rules in 15 U.S.C. §7001(c). State law may still require notarization, recording, or a particular filing method.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.