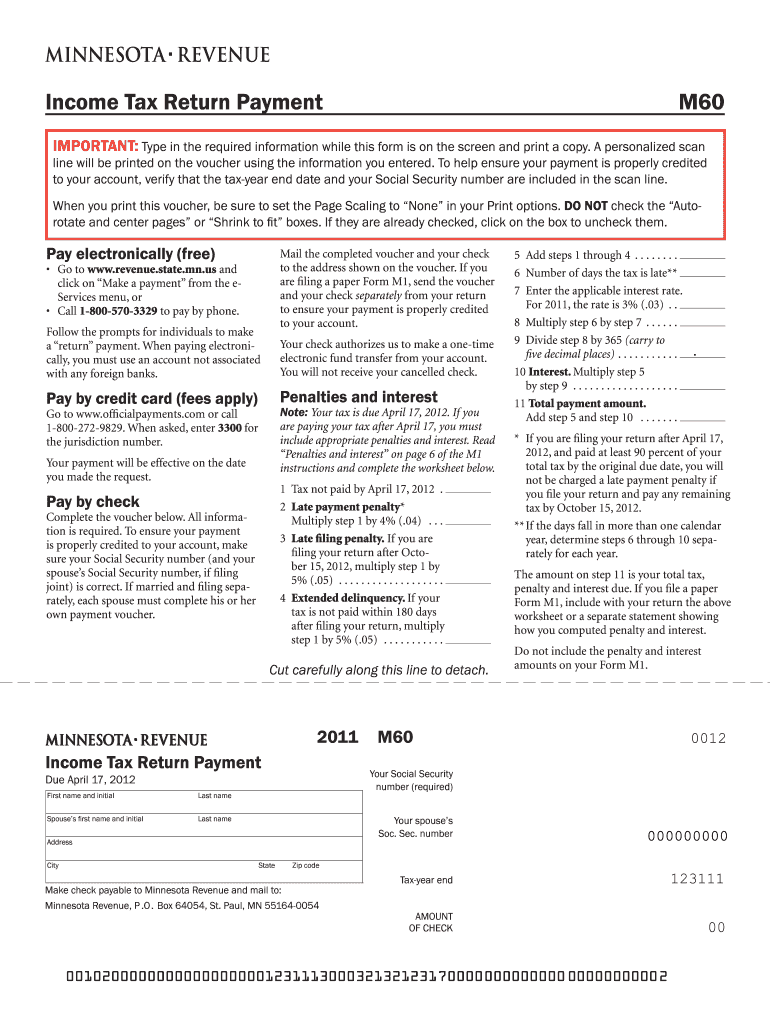
Minnesota Estimated Tax Voucher Form
Use a Minnesota Estimated Tax Voucher template to make your document workflow more streamlined.
Minnesota estimated tax voucher overview
The Minnesota Estimated Tax Voucher Form records an estimated state tax payment for the taxpayer and tax period identified on the voucher. It is used with the payment process rather than as a substitute for the taxpayer’s complete Minnesota return. A preparer can upload the voucher to signNow, review detected fields, enter or verify taxpayer and payment information, assign signature fields, and send it for electronic signature. The completed voucher, signing events, and audit trail can then be retained together. Confirm current instructions and filing requirements with Minnesota tax authorities before submission.
Features for Minnesota voucher workflows
signNow combines field preparation, signer routing, audit evidence, and storage options for organizations processing Minnesota estimated tax vouchers.
Field detection
Upload the Minnesota voucher and let signNow detect fillable areas before reviewing tax-period, taxpayer, and payment fields.
Signer routing
Assign the required preparer or taxpayer signature field and route the voucher to the correct signer.
Audit trail
Capture timestamps, signer actions, and document history so the completed voucher has supporting execution evidence.
Mobile signing
Use signNow’s mobile apps to review or sign the Minnesota voucher from a supported device when travel interrupts office processing.
Secure storage
Store the signed voucher with its completion certificate and audit trail for later tax-record review.
Business integrations
Connect completed voucher records with systems such as Google Drive, Box, NetSuite, or Microsoft 365.
How to complete the Minnesota voucher
Use the Minnesota voucher as the source document, verify every tax-period and payment field, then preserve the signed record and audit trail together.
Upload voucher:
Upload the Minnesota voucher PDF to signNow. Check fields:
Review detected fields and add missing tax details. Assign signer:
Assign the payer or preparer signature field. Send securely:
Send the completed voucher for electronic signature. Store records:
Download the signed voucher and audit trail.
Recommended voucher workflow setup
Configure the Minnesota voucher workflow around signer identity, record integrity, controlled access, and the applicable federal retention period.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification with SMS OTP |
| Signature type | Typed or drawn electronic signature |
| Audit trail | Capture timestamps, IP, and actions |
| Document retention | Keep three years from filing under IRC §6501(a) |
| Encryption and provisioning | AES-256 storage with controlled user access |
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
What the voucher audit trail records
The audit trail preserves signer identity evidence, timing, document integrity, and retrieval history for the completed Minnesota voucher.
Signer authentication:
Timestamp capture:
Document hashing:
Sealing evidence:
Event logging:
Audit retrieval:
Retention periods for voucher records
Keep the voucher, payment evidence, and related records according to the applicable federal rule and your organization’s tax policy.
Three years from filing
Six years for substantial understatement
Six years for HIPAA records
Three years for payroll records
Five years for injury records
Risks of incorrect voucher use
Reporting errors
IRS review
Record gap
Evidence dispute
Privacy and disclosure pitfalls
The voucher can expose taxpayer names, addresses, identification numbers, and payment details when shared through unsecured email or broad-access folders. A signer may complete the voucher without seeing the electronic-record disclosure required for consumer-facing transactions under 15 U.S.C. §7001(c). Unrestricted access can let unauthorized staff download taxpayer information or alter routing instructions without documented approval. Using an outdated voucher template can place the wrong tax period, payment amount, or taxpayer details on the submitted record.
Security for taxpayer records
Data encryption:
Transport security:
Security certification:
Control framework:
Privacy compliance:
Electronic signatures:



Best practices for Minnesota vouchers
Accurate fields, authorized signers, preserved audit evidence, and an authority-based retention schedule reduce avoidable processing and recordkeeping errors.
Verify every Minnesota voucher field
Confirm signer authority before sending
Preserve the signed record set
Apply the federal retention rule
Key performance indicators that demonstrate SignNow's proven track record.
Minnesota voucher troubleshooting
Resolve field, signer, retention, and electronic-signature questions before treating the completed Minnesota voucher as a final tax record.
Upload the current Minnesota voucher PDF again and inspect detected fields before sending. signNow’s field review lets you correct missing or misplaced signature, date, taxpayer, or payment fields before routing the document.
The Business plan includes legally binding eSignatures, templates, audit trails, and mobile apps at $8 per user monthly when billed annually. Confirm the plan’s current signature-invite allowance before processing higher volumes.
For consumer-facing electronic records, provide the ESIGN disclosure explaining paper-record rights, electronic access, and consent withdrawal procedures under 15 U.S.C. §7001(c). signNow can document the signing event, but your process must provide the disclosure.
Use email verification or stronger authentication, such as SMS OTP, when taxpayer information requires additional identity assurance. Review the audit trail for authentication events, timestamps, IP information, and signer actions.
Keep the voucher and payment evidence under the applicable tax-record schedule. IRC §6501(a) generally uses three years from filing; IRC §6501(e) extends the period to six years for substantial understatement.
ESIGN and UETA generally recognize electronic signatures when intent, consent, attribution, and reproducible records are established. Electronic signing does not replace Minnesota filing or payment instructions; verify the agency’s submission requirements separately.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.