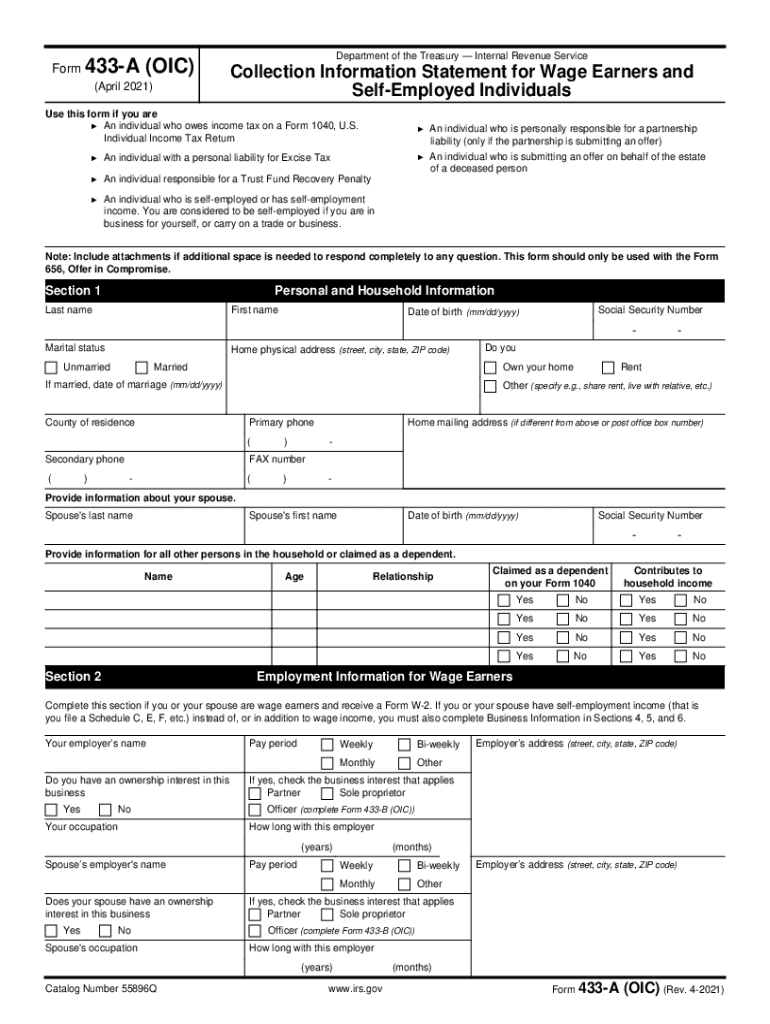
Form 433 A Oic Rev 4 Internal Revenue Service
Use a Form 433 A OIC Rev 4 Internal Revenue Service template to make your document workflow more streamlined.
What Form 433-A means for an offer in compromise
Form 433-A OIC is the IRS financial statement used to disclose an individual taxpayer’s financial condition in an offer-in-compromise process. It organizes information about income, assets, liabilities, monthly expenses, and other financial circumstances so the Internal Revenue Service can evaluate the taxpayer’s ability to pay. Revision 4 identifies the specific version being prepared. signNow can help complete and route the electronic document, capture signatures, and preserve an audit trail, but it does not decide eligibility, calculate the IRS offer amount, or replace the current IRS instructions and submission requirements.
Who uses Form 433-A and why
Individual taxpayers
Taxpayers use Form 433-A OIC to provide the IRS with a structured statement of income, assets, liabilities, and expenses during an offer-in-compromise review.
Tax resolution firms
Tax professionals prepare and review Form 433-A, coordinate supporting records, and route the completed statement for taxpayer signature before submission.
Who benefits from Form 433-A workflows
Form 433-A is most useful to taxpayers and tax professionals documenting financial information for an IRS offer-in-compromise process.
Solo tax practitioners can prepare a taxpayer’s Form 433-A, route signature fields, and retain the completed financial statement with its audit trail for the client file. Tax resolution firms can use reusable Form 433-A templates, delegated sending, and controlled access while coordinating taxpayer signatures and supporting-document review. Enterprise tax departments can standardize Form 433-A workflows across authorized staff, connect records to approved storage, and apply retention policies for IRS correspondence.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
How the Form 433-A workflow works
Form 433-A moves from financial disclosure through signature and record preservation; IRS eligibility and submission decisions remain separate.
Complete disclosures: Enter financial information from current records. Add evidence: Attach supporting documents required for review. Request signature: Route Form 433-A to the taxpayer. Retain evidence: Preserve the signed record for submission.
How to complete Form 433-A in signNow
Prepare the IRS form in signNow, route it to the correct signer, and preserve the completed record with its audit evidence.
Upload form:
Upload the IRS Form 433-A PDF. Place fields:
Let signNow detect fields or add them manually. Assign signers:
Assign the taxpayer and any required signers. Send request:
Send the form for electronic completion. Store record:
Review the signed PDF and audit trail.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
What the Form 433-A audit trail records
A signNow audit trail preserves the electronic evidence surrounding Form 433-A completion, helping reviewers connect signer activity with the final record.
Signer authentication:
Timestamp capture:
Document integrity:
Tamper-evident sealing:
Audit history:
Retrieval and export:
Key signNow features for Form 433-A
signNow helps organize Form 433-A completion, signer routing, evidence capture, and record preservation without replacing the IRS form instructions or submission process.
Reusable template
Upload the Form 433-A PDF, add missing fields, and maintain a reusable template for repeated taxpayer workflows without re-creating the document structure.
Signer routing
Send the completed Form 433-A to the taxpayer or authorized signer by email, then track signature status from the signNow workspace.
Audit trail
Capture signer actions, timestamps, and completion history with the Form 433-A so reviewers can examine the electronic signing record.
Mobile signing
Use signNow mobile apps to review or sign Form 433-A from an iOS or Android device when desktop access is unavailable.
Team permissions
Apply role-based workspace permissions so tax professionals, administrators, and delegated senders handle Form 433-A according to internal responsibilities.
Record preservation
Store the completed Form 433-A with its audit evidence and export the record when IRS correspondence or internal review requires it.
Platform requirements for Form 433-A
Complete Form 433-A through signNow using Chrome, Firefox, Safari, or Edge on Windows or macOS. signNow also provides mobile apps for iOS and Android, supporting review and signing away from a desk.
Supported browsers Chrome, Firefox, Safari, and Edge Desktop systems Windows and macOS desktop access Mobile systems iOS and Android mobile apps
Organizations should manage access to Form 433-A through approved devices, controlled accounts, and appropriate permissions. Enterprise deployments may also require API access, SSO provisioning, and retention controls aligned with IRS recordkeeping obligations and the organization’s tax-practice policies.
Recommended Form 433-A workflow setup
Configure Form 433-A for clear signer attribution, preserved evidence, controlled access, and retention aligned with IRS tax-record requirements.
| Form 433-A setting | Recommended configuration |
|---|---|
| Authentication method | Email verification with optional SMS authentication |
| Signature type | Electronic signature with signer intent |
| Audit trail | Enabled with completion history |
| Document retention | Three years from filing under IRC §6501(a) |
| Encryption | TLS 1.2/1.3 and AES-256 protection |
How long to retain Form 433-A records
Retention depends on the tax record, understatement, fraud, and electronic-record requirements applicable to the Form 433-A submission.
Three years from filing
Six years for understatement
Indefinite for fraud
Matter-specific active period
Electronic record preservation
Best practices for Form 433-A records
Use a documented retention and access process that preserves the Form 433-A, supporting evidence, and signNow completion record together.
Apply the correct IRS retention period
Export the completed form and audit trail
Protect sensitive financial information
Preserve the original submission history
Security for Form 433-A records
Encrypted stored records:
Protected data transfer:
Independent controls report:
Certified security management:
Electronic signature compliance:
Protected health information:
Challenges when completing Form 433-A
Entering household income, assets, liabilities, and expenses inconsistently can make the Form 433-A financial statement difficult for the IRS to evaluate. Uploading an incomplete Form 433-A without supporting financial records can delay review or prompt a request for additional information. Using an outdated revision or omitting required signatures can undermine the completeness of an offer-in-compromise submission. Sending sensitive tax information to unauthorized recipients can expose taxpayer data and weaken internal access controls.
Risks of mishandling Form 433-A
IRS requests more information
Offer evaluation may change
Submission may remain incomplete
Taxpayer data is exposed
Troubleshooting Form 433-A workflows
These answers address field detection, electronic consent, IRS submission limits, plan capabilities, audit evidence, and sensitive information handling.
Upload the IRS Form 433-A PDF again and inspect whether signNow detected its fillable fields. If fields are absent, add the required text, date, checkbox, and signature fields manually before sending the document.
The signNow Business plan includes templates and audit trails at $8 per user per month with annual billing. Business Premium adds bulk send at $15, while Enterprise adds advanced signer authentication at $30.
A signature request does not replace IRS submission requirements. signNow can document completion and provide an audit trail, but confirm the current Form 433-A instructions and IRS delivery method before treating the file as submitted.
For a consumer-facing electronic record, obtain electronic consent and provide the required paper-record disclosure under ESIGN, 15 U.S.C. §7001(c). Preserve evidence that the signer could access the electronic Form 433-A.
Use signNow’s audit trail to review timestamps, signer actions, and completion history. ESIGN and UETA support electronic records when intent, consent, attribution, and reliable retention and reproduction are established.
If Form 433-A contains protected health information, signNow identifies HIPAA compliance as requiring a business associate agreement. Confirm that agreement and your access controls before including PHI in the workflow.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.