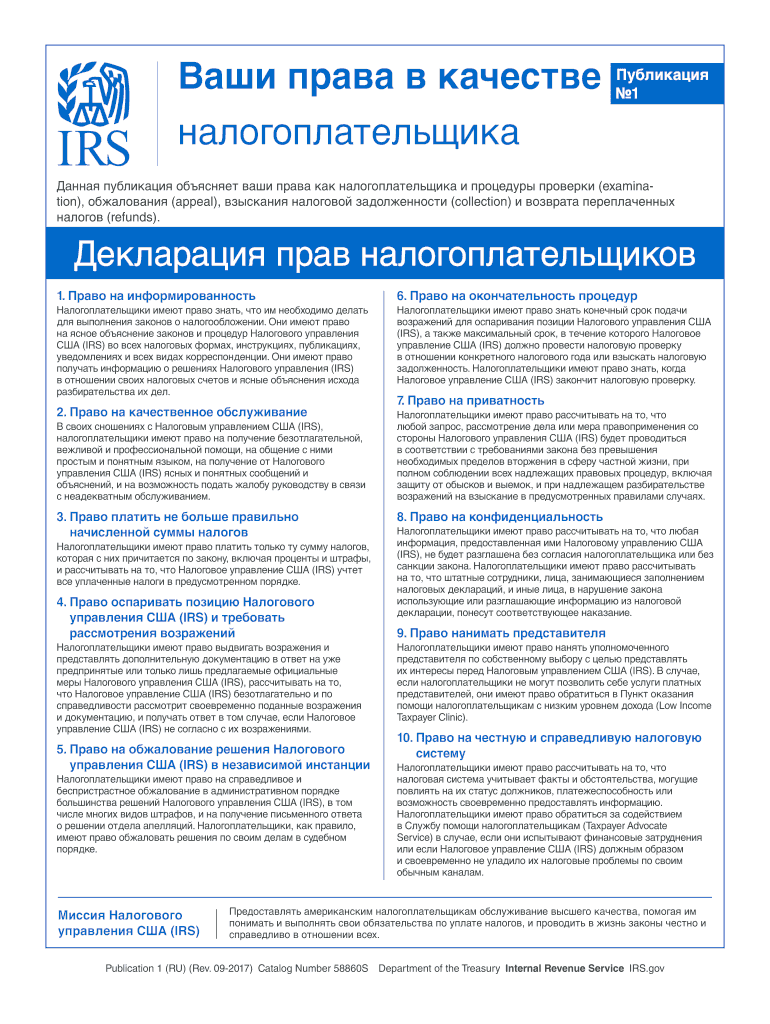
Publication 1 Ru Rev 09 Your Rights As A Taxpayer Russian Version Form
Use a Publication 1 RU Rev 09 Your Rights As A Taxpayer Russian Version template to make your document workflow more streamlined.
What Publication 1 explains
Publication 1, “Your Rights as a Taxpayer,” is an IRS publication that explains the protections and service expectations available to taxpayers during federal tax administration. The Russian version presents that information for Russian-speaking readers; it is not a return, payment voucher, election, or standalone claim for an IRS benefit. Organizations can distribute the publication, add a clearly labeled receipt acknowledgment, and use signNow to collect that acknowledgment with an audit trail. Any actual filing deadline, tax payment, appeal, or submission must come from the applicable IRS notice, form, or tax rule—not Publication 1.
Who uses the Russian rights publication
Taxpayer service teams can distribute the Russian publication alongside IRS correspondence, then document receipt when internal procedures require evidence that rights information was provided. The acknowledgment should identify the communication purpose without implying that the taxpayer filed a return or made a tax election through signNow. Tax professionals and financial-services teams can use a controlled acknowledgment workflow for Russian-speaking clients who need accessible taxpayer-rights information. Staff should preserve the IRS source, identify any translation, and route tax returns, authorizations, and appeals through their separate legally applicable processes.
Key benefits of the Russian taxpayer rights publication
Publication 1 explains taxpayer protections and IRS service expectations; a controlled signNow workflow can document distribution and acknowledgment without replacing an IRS filing.
Rights review
Review the IRS taxpayer rights described in Publication 1 and organize internal acknowledgments or educational workflows without changing the publication’s official content.
Russian access
Use a Russian-language version to help taxpayers understand IRS communications, while preserving the English-language source and checking translation accuracy before relying on it.
Receipt confirmation
Add signer fields to an internal acknowledgment copy, allowing recipients to confirm receipt without treating the signed copy as an IRS filing.
Audit evidence
Capture signer identity, timestamps, and document history when an organization distributes Publication 1 for documented taxpayer communication procedures.
Controlled delivery
Route the publication to taxpayers, representatives, or service teams through a controlled workflow that records who received the material and when.
Record separation
Store the completed acknowledgment and audit trail separately from tax returns, preserving a clear distinction between taxpayer education and tax filing records.
How to manage Publication 1 workflows
Publication 1 is an IRS taxpayer-rights publication, not a substitute for a return; use signNow to document controlled distribution or acknowledgment.
Prepare document: Upload the Russian Publication 1 file or an acknowledgment copy. Check fields: Review detected fields and add recipient information manually. Deliver securely: Send the document to the intended taxpayer or representative. Store evidence: Capture acknowledgment and retain the completed record separately.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
What the Publication 1 audit trail records
The audit trail documents the acknowledgment event around Publication 1, rather than asserting that the publication itself is an electronically filed IRS return.
Authenticate signer:
Timestamp activity:
Hash document:
Seal record:
Track activity:
Retrieve evidence:
Ways to send and acknowledge Publication 1
- Use the web app when staff need to upload the Russian publication, review fields, configure recipients, and monitor acknowledgment status from a desktop workflow.
- Use the mobile app when a taxpayer or representative reviews the publication away from a desk and needs to sign an acknowledgment on an iOS or Android device.
- Use kiosk mode for supervised, in-person distribution where staff control the device and guide a recipient through a clearly labeled receipt acknowledgment.
- Use a shareable signing link when the same acknowledgment copy must reach recipients through an approved channel without creating a separate email invitation for every recipient.
Challenges when distributing Publication 1
Treating Publication 1 as a tax return can lead teams to seek a filing deadline or submission method that the publication itself does not require. Using an unofficial Russian translation may create wording differences that obscure the IRS taxpayer rights described in the official publication. Sending the publication without identifying the recipient can make it difficult to prove who received taxpayer-rights information and when. Combining the publication with unrelated tax forms can confuse an acknowledgment record with an IRS filing or supporting tax document.
Legal standing of a signed acknowledgment
Publication 1 communicates IRS taxpayer rights; it does not itself create a tax liability or replace a return. A separate acknowledgment may be admissible under ESIGN and applicable UETA rules when intent, consent, attribution, and reliable record retention are shown, subject to statutory exclusions and state requirements.

Best practices for using Publication 1
A careful workflow separates the IRS taxpayer-rights publication from any acknowledgment, translation, or tax filing record created around it.
Preserve the IRS source
Define the signature purpose
Limit required fields
Archive with context
Signer authentication for Publication 1
Digital certificates:
Certificate format:
Second-factor protection:
SMS verification:
Identity verification:
Evidence capture:
Platform requirements for Publication 1 workflows
Use current Chrome, Edge, Safari, or Firefox on Windows or macOS, with TLS 1.2 or TLS 1.3 protecting signNow connections. signNow mobile apps support iOS and Android, allowing recipients to review and acknowledge the Russian publication from supported mobile devices.
Windows browsers Chrome and Edge macOS browsers Safari and Firefox Mobile apps iOS and Android
Organizations should manage access through approved devices and identity controls, especially when acknowledgment records accompany taxpayer correspondence. Teams connecting signNow to Microsoft 365, Google Drive, or other approved systems should configure permissions, retention, and export procedures separately; the platform does not determine the IRS filing or retention rule.
Publication 1 troubleshooting questions
These answers distinguish the IRS publication from an acknowledgment workflow and identify the signNow controls relevant to distributing it.
Upload the Russian Publication 1 PDF or the acknowledgment copy again, then review signNow’s detected fields. If no fields appear, place the recipient, date, and signature fields manually; do not assume the publication’s printed text is a fillable IRS form.
Use signNow’s Business plan for templates, audit trails, and mobile apps at $8/user/month with annual billing. The plan includes 100 signature invites per user annually; overage terms apply, so confirm expected acknowledgment volume before rollout.
For a consumer-facing electronic acknowledgment, provide the ESIGN disclosure, explain the right to receive paper records, confirm electronic access, and describe withdrawal procedures under 15 U.S.C. §7001(c). The publication itself does not waive those requirements.
A signed acknowledgment can evidence intent and attribution when the signer knowingly confirms receipt, but it does not prove an IRS filing. ESIGN and UETA address electronic records; they do not change Publication 1’s informational purpose.
Business Premium costs $15/user/month with annual billing and includes bulk send, which can help distribute repeated acknowledgment copies. Enterprise costs $30/user/month and adds advanced signer authentication; neither changes the publication’s IRS status.
Restrict access to the completed PDF and audit trail, use signNow’s available authentication controls, and preserve the record in a system governed by your tax-document policy. Select retention based on the surrounding record category and applicable IRS rule.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.