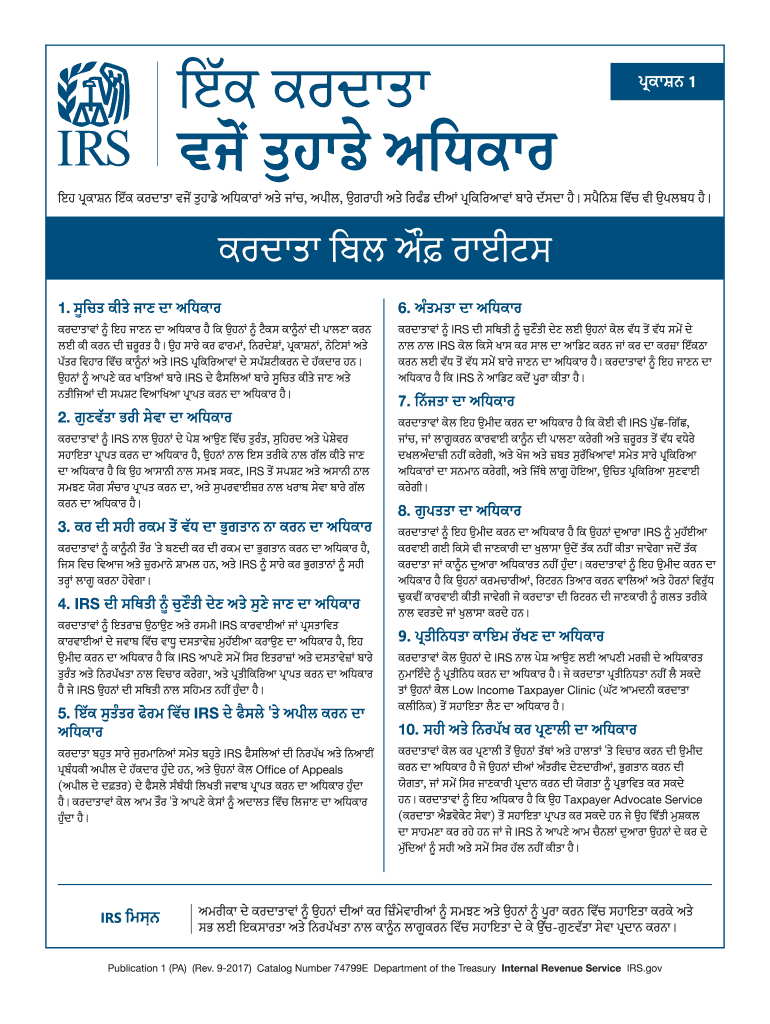
IRS Publication 1 Form
Use a Irs Publication 1 template to make your document workflow more streamlined.
What IRS Publication 1 covers
IRS Publication 1 is an IRS taxpayer-rights publication, not a standard tax return or information-return form. It explains the Taxpayer Bill of Rights, including the right to be informed, quality service, paying no more than the correct amount, challenging the IRS, and receiving a fair and just tax system. A user may place the publication or an associated acknowledgment into a signNow workflow for review, consent, or recordkeeping. The IRS remains the authority for its contents; signNow manages preparation, routing, signatures, and audit evidence.
Legal standing and document limits
An electronic record connected to IRS Publication 1 can support business evidence when the signer shows intent, consents where required, and the record remains attributable and reproducible under ESIGN, 15 U.S.C. ch. 96, and applicable UETA law. ESIGN exceptions still include wills, certain court orders, and family-law decrees.

Who benefits from IRS Publication 1
The document is most useful where taxpayer information, review responsibilities, and signed records must remain organized.
Solo tax practitioners can collect taxpayer acknowledgments and supporting information in a controlled document workflow, then retain the completed record with its signing history for client files. Small accounting firms can route IRS Publication 1 materials to clients, use reusable templates for recurring engagements, and maintain a consistent record of who reviewed or signed each document. Enterprise finance departments can connect document workflows with internal controls, assign authorized senders, and preserve completed IRS-related records alongside broader tax and payment documentation.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
How the document workflow works
Prepare the IRS Publication 1 document in signNow, route it to the intended signer, and preserve the completed record with its audit trail.
Select document: Start with the IRS Publication 1 document Prepare fields: Upload it and identify available fields Request signatures: Send the prepared record to authorized signers Archive record: Store the completed copy and audit trail
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
What the audit trail records
For an IRS Publication 1 workflow, the audit trail connects signer identity, document activity, timing, and retrieval evidence without replacing the underlying IRS requirements.
Authenticate signer:
Capture timestamp:
Track document:
Seal record:
Log actions:
Export trail:
Recommended workflow configuration
Configure the IRS Publication 1 workflow around signer attribution, controlled access, and retention aligned with the applicable IRS recordkeeping requirement.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification with SMS OTP |
| Signature type | Electronic signature with recorded intent |
| Audit trail and encryption | Audit trail with TLS and AES-256 |
| Document retention | Retain three years from filing under IRC §6501(a) |
| User provisioning | Authorized senders with role-based access |
Security for IRS Publication 1
Data encryption:
Security assurance:
Security certification:
Health data:
Signature laws:
Encryption standards:
Privacy and disclosure pitfalls
Entering taxpayer information into an unofficial copy can expose sensitive identification data to unauthorized recipients. Leaving signer consent undocumented can weaken evidence that the person intended to approve the electronic record. Sharing completed records through unrestricted links can expose taxpayer information beyond the intended payer or organization. Failing to review names, taxpayer identification numbers, and payment details can create reporting or reconciliation errors.
Recordkeeping practices for IRS Publication 1
Use a documented retention, access, and audit process for every completed IRS Publication 1 workflow.
Set retention from the tax statute
Export the audit trail
Limit access to taxpayer records
Review related tax details
Platform requirements for the document
Use signNow through Chrome, Firefox, Safari, or Edge on Windows or macOS. Mobile access is available through iOS and Android applications.
Supported browsers Chrome, Firefox, Safari, and Edge Desktop systems Windows and macOS desktop access Mobile systems iOS and Android mobile access
Organizations should confirm managed-device policies, browser updates, and access permissions before routing IRS Publication 1 materials. Enterprise deployments may also review API, SSO, and retention controls when records enter a regulated tax or finance archive.
Key performance indicators that demonstrate SignNow's proven track record.
IRS Publication 1 troubleshooting
Resolve document, signature, retention, and compliance questions by separating IRS requirements from signNow workflow settings.
signNow Business includes templates, audit trails, mobile apps, and legally binding eSignatures at $8 per user per month with annual billing. It includes 100 signature invites per user annually; overage fees may apply. The IRS, not signNow, determines the document’s tax use.
An electronic signature can support an IRS Publication 1 record when intent, consent, attribution, and record reproduction requirements are satisfied. ESIGN, 15 U.S.C. ch. 96, and applicable UETA law govern electronic transactions; retain the audit trail with the signed record.
Consumer-facing electronic records require an ESIGN disclosure explaining the right to paper records, electronic access, and withdrawal procedures under 15 U.S.C. §7001(c). Configure that disclosure before requesting a consumer’s signature on a related IRS workflow.
If the uploaded IRS Publication 1 file has no detectable fields, place the required text, signature, date, or acknowledgment fields manually in signNow. Verify the final document against the IRS source before sending it.
For federal tax records, IRC §6501(a) generally provides a three-year assessment period from filing, with six years when a return omits more than 25 percent of gross income. Apply the rule to the related tax record, not automatically to every publication copy.
If the workflow concerns a will, codicil, testamentary trust, court order, or family-law decree, do not assume signNow can replace required formalities. ESIGN’s exceptions and applicable state law may require a different signing or filing process.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.