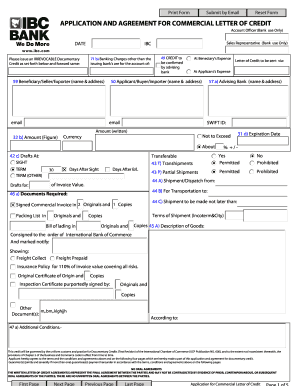
Letter Of Credit Application Form
Use a Letter Of Credit Application Form template to make your document workflow more streamlined.
What the application form does
A Letter Of Credit Application Form is a bank-facing request for a documentary credit that records the applicant, beneficiary, amount, currency, shipment terms, expiry, and required documents. The applicant submits it to a financial institution, which evaluates the requested credit and may issue a letter of credit subject to its approval and conditions. The bank’s undertaking is separate from the underlying sales contract. Because letters of credit are among ESIGN’s exclusions, including certain UCC Article 5 instruments, confirm with the issuing bank whether electronic signing is accepted before using a digital workflow.
Who uses this application form
Importers and exporters
Importers and exporters use the application to provide banks with transaction details for documentary credits, including beneficiary information, trade value, currency, shipment dates, and required presentation documents. Finance teams can route the completed request for internal approval before submitting it to the issuing bank.
Trade-finance teams
Trade-finance departments and commercial banks review applicant data, requested terms, collateral information, and document conditions before deciding whether to issue or amend a letter of credit. The form supports controlled collection of approvals but does not replace bank underwriting or legal review.
Businesses that use this form
Importers, exporters, banks, manufacturers, and distributors use the form when a transaction requires a documented request for bank-issued credit.
Import-export companies use the form to request documentary credit for defined shipments, giving banks applicant, beneficiary, amount, currency, expiry, and document-presentation terms before issuance. Commercial banks and trade-finance departments use structured applications to collect authorized requests, evaluate credit exposure, and maintain an approval record separate from the underlying sales contract. Manufacturers and distributors use controlled signing workflows when multiple officers must approve a bank request, while preserving amendments and supporting documents for later reconciliation.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
Letter of credit application challenges
Applicants may omit issuing-bank instructions, shipment terms, currency details, or required supporting documents, delaying credit review and approval. Inconsistent beneficiary names, invoice references, and payment terms can create discrepancies between the application and later documentary credit documents. Manual rekeying of applicant, account, and transaction details increases transcription errors before the letter of credit reaches bank review. Multiple approvers may sign different copies, making it difficult to prove which application version authorized the requested credit terms.
Complete the application step by step
Prepare the bank’s template, verify every trade term, collect authorized signatures, and preserve the final submission record.
Upload template:
Upload the bank’s current application template to signNow. Check fields:
Review detected fields and add missing trade details. Assign roles:
Assign applicant, guarantor, or approver roles. Send for approval:
Send the approved application for electronic signatures only after bank acceptance is confirmed. Store records:
Download the signed record and completion certificate.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Recommended workflow configuration
Configure the application workflow around bank acceptance, authorized signers, controlled access, and a complete record of approval activity.
| Setting | Recommendation |
|---|---|
| Authentication method | Two-factor authentication for approvers |
| Signature type | Bank-approved electronic signature |
| Audit trail | Retain completion certificate and action history |
| Document retention | Follow transaction-specific bank policy |
| Encryption | TLS in transit and AES-256 at rest |
Features for letter of credit applications
signNow organizes the Letter Of Credit Application Form workflow around accurate trade data, authorized approvals, signer evidence, and secure records.
Template-based completion
Upload the bank’s PDF template, place fields over applicant and approval areas, and preserve the exact trade terms without recreating the document manually.
Role-based routing
Assign signing and approval roles so the applicant, authorized officer, and internal reviewers act in the intended order before submission.
Audit evidence
Capture timestamps, signer identity, IP details, and document actions in an audit trail accompanying the completed application.
Signer verification
Use conditional access and two-factor authentication for sensitive trade details, subject to the bank’s accepted signing procedures.
Business integrations
Connect records with systems such as NetSuite, Salesforce, Microsoft 365, Google Drive, or Box for controlled retrieval and processing.
Centralized records
Store the completed application and certificate of completion together, helping finance teams reconstruct the approval record during bank inquiries.



Mobile options for trade applications
signNow mobile apps for iOS and Android can support reviewing and signing the Letter Of Credit Application Form when the issuing bank accepts electronic execution. Camera-based capture can help digitize supporting pages, while the bank’s submission requirements remain controlling.
Mobile apps iOS and Android apps Offline mode Offline signing availability Document capture Camera document capture
For controlled trade-finance deployment, use managed iOS or Android devices, role-based access, and approved storage policies. Confirm whether offline signing, electronic delivery, and any required certificate or authentication method satisfy the issuing bank’s procedures before relying on the mobile workflow.
Security for signed applications
Data in transit:
Stored document protection:
Independent controls:
Information security:
Electronic signature framework:
Signer verification:
How the audit trail records approval
The audit trail documents who accessed, reviewed, signed, and completed the Letter Of Credit Application Form, supporting controlled bank submission records.
Authenticate signer:
Capture timestamps:
Track document history:
Seal completion:
Preserve evidence:
Export audit trail:
Best practices for completing the form
Accurate trade terms and controlled approvals reduce discrepancies before the issuing bank reviews the application.
Reconcile every trade detail
Follow the issuing bank template
Control internal authorization
Archive the complete record
Legal standing of the application
For transactions within ESIGN and UETA, an electronic record and signature can satisfy writing and signature requirements when intent, consent, attribution, and reproducible retention are shown. However, ESIGN excludes certain UCC Article 5 letters of credit, so the issuing bank’s procedures control. Wills, court filings, and family-law decrees are also excluded.

Risks from incomplete applications
Incorrect trade terms
Document discrepancy
Missing audit trail
Uncontrolled access
Letter of credit application troubleshooting
Resolve bank-acceptance, field-mapping, signer-access, plan, and records questions before treating a completed application as ready for submission.
A letter of credit is among ESIGN’s listed exclusions for certain UCC Article 5 instruments. Ask the issuing bank whether this application may be electronically signed and whether it requires a wet-ink or bank-portal submission. signNow cannot change the legal or procedural requirements imposed by the bank.
Upload the bank’s current PDF and inspect signNow’s detected fields before sending. Compare each field with the bank template, especially applicant identity, beneficiary, amount, currency, shipment terms, expiry, and document conditions. Add missing fields manually and remove fields that do not belong on this application.
The Business plan includes audit trails and templates at $8 per user per month when billed annually. Business Premium is $15 per user per month annually and adds bulk send. Confirm that the selected plan’s features and signature method match the issuing bank’s requirements.
If a signer cannot access the application, verify the recipient address, resend the invitation, and confirm that the signer’s organization permits the delivery method. For sensitive trade workflows, enable stronger authentication where available and ensure the signer is authorized for the applicant or guarantor.
ESIGN and UETA generally recognize qualifying electronic signatures, but letters of credit and certain UCC instruments are excluded from ESIGN’s coverage. Retain evidence of intent, consent, attribution, and reproducibility, then follow the issuing bank’s specific execution and delivery instructions.
Export the completed PDF and audit trail from signNow, then store them with the bank’s acceptance, amendments, correspondence, and supporting trade documents. Retention depends on the transaction, bank policy, and applicable records rule; no single federal period applies to every letter of credit application.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.