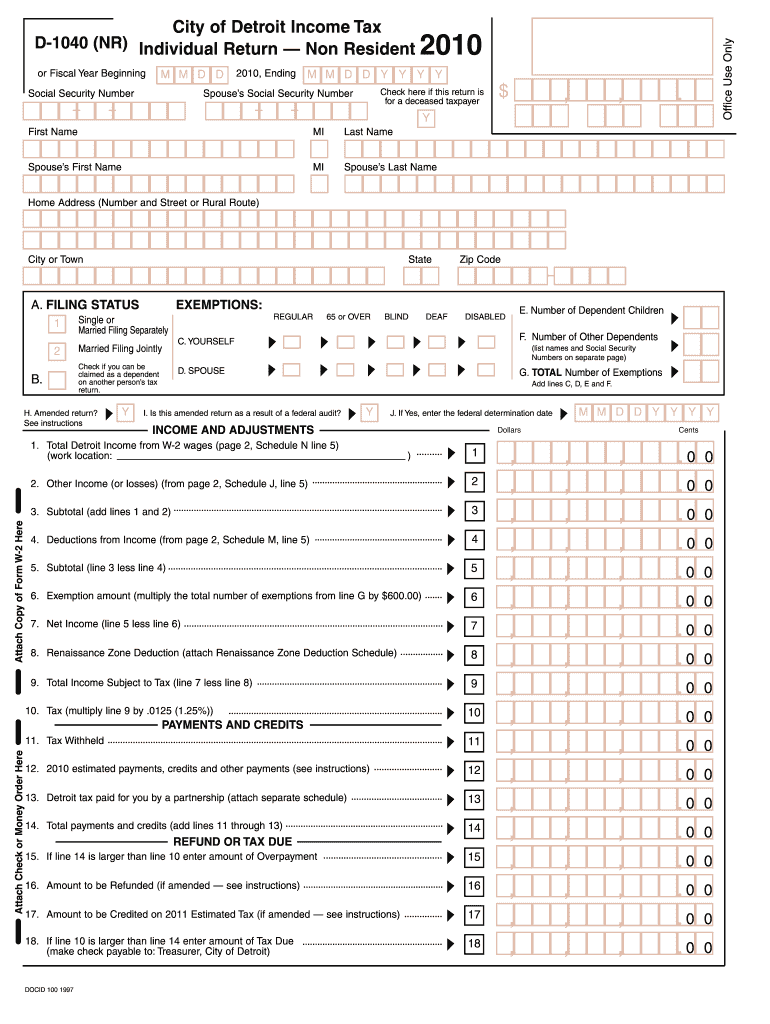
D 1040NR Form (2010)
Use a D 1040nr Form 2010 template to make your document workflow more streamlined.
What D 1040NR Form (2010) is
D 1040NR Form (2010) is a 2010-edition U.S. tax document that records information required from a nonresident taxpayer or related filer. Before using it, confirm that the recipient specifically requires this edition rather than a later IRS revision. Prepare the taxpayer’s identifying, residency, income, and withholding information from source records, then review the completed PDF. signNow can detect fillable fields, route the document to designated recipients, capture electronic signatures, and preserve the signed file with an audit trail.
Teams that manage this form
Tax preparers can upload the 2010 PDF, assign taxpayer or reviewer roles, and delegate sending while administrators retain control over templates and access permissions. Finance teams can maintain a controlled D 1040NR Form (2010) template, route completed records for review, and preserve the signed document with its audit trail.
Challenges when preparing D 1040NR Form (2010)
The 2010 edition may not reflect current IRS instructions, fields, or filing requirements for the taxpayer’s situation. Incorrect taxpayer identification, residency, income, or withholding details can create inconsistencies across supporting tax records. A completed signature page without the required supporting information may leave the submission incomplete or difficult to review. Saving an unsigned draft separately from the final signed record can weaken version control and auditability.
How to complete D 1040NR Form (2010)
Use this sequence to move the 2010 PDF from preparation through signing and controlled record storage in signNow.
Upload the form:
Upload the 2010 PDF into signNow. Check fields:
Review auto-detected fields and add missing fields. Assign recipients:
Assign the taxpayer, reviewer, or authorized signer. Send for signature:
Send the completed package for signature. Archive records:
Download the signed form and audit trail.
How the signNow workflow works
signNow moves this 2010 form from an uploaded PDF to a signed, auditable record through four controlled actions.
Upload: Upload the D 1040NR Form (2010) PDF to signNow. Prepare: Auto-detect fillable fields and add missing recipients. Send: Send the assigned form for secure signing. Store: Store the signed PDF with its audit trail.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Choose a signing method for this form
- Use the signNow web app when a preparer needs to upload D 1040NR Form (2010), verify fields, assign recipients, and monitor completion from a desktop browser.
- Use the signNow mobile app when an authorized signer needs to review or sign the prepared form from an iOS or Android device.
- Use kiosk mode when a supervised in-person workflow requires one device to collect a signer’s completed form without sharing the preparer’s account credentials.
- Use a shareable signing link when recipients should open the prepared D 1040NR Form (2010) from a controlled distribution channel rather than an individual email.
Recommended workflow setup
Use controlled authentication, field review, audit evidence, and retention aligned with the tax record’s applicable federal requirements.
| Setting | Recommendation |
|---|---|
| Authentication method | Email authentication with SMS OTP |
| Signature type | Electronic signature with signer intent |
| Audit trail | Enable completion history and export |
| Document retention | Retain 3 years from filing (IRC §6501(a)) |
| Encryption | TLS 1.2/1.3 and AES-256 at rest |
Find and fill out the correct d 1040nr 2015 form
airSlate SignNow helps you fill in and sign documents in minutes, error-free. Choose the correct version of the editable PDF form from the list and get started filling it out.
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| MI D-1040(NR) - Detroit 2014 | 4.8 Satisfied (7054 Votes) | |
| MI D-1040(NR) - Detroit 2013 | 4.7 Satisfied (984 Votes) | |
| MI D-1040(NR) - Detroit 2011 | 4.8 Satisfied (221 Votes) | |
| MI D-1040(NR) - Detroit 2010 | 4.8 Satisfied (95 Votes) |
Security controls for signed tax records
Encryption at rest:
Encryption in transit:
Independent assurance:
Information security:
Electronic signatures:
Protected health information:
Platform requirements for completing the form
Complete D 1040NR Form (2010) in signNow through Chrome, Firefox, Safari, or Edge on Windows and macOS. Browser connections use TLS 1.2 or TLS 1.3, while signNow mobile apps support signing on iOS and Android devices.
Desktop browsers Chrome, Firefox, Safari, and Edge on Windows or macOS. Mobile browsers Safari on iOS and Chrome on Android devices. Connection security TLS 1.2 or 1.3 secures browser connections to signNow.
Organizations can manage access through supported browsers, iOS, and Android applications on managed devices. Business workflows can also use signNow API access, SSO provisioning, and configured certificate or long-term validation requirements when their internal controls require them.



Pricing and feature comparison
For D 1040NR Form (2010) workflows, signNow pricing and included capabilities are verified; competitor values remain unverified where the supplied data provides no figures.
| Features | signNow | DocuSign | Adobe Sign | PandaDoc | Dropbox Sign |
|---|---|---|---|---|---|
| Annual Business price | $8/user/month, billed annually | Not verified | Not verified | Not verified | Not verified |
| Free trial | 7 days, no credit card required | Not verified | Not verified | Not verified | Not verified |
| Bulk send | Available with Business Premium | Not verified | Not verified | Not verified | Not verified |
| Audit trails | Included with Business plan | Not verified | Not verified | Not verified | Not verified |
| HIPAA compliance | Compliant; BAA required | Not verified | Not verified | Not verified | Not verified |
Record-keeping practices for this form
Retention and audit controls should reflect the tax record’s filing circumstances, the 2010 edition, and the need to reproduce the final signed document.
Apply the correct IRS retention period
Export the audit trail with the form
Limit access to authorized tax personnel
Separate drafts from the final signed record
What the audit trail records
The audit trail documents signing evidence separately from the form’s tax content, helping reviewers reconstruct how D 1040NR Form (2010) was completed.
Signer authentication:
Timestamp capture:
Document history:
Tamper evidence:
Action logging:
Audit export:
Key performance indicators that demonstrate SignNow's proven track record.
Questions about completing this form
These answers address edition control, field detection, electronic consent, retention, and signNow configuration for D 1040NR Form (2010).
Upload the original D 1040NR Form (2010) PDF again and confirm that its pages are readable. signNow can auto-detect fillable fields, but the sender should review detected fields and add any missing signature or date fields before sending.
The signNow Business plan is listed at $8 per user per month when billed annually, with a seven-day free trial and no credit card required. Confirm the selected plan and billing cycle before starting a recurring workflow.
For consumer-facing electronic records, ESIGN requires disclosure of the right to paper, electronic-access capability, and withdrawal procedures under 15 U.S.C. §7001(c). Add the required disclosure before requesting a consumer’s electronic signature.
Electronic signatures can have legal effect under ESIGN and UETA when intent, consent, attribution, and record reproducibility are established. Keep the completed PDF and signNow audit trail together as evidence of the signing event.
Business plans include audit trails, while signNow states that HIPAA compliance requires a business associate agreement. Do not place protected health information in this workflow unless the required agreement and controls are in place.
For tax records, IRC §6501(a) generally provides a three-year assessment period from filing, with six years for a 25% income understatement and indefinite retention for fraud or no return. Set retention according to the applicable circumstance.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.