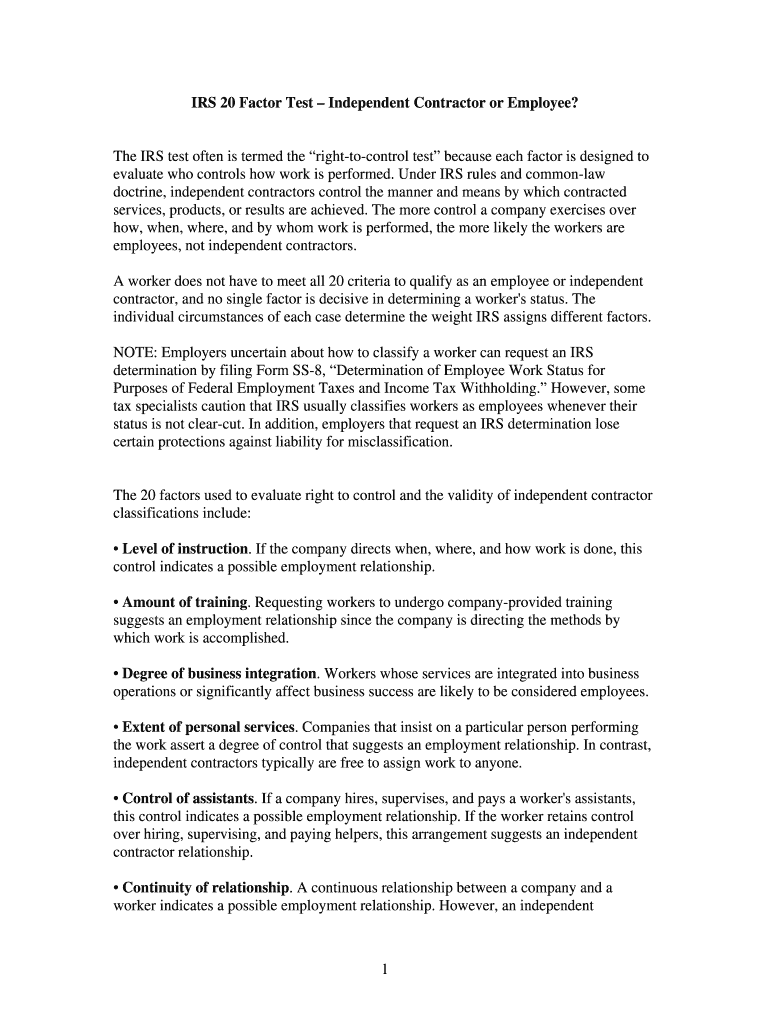
IRS 20 Factor Test Form
Use a Irs 20 Factor Test template to make your document workflow more streamlined.
What the IRS 20 Factor Test Form does
The IRS 20 Factor Test Form is a worksheet for documenting facts that help a payer evaluate whether a worker is an employee or an independent contractor. It examines behavioral control, financial control, and the relationship between the parties; no single answer decides the result. The form supports a facts-and-circumstances analysis rather than replacing IRS guidance or a formal determination. Businesses should preserve the completed form with contracts, invoices, and other evidence supporting the classification decision.
Who uses the IRS 20 Factor Test Form
Payers and employers
Businesses use the IRS 20 Factor Test Form to document whether a worker relationship reflects behavioral control, financial control, and the parties’ relationship. It supports a classification file but does not replace the IRS’s facts-and-circumstances analysis.
Tax and legal reviewers
Accountants, payroll teams, and legal reviewers use the completed form alongside contracts, invoices, correspondence, and payment records. signNow routes review signatures and preserves an Audit Trail for the final classification record.
How the IRS 20 Factor Test works
The IRS 20 Factor Test organizes facts about control and independence before a worker classification decision is made.
Gather facts: Identify the payer and worker relationship. Assess factors: Answer behavioral, financial, and control questions. Evaluate balance: Review the combined evidence objectively. Retain findings: Save the completed record for reference.
Complete the IRS 20 Factor Test Form
Use signNow to prepare the IRS 20 Factor Test Form, route it to the responsible reviewers, and preserve the signed evidence.
Upload form:
Upload the IRS 20 Factor Test Form to signNow. Check fields:
Review auto-detected fields and add missing fields. Add signers:
Enter each signer’s email and signing order. Send form:
Send the factor test for electronic signatures. Store records:
Download the signed PDF and Audit Trail.
Recommended IRS 20 Factor Test setup
Configure the workflow around signer attribution, evidence preservation, and the federal tax record period that applies to the classification decision.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification with SMS authentication |
| Signature type | Legally binding electronic signature |
| Audit trail | Enable completed-document Audit Trail |
| Document retention | Three years under IRC §6501(a) |
| Encryption | AES-256 at rest and TLS 1.2/1.3 in transit |
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
What the signNow Audit Trail records
The signNow Audit Trail documents authentication, signing events, and completed-record handling for the IRS 20 Factor Test Form.
Authenticate signer:
Capture timestamp:
Seal document:
Log activity:
Store completion:
Export evidence:
Retention periods for factor-test records
Use the federal tax assessment periods as a baseline for IRS 20 Factor Test Form records, then apply any longer rule governing the specific business or state record.
Three years after filing
Six years for major understatement
Indefinite period for fraud
Supporting tax records retention
Longer applicable state schedule
Record-keeping practices for the factor test
A defensible IRS 20 Factor Test Form record connects each answer to evidence, approval history, and an appropriate retention policy.
Retain supporting evidence with the completed test
Document facts behind every factor answer
Export the signed record and Audit Trail
Restrict access and review changed relationships
Risks of incomplete factor documentation
Worker status disputes
Incorrect worker reporting
Incomplete factor record
Unresolved classification
Privacy and disclosure pitfalls
Including Social Security numbers or bank details in the form can expose sensitive taxpayer information to unnecessary recipients and create avoidable disclosure risk. Sending the IRS 20 Factor Test Form without documented electronic consent can weaken evidence that each signer agreed to use electronic records under ESIGN. Granting broad workspace access may let unauthorized users view worker classification details, signed records, or Audit Trails containing personal information. Changing a factor answer after signature without preserving the original record can create conflicting versions and undermine the reliability of the classification file.
Security for IRS factor-test records
Data encryption:
Transport security:
Independent controls:
Information security:
Signer authentication:
Electronic signatures:



Legal standing of the completed factor test
The IRS 20 Factor Test Form records classification evidence; it does not itself determine worker status or replace IRS review. A signed electronic record may be admissible when intent, consent, attribution, and reliable retention are shown under ESIGN, 15 U.S.C. ch. 96, and applicable state law. Wills, court orders, and family law decrees remain outside ESIGN’s federal exceptions.

Key performance indicators that demonstrate SignNow's proven track record.
IRS 20 Factor Test Form troubleshooting
These answers address field preparation, electronic signing, retention, and signNow plan questions specific to the IRS 20 Factor Test Form.
Upload the IRS 20 Factor Test Form to signNow, then review the fields signNow detects automatically. Add fields for missing answers, explanations, dates, or signatures before sending the document to the payer, worker, or reviewer responsible for the classification record.
The Business plan includes legally binding eSignatures, templates, and Audit Trails at $8/user/month when billed annually. Business Premium is $15/user/month annually and adds bulk send, while Enterprise is $30/user/month annually and adds advanced signer authentication.
An electronic signature can support the completed IRS 20 Factor Test Form when the signer demonstrates intent, consents to electronic records, can be attributed, and the record remains reproducible. ESIGN, 15 U.S.C. ch. 96, and applicable state law govern the analysis.
Use signNow’s Audit Trail and retain the completed PDF with the supporting classification evidence. IRC §6501(a) generally provides a three-year federal assessment period, extending to six years for a substantial understatement and indefinitely for fraud or no return.
Keep the IRS 20 Factor Test Form separate from unrelated Form I-9, W-9, or payroll records unless those documents independently support the same classification decision. Each record should identify its purpose, signer, date, and relationship to the worker analysis.
SignNow supports AES-256 encryption at rest, TLS 1.2/1.3 in transit, SOC 2 Type II, ISO 27001, and ESIGN/UETA compliance. These platform controls do not determine worker status; the payer remains responsible for accurate facts and classification.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.