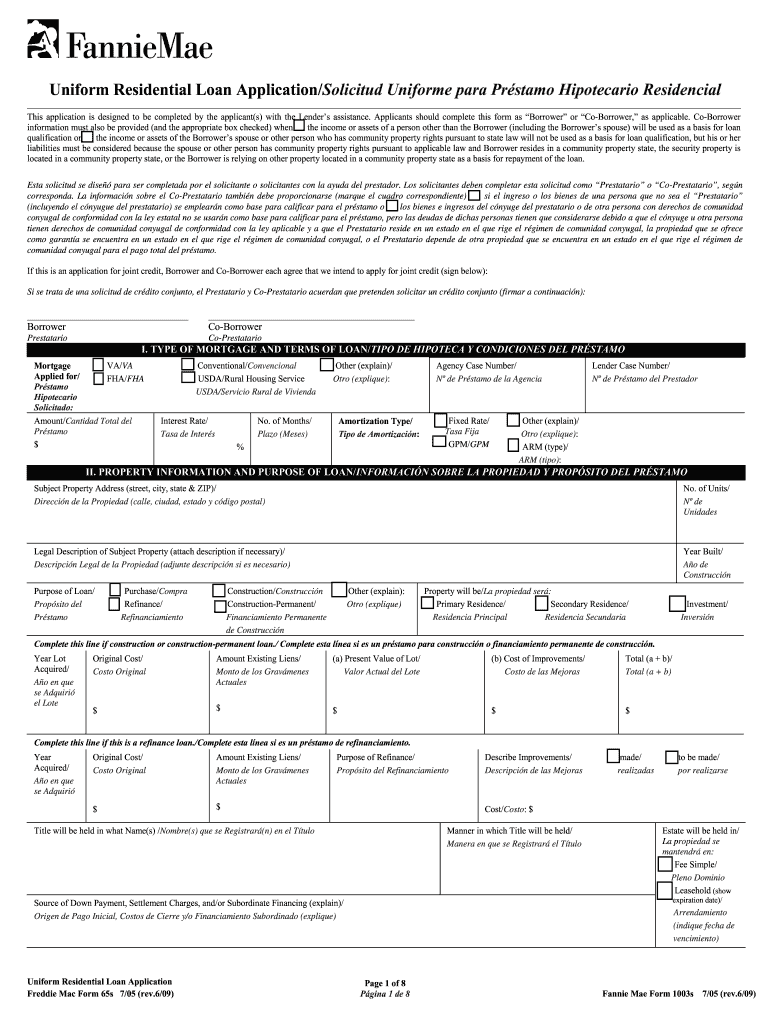
Blank 1003 Form
Use a Blank 1003 template to make your document workflow more streamlined.
What the blank 1003 Form is
The Blank 1003 Form is an uncompleted mortgage-loan application used to collect a borrower’s identity, property, income, assets, liabilities, and requested-loan information for lender review. A borrower and any co-borrower provide the applicable details, then review and sign the finished application. In signNow, the template can be uploaded, fields can be detected or placed, roles can be assigned, and the completed record can be retained with an audit trail. Lenders remain responsible for determining which supporting documents, disclosures, and underwriting requirements apply.
Who uses the blank 1003 Form
Mortgage brokers
Mortgage brokers use the blank 1003 Form to collect borrower and co-borrower information, property details, income, assets, liabilities, and required signatures before submitting an application for lender review.
Mortgage lenders
Mortgage lenders use the completed 1003 Form as an organized application record for underwriting intake, document review, borrower communication, and controlled signature collection through an auditable workflow.
Team controls for 1003 workflows
Mortgage brokerages can use shared templates, role-based permissions, and delegated sending to route each borrower’s blank 1003 Form without giving every team member unrestricted document access. Administrators can standardize fields and monitor signing activity through signNow controls and audit trails. Mortgage lenders and correspondent teams can assign preparation and signature responsibilities across branches while preserving a controlled template. Admins manage users, permissions, and shared documents; authorized staff send the application to borrowers and retain completed records with their transaction history.
How the blank 1003 form works
The blank 1003 Form becomes a structured mortgage application when its borrower, property, income, asset, liability, and signature fields are completed in sequence.
Upload template: Upload the blank 1003 template to signNow. Check fields: Review detected fields and add missing borrower fields. Assign roles: Assign sections to borrowers, co-borrowers, and lender staff. Complete record: Send the completed application for signatures and retain the audit trail.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
What the 1003 audit trail records
The signNow audit trail records technical events surrounding the Blank 1003 Form, helping reviewers connect signer identity, document integrity, and completion history.
Authenticate signer:
Capture timestamp:
Hash document:
Seal record:
Link activity:
Export trail:
Blank 1003 Form completion challenges
Borrowers may omit income, asset, liability, or occupancy details required for lender underwriting review. Hand-entered figures can differ from supporting statements, creating reconciliation questions before the application advances. Multiple borrowers may sign different versions when field assignments and document routing are not controlled. Incomplete dates, addresses, or signature fields can delay lender review and require a corrected application.
Features for blank 1003 workflows
signNow organizes the blank 1003 Form into a controlled workflow for field completion, borrower signatures, lender review, and auditable record handling.
Field detection
Auto-detected fields help identify borrower, property, financial, and signature areas after the blank 1003 template is uploaded, reducing manual document preparation before sending.
Role routing
Role assignments separate borrower, co-borrower, and lender actions so each participant receives the fields and signing tasks relevant to the mortgage application.
Reusable template
Reusable templates preserve the approved blank 1003 layout, field placement, and routing sequence for repeated mortgage application workflows.
Audit trail
Audit trails record signing events, timestamps, and document activity, creating a reviewable history alongside the completed application.
Mobile access
Mobile signing lets borrowers review and complete assigned 1003 fields from supported signNow apps when desktop access is unavailable.
Record access
Completed documents and signing records can remain together in a controlled workspace, supporting retrieval during lender review and internal quality checks.
Security for mortgage applications
Transport encryption:
Stored encryption:
Security certification:
Information security:
Privacy compliance:
Electronic signatures:
Recommended 1003 workflow setup
Configure the Blank 1003 Form around verified signer identity, controlled field ownership, audit evidence, and the lender’s records policy.
| Setting | Recommendation |
|---|---|
| Authentication method | Email link with SMS OTP |
| Signature type | Electronic signature with signer intent |
| Audit trail | Enable completion history and export |
| Document retention | Apply lender retention policy |
| Encryption | Use TLS and AES-256 protection |
Risks from improper completion
Delayed underwriting
Reconciliation review
Electronic record issue
Execution gap
Blank 1003 Form troubleshooting
Resolve field, routing, consent, authentication, and plan questions before the completed mortgage application enters lender review.
Upload the blank 1003 Form as a PDF or supported document, then use signNow’s field tools to identify or place borrower, co-borrower, date, and signature fields. Check every detected field before sending because signNow cannot determine lender-specific underwriting requirements from the template alone.
Create separate recipient roles for each borrower, co-borrower, and lender participant. Assign fields by role, review the routing order, and send a test workflow if needed. A shared template in signNow helps prevent one participant from receiving another participant’s private fields.
Use signNow’s audit trail to review signer identity events, timestamps, actions, and completion history. ESIGN and UETA recognize electronic signatures when intent, attribution, consent, and record reproducibility are established; lender procedures may require additional controls.
The Business plan includes legally binding eSignatures, templates, audit trails, and mobile apps. Business Premium adds bulk send, while Enterprise adds advanced signer authentication. Select a plan based on the lender’s workflow, not merely the number of Blank 1003 Forms.
For consumer-facing electronic records, ESIGN requires disclosure of the right to receive paper records, access to the electronic format, and a withdrawal procedure under 15 U.S.C. §7001(c). Establish that process before sending a Blank 1003 Form electronically to a consumer.
If a borrower cannot complete the form on a phone, signNow mobile apps and browser workflows provide alternative access. Confirm the PDF’s fields, signer permissions, and final document before resending; do not overwrite a completed application without following the lender’s correction procedure.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.