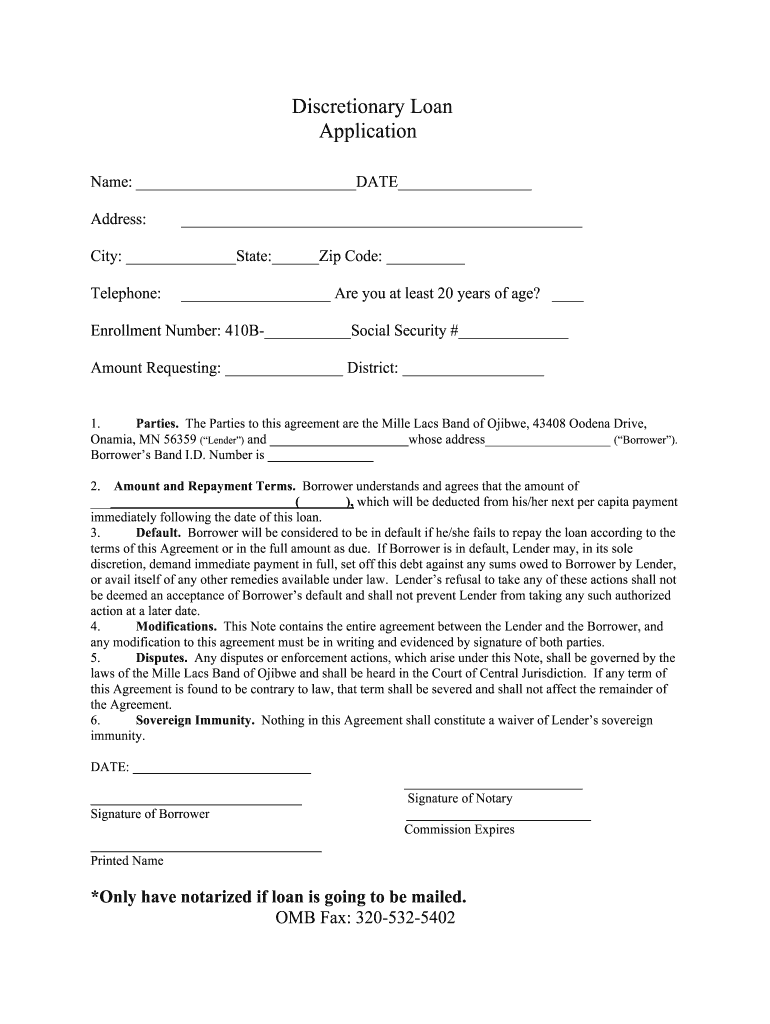
Discretionary Loan Form
Use a Discretionary Loan template to make your document workflow more streamlined.
What a discretionary loan form records
A Discretionary Loan Form records a lender’s decision to consider or approve credit outside a fixed lending program. It typically identifies the borrower, requested amount, purpose, terms, conditions, approving authority, and signatures. Because the exact fields depend on the lender’s policy, review the completed form against internal underwriting and state-law requirements. In signNow, upload the document, auto-detect or place fillable fields, assign borrower and approver roles, send it for signature, and retain the signed PDF with its completion certificate and audit trail.
Who uses a discretionary loan form
Lending teams
Banks, credit unions, and commercial lenders can use the form to document borrower information, requested credit, discretionary approval conditions, and authorized signatures. SignNow supports role-based routing, reusable templates, and an audit trail that helps staff preserve the completed loan record without relying on paper delivery.
Business finance
Businesses extending internal or supplier credit can use the form to capture a request, decision, repayment conditions, and management authorization. Finance staff can send the document from a signNow template, collect signatures in sequence, and store the final record with controlled access.
Complete a discretionary loan form online
Use this signNow workflow to prepare, route, sign, and retain the lender’s discretionary loan record.
Upload form:
Upload the lender’s approved Discretionary Loan Form. Check fields:
Review detected fields and add borrower or approver fields. Route signatures:
Assign signing order and send the form securely. Store record:
Review the completed PDF and audit trail.
Recommended loan form workflow settings
Configure the workflow around signer identity, clear intent, documented approvals, secure transmission, and the lender’s approved retention policy.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification with SMS OTP |
| Signature type | Intent-based electronic signature |
| Audit trail | Retain completion certificate and action log |
| Document retention | Follow lender policy and applicable state law |
| Encryption | TLS 1.2 or 1.3 in transit; AES-256 at rest |
How the loan form audit trail works
The audit trail preserves evidence about who handled the Discretionary Loan Form, when actions occurred, and whether the final record changed.
Authenticate signer:
Capture timestamp:
Hash document:
Seal record:
Log activity:
Export trail:
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Features that support discretionary loan forms
signNow features address the specific work of preparing, routing, signing, reviewing, and retaining a discretionary credit approval record.
Fillable fields
Upload the lender’s PDF and place or review fields for borrower information, loan terms, conditions, approvals, dates, and signatures before sending.
Role routing
Assign borrower, reviewer, and approving-authority roles so each person completes only the fields relevant to the discretionary credit decision.
Reusable templates
Use reusable templates to preserve the lender-approved structure and reduce omissions when staff prepare multiple discretionary loan requests.
Audit trail
Capture timestamps, recipient actions, and signature events in an audit trail that supports later review of the completed loan record.
Mobile signing
Collect signatures through signNow’s web and mobile experiences, allowing authorized borrowers and staff to review the document without exchanging paper copies.
System connections
Connect completed forms with business systems such as Salesforce, NetSuite, Google Drive, Box, or Microsoft 365 for controlled record handling.



Security controls for loan form records
Encryption controls:
Security certification:
Information security:
Electronic signature law:
Regulated health data:
Privacy compliance:
Best practices for completing loan forms
Apply these controls to keep the Discretionary Loan Form complete, attributable, reviewable, and aligned with the lender’s documented approval process.
Use the lender-approved template
Assign every field and signer
Archive the signed record securely
Reconcile terms before funding
Risks of incomplete loan documentation
Approval cannot be verified
Contract terms remain disputed
Attribution evidence is weaker
Reproduction may fail
Borrower data exposure
When electronic loan signatures carry legal weight
A discretionary loan form can generally be used as electronic evidence when the parties show intent, consent, signer attribution, and reliable record retention under ESIGN and applicable state law, including UETA or New York ESRA. Wills, codicils, testamentary trusts, court orders, and specified family-law filings remain excluded from ESIGN’s coverage.

Privacy and disclosure pitfalls to avoid
Placing borrower income, account, or identification data in unrestricted fields can expose sensitive information to recipients who do not need access. Sending a discretionary loan form without documented electronic consent can weaken evidence that the borrower agreed to use electronic records. Giving every team member shared credentials makes it difficult to attribute edits, approvals, and signature actions to a specific individual. Using an outdated loan-form template can omit approval conditions, repayment terms, or disclosures required by the lender’s current policy.
Platform requirements for loan forms
The Discretionary Loan Form can be prepared in signNow using Chrome, Firefox, Safari, or Edge on Windows and macOS. signNow also provides mobile apps for iOS and Android, allowing authorized users to review and sign from supported mobile devices. Use a TLS-enabled internet connection when accessing borrower information or submitting signatures.
Browser access Chrome, Firefox, Safari, and Edge on Windows or macOS Mobile apps signNow apps for iOS and Android Connection security TLS-enabled internet connection for signing
Lenders should manage access through approved devices, role-based permissions, and organizational identity controls. Teams using API access, SSO provisioning, or regulated workflows should confirm the required signNow plan and configuration before deployment. Retain the completed form, completion certificate, and audit trail according to the lender’s documented policy and applicable state requirements.
Troubleshoot discretionary loan form workflows
Find direct answers to field detection, signer access, legal validity, plan selection, notarization, and retention questions for this loan document.
Upload the lender-approved PDF again and inspect field detection before sending. signNow supports templates and fillable fields, but a scanned or unusual layout may require manually placing borrower, approver, date, and signature fields. Review the document visually before routing it.
Confirm that the recipient email address is correct, the signer has access to the signing link, and any required authentication method is configured. If the workflow requires stronger identity evidence, use available SMS or advanced authentication settings under the selected signNow plan.
An electronic signature can support a discretionary loan transaction when intent, consent, attribution, and record retention are established under ESIGN and applicable state law. signNow provides audit trails and completion records, but the lender remains responsible for disclosures and legal requirements.
Business includes legally binding eSignatures, templates, and audit trails. Business Premium adds bulk send and kiosk mode, while Enterprise adds advanced signer authentication and advanced fields. Confirm plan-specific features before designing a high-volume or regulated loan workflow.
Do not assume that an electronic loan signature replaces notarization or other state-law formalities. ESIGN and UETA do not cover wills, court orders, or specified family-law documents. Check the governing state law and lender policy when notarization or special execution is required.
Export the signed PDF, completion certificate, and audit trail from signNow, then place them in the lender’s controlled repository. Retention is not one universal period for every discretionary loan record; follow the applicable contract, policy, regulatory, and state-law schedule.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.