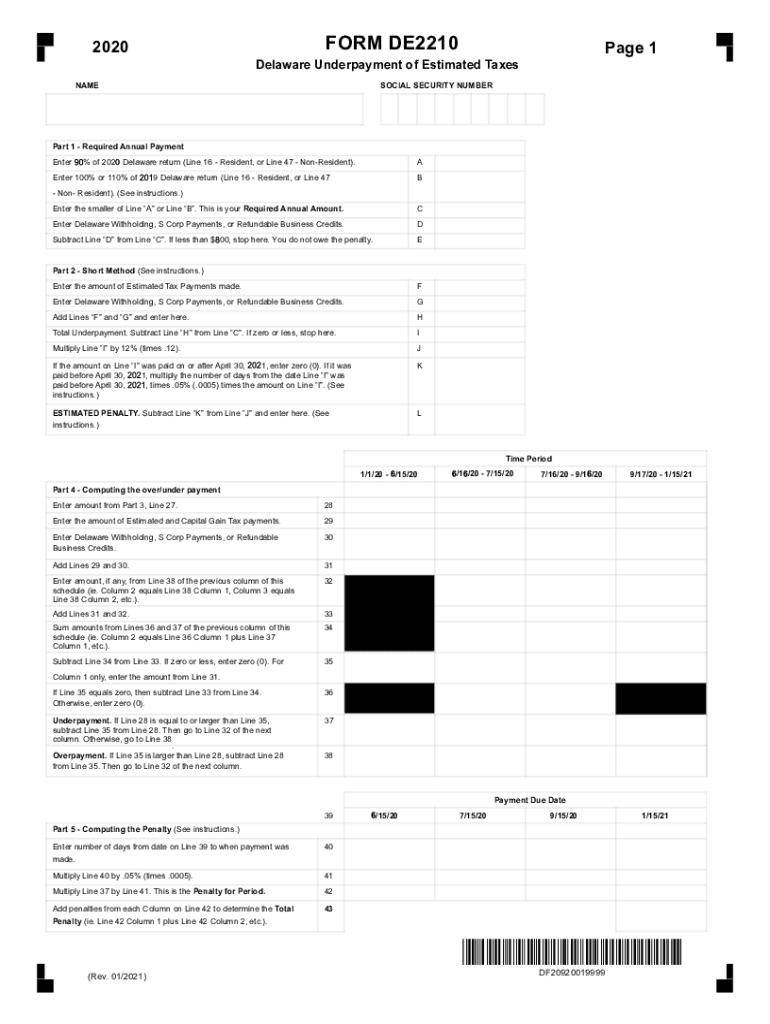
Penalty Who Must Pay The Underpayment Part I Required Instructions For Form 2210 Internal Revenue Serviceinstructions For Form 2
Use a Penalty Who Must Pay The Underpayment Part I Required Instructions For Form 2210 Internal Revenue ServiceInstructions For Form 2 2020 template to make your document workflow more streamlined.
What this Form 2210 instruction covers
This IRS instruction explains who may owe an estimated tax underpayment penalty and how Form 2210 information supports that determination. It helps taxpayers and preparers review required income, withholding, estimated payments, annualized income, and exception calculations before filing. The form’s Part I addresses the required-tax and withholding comparison; later sections determine whether an exception applies or calculate the penalty. Use the current IRS instructions and tax records for the applicable filing year, because the figures and filing requirements depend on the taxpayer’s facts.
How the Form 2210 review works
Form 2210 review follows the IRS sequence: establish the required tax, account for withholding and estimated payments, test applicable exceptions, and complete the relevant penalty calculation.
Review instructions: Review the IRS instructions and filing-year facts. Compare amounts: Compare required tax with withholding and payments. Check exceptions: Apply an available exception using supporting records. Finalize records: Complete the applicable penalty calculation and retain evidence.
Steps for completing Form 2210 records
Use this signNow workflow to prepare, route, sign, and preserve a Form 2210-related record without replacing the IRS calculation process.
Upload document:
Upload the Form 2210-related PDF to signNow. Check fields:
Review detected fields and add missing fields. Assign roles:
Assign taxpayer or preparer signing roles. Send and archive:
Send for signature and save the audit trail.
Recommended Form 2210 workflow setup
Configure the Form 2210 workflow around signer identity, review evidence, encryption, and the retention period applicable to the tax record.
| Setting | Recommendation |
|---|---|
| Authentication method | Email link with SMS OTP |
| Signature type | Typed or drawn electronic signature |
| Audit trail | Enabled for every completed record |
| Document retention | Three years from filing under IRC §6501(a) |
| Encryption | TLS 1.2/1.3 and AES-256 |
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Security for IRS form records
Transit encryption:
Stored encryption:
Control certification:
Security certification:
Signature compliance:
Privacy safeguards:
What the Form 2210 audit trail records
The audit trail documents the signing event around Form 2210 records; it does not determine the taxpayer’s IRS liability or calculate the penalty.
Authenticate signer:
Capture timestamps:
Record document history:
Seal completion:
Link evidence:
Export audit trail:
Find and fill out the correct penalty who must pay the underpayment part i required instructions for form 2210 2019internal revenue serviceinstructions for
airSlate SignNow helps you fill in and sign documents in minutes, error-free. Choose the correct version of the editable PDF form from the list and get started filling it out.
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| DE PIT-UND 2022 | 4.8 Satisfied (1792 Votes) | |
| DE PIT-UND 2021 | 4.8 Satisfied (2329 Votes) | |
| DE PIT-UND 2020 | 4.8 Satisfied (3604 Votes) |



Best practices for Form 2210 records
Accurate filing-year data, controlled signing roles, and documented retention decisions make Form 2210 records easier to review and defend.
Verify the filing-year instructions
Separate taxpayer and preparer fields
Preserve supporting payment evidence
Apply the correct retention rule
Form 2210 record retention schedule
Retention depends on the federal tax-record rule and the taxpayer’s filing circumstances. Keep the completed form, calculations, payment confirmations, and supporting records together.
Three years from filing
Six years for understatement
Indefinite for fraud
Indefinite without return
Payment evidence retained
Risks when Form 2210 data is incomplete
Calculation error
Incomplete evidence
Exception challenge
Interest exposure
Form 2210 troubleshooting questions
These answers address field setup, electronic signing, IRS calculation responsibility, and preservation of Form 2210 evidence.
Upload the IRS instruction or Form 2210 PDF to signNow and verify that detected fields align with the tax-year document. The Business plan includes templates and audit trails; review every imported field before sending.
Use signNow’s editable fields to identify the taxpayer, preparer, dates, amounts, and signature locations. Auto-detection assists setup but does not interpret IRS calculations or determine whether a penalty exception applies.
The Business plan provides legally binding eSignatures and audit trails, while Business Premium adds bulk send. Neither plan replaces IRS guidance or a tax professional’s review of filing-year calculations.
For consumer-facing electronic records, provide the ESIGN disclosure, confirm access to the electronic format, and explain withdrawal procedures under 15 U.S.C. §7001(c). Capture consent before requesting a signature.
Require the signer to review the completed Form 2210 information before signing. signNow records timestamps and document history, helping preserve evidence of the signing event, but the taxpayer remains responsible for accurate IRS reporting.
Export the completed document and audit trail from signNow, then store them with tax calculations and payment records. Apply the applicable IRC §6501 retention period and any longer business policy.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.