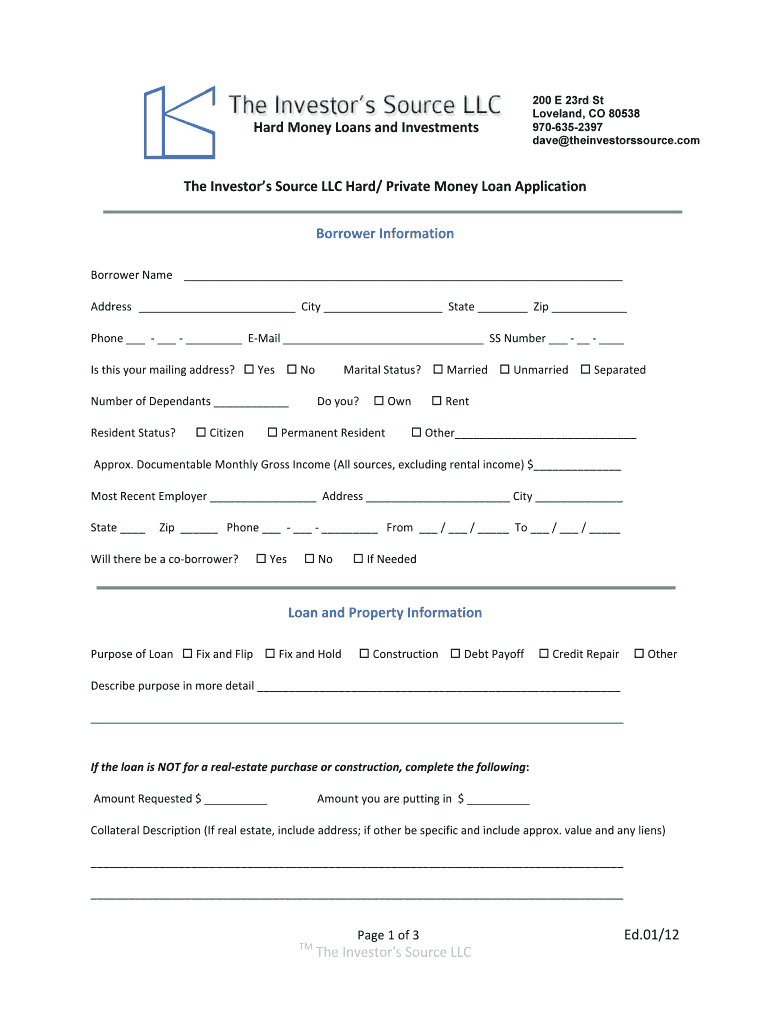
Hard Money Loan Application
Create a custom Hard Money Loan Application Pdf 2012 that meets your industry’s specifications.
What a hard money loan application does
A Hard Money Loan Application collects the borrower, property, financing, and repayment information a private or asset-based lender uses to evaluate a proposed loan. The applicant identifies the property, requested amount, purchase or refinance details, estimated value, intended use of funds, exit strategy, income, assets, liabilities, and relevant ownership information. Supporting records may include identification, bank statements, tax documents, and property materials. With signNow, a lender uploads the application, reviews detected fields, assigns signers, sends it for electronic signature, and stores the completed record with its audit trail.
Businesses that use hard money applications
The form fits lenders and real-estate finance teams that need structured borrower intake, property documentation, and signed approval records.
Independent hard-money lenders can use the application to collect borrower identity, requested loan amount, property address, purchase price, exit strategy, and supporting financial records before underwriting begins. Regional real-estate investment firms can route applications among acquisitions, underwriting, and compliance teams, preserving signed borrower disclosures and approval evidence for each property-backed financing decision. Private lending platforms can standardize intake across multiple originators by reusing a controlled template, assigning signer roles, and storing completed applications with their audit trails.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
How the application workflow works
The process moves from document preparation to borrower completion and controlled record storage.
Upload: The lender uploads the Hard Money Loan Application. Prepare: signNow identifies fields for borrower and property data. Route: The lender assigns signers and sends invitations. Complete: Signers complete fields and receive the executed record.
Complete the application in signNow
Use this workflow to move the Hard Money Loan Application from intake through signed, auditable storage.
Upload form:
Upload the lender’s Hard Money Loan Application to signNow. Check fields:
Review detected fields and add missing borrower, property, and lender fields. Assign roles:
Assign borrower, guarantor, broker, and lender roles where required. Send application:
Send the application by email or generate a signing link. Store evidence:
Review the completed PDF, certificate, and audit trail.
Recommended hard money loan setup
Configure the application workflow to protect borrower information and preserve evidence of each signing event.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification with SMS OTP |
| Signature type | Electronic signature with signer intent |
| Audit trail | Capture timestamps, IP addresses, and action history |
| Document retention | Retain loan records under applicable state policy |
| Encryption | TLS 1.2/1.3 in transit and AES-256 at rest |
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
What the audit trail records
A signNow audit trail documents the evidence surrounding each completed Hard Money Loan Application, from signer authentication through export.
Authenticate signer:
Capture timestamps:
Hash document:
Seal evidence:
Attach certificate:
Export history:
Features for hard money loan intake
signNow connects structured borrower intake, signer routing, mobile completion, and audit evidence for property-backed financing workflows.
Structured intake
A reusable application template keeps borrower, property, requested proceeds, valuation, and exit-strategy fields organized before the lender begins underwriting.
Field detection
Auto-detected fields reduce manual placement work, while staff can review and correct fields specific to the lender’s application.
Signer routing
Role-based routing sends borrower, guarantor, broker, and lender fields to the appropriate signer in the required order.
Audit evidence
The completed application remains connected to timestamps, authentication events, and action history for later review.
Mobile access
Mobile apps let borrowers review and sign property-financing documents from supported iOS and Android devices.
Team control
Templates and delegated sending help private-lending teams manage repeated applications without distributing uncontrolled document copies.



Find and fill out the correct private money lender handbook pdf form
airSlate SignNow helps you fill in and sign documents in minutes, error-free. Choose the correct version of the editable PDF form from the list and get started filling it out.
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| *2012 The Investor's Source LLC Hard/Private Money Loan Application [2012-01] 2012 | 4.8 Satisfied (21921 Votes) |
Security for borrower applications
Transit encryption:
Stored encryption:
Security reporting:
Information security:
Electronic signatures:
Protected health data:
Privacy and disclosure pitfalls
Borrower bank statements, tax returns, credit information, and property details may remain visible to recipients who do not need underwriting access. Consumer-facing electronic records require consent disclosures and accessible electronic copies under 15 U.S.C. §7001(c). Shared templates or delegated sending can expose applications to the wrong lender, broker, borrower, or property file. A missing property address, loan amount, or exit strategy can delay underwriting and create conflicting application versions.
Legal standing of the signed application
A completed Hard Money Loan Application can document borrower intent, disclosures, and lender review when the signer consents, intends to sign, can be identified, and the record is retained accurately. ESIGN, 15 U.S.C. ch. 96, and applicable UETA rules support electronic records, but wills, court filings, family-law decrees, and other statutory exceptions remain outside that framework.

Record-keeping practices for loan applications
Preserve the signed application, supporting documents, and audit evidence as one controlled loan record.
Retain the complete loan file
Export the audit trail
Limit borrower-data access
Archive signed records securely
Retention schedule for loan records
Hard Money Loan Application records do not have one universal federal retention period; apply the controlling transaction, tax, state, and legal-hold rules.
3 years from filing
6 years under applicable rule
3 or 6 years for tax records
Loan-term period
Indefinite legal hold
Platform requirements for signing
Complete the Hard Money Loan Application in a current Chrome, Firefox, Safari, or Edge browser on Windows or macOS. signNow also provides mobile apps for iOS and Android, allowing borrowers to review, capture supporting documents, and sign from a supported mobile device. Use TLS-secured connections for the signing session.
Browsers Chrome, Firefox, Safari, Edge Operating systems Windows, macOS, iOS, Android Mobile signing signNow mobile apps with camera capture
Lenders should manage mobile access through approved devices and account permissions. Before deployment, test camera-based document capture, signer authentication, delegated sending, and audit-trail export with the actual borrower and property fields. Organizations requiring SSO, full API access, HIPAA, or 21 CFR Part 11 add-ons should confirm the appropriate signNow plan and configuration.
Hard money application use cases
Real-estate finance teams use structured electronic workflows to collect property and borrower information before underwriting and approval.
Martin Properties
Martin Properties uses online document execution for real-estate transactions and illustrates how property-focused teams can move signed paperwork between parties without relying on in-person meetings.
- Real-estate transaction documents
- Mobile and offline work
- Built-in compliance and security
Tim Martin, founder of Martin Properties, describes processing and executing documents online while working on mobile or offline. That workflow is relevant to hard-money intake when borrowers, brokers, and lenders need to review property information away from the office, although each lender must configure the application and retention policy for its own transactions.
Regional private lender
A regional private lender can standardize borrower intake by using one controlled template for property details, requested proceeds, repayment strategy, and supporting records.
- Structured borrower intake
- Role-based signing order
- Audit-trail preservation
The scenario shows how a lender can separate borrower completion from internal review, then preserve the signed application and audit evidence. It does not establish a legal outcome or underwriting decision; state lending rules, disclosure obligations, and the lender’s own approval policy still control the transaction.
Hard Money Loan Application troubleshooting
Resolve field, signer-authentication, plan, and retention questions before relying on the completed application for underwriting or closing.
Upload the original Hard Money Loan Application as a PDF or supported document, then review signNow’s detected fields. Add borrower, lender, guarantor, property, loan amount, and signature fields manually when detection misses or misplaces a field.
The Business plan costs $8 per user per month with annual billing and includes templates and audit trails. Business Premium costs $15 per user per month annually and adds bulk send, kiosk mode, request payments, and quick invite links.
signNow supports legally binding electronic signatures under ESIGN and UETA. Confirm borrower consent, signer intent, attribution, and record retention. For consumer-facing records, provide the disclosures and access procedures required by 15 U.S.C. §7001(c).
Use SMS OTP or another configured authentication control when borrower identity requires more evidence than an email link. Advanced signer authentication is listed with Enterprise, while exact configuration depends on the account and workflow.
Business, Business Premium, and Enterprise plans include 100 signature invites per user per year, with overage fees. The Site License costs $1.50 per signature invite and is usage-based for organizations with 1,000 or more documents annually.
Export the completed Hard Money Loan Application together with its certificate and audit trail. Store them under the lender’s retention policy, and apply any state, tax, litigation-hold, or transaction-specific requirements before deletion.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.