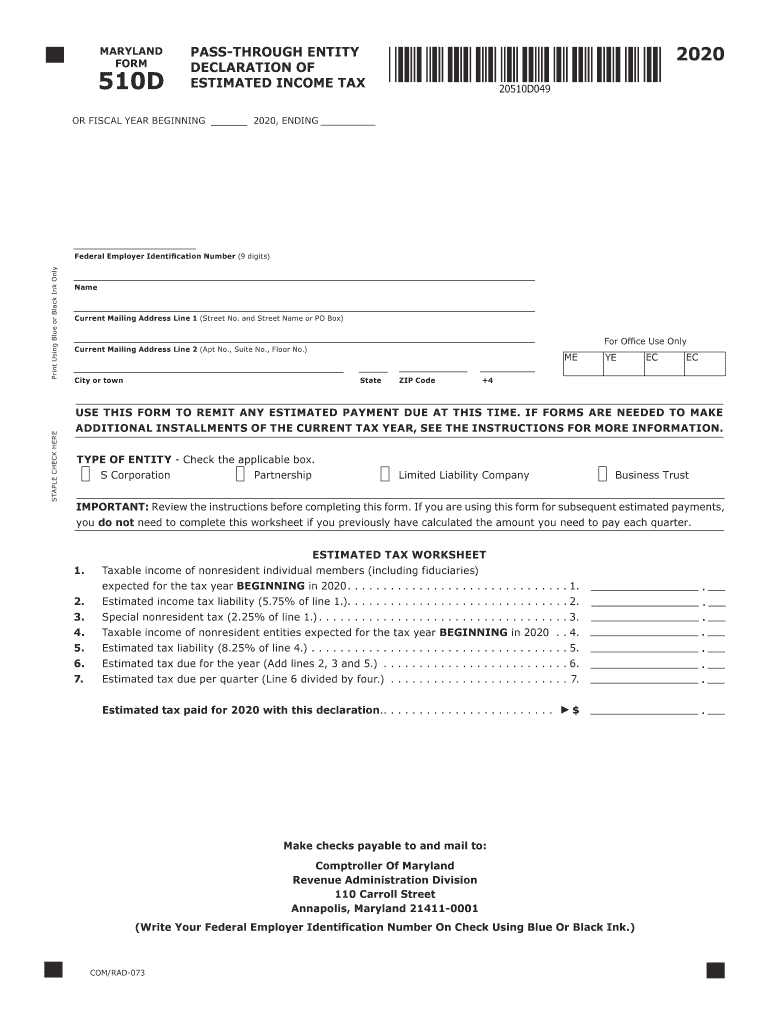
Ty 510D Pte Estimated Income Tax Form
Use a TY 510D PTE ESTIMATED INCOME TAX FORM 2020 template to make your document workflow more streamlined.
What this estimated tax form does
Ty 510D Pte Estimated Income Tax Form is a named document for recording estimated income tax information, but the supplied source does not identify its issuing agency, filing period, or official instructions. Treat the form as a source-controlled tax record: confirm every field against the issuing authority, enter figures exactly as instructed, and retain the completed version with its supporting calculations. signNow can upload the document, detect fillable fields, route it for review and signature, and preserve an audit trail. Electronic-signature enforceability depends on intent, consent, attribution, and record reproducibility under ESIGN and applicable state law.
Who uses this tax form
Tax preparers
Independent tax preparers and small-business owners use this form to document estimated income tax information for a specific filing workflow.
Finance teams
Finance teams can route the completed form for review, signature, storage, and later retrieval without changing its tax content.
Features for this tax workflow
The workflow keeps the Ty 510D Pte form intact while adding controlled field completion, routing, signatures, and evidence for the resulting tax record.
Field preparation
Upload the Ty 510D Pte document and place fields for the preparer, reviewer, signer, date, and required tax information without rebuilding the form.
Role routing
Route the form to named participants in sequence, keeping review and signature responsibilities separate when the tax workflow requires approval.
Electronic signing
Collect an electronic signature with signer intent, attribution, and a reproducible completed record for the transaction file.
Audit evidence
Preserve the final Ty 510D Pte document with timestamps, participant actions, and completion evidence in an audit trail.
Record retrieval
Retrieve the signed document and audit trail together when accounting or compliance personnel need to review the filing record.
Mobile access
Use signNow mobile apps or web access when authorized personnel must review or sign the form away from a desk.
Complete the form in signNow
Use this sequence to prepare, route, sign, and preserve the Ty 510D Pte Estimated Income Tax Form without altering its required tax information.
Upload form:
Upload the original Ty 510D Pte document to signNow. Check fields:
Review detected fields and add missing tax-specific fields. Assign roles:
Assign the preparer, reviewer, and signer roles. Send securely:
Send the completed form for review and signature. Store records:
Download the signed record and audit trail.



 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Platform requirements for this form
Access the Ty 510D Pte workflow through Chrome or Edge on Windows or macOS, or use signNow mobile apps on iOS and Android with an internet connection.
Desktop browsers Chrome and Edge Desktop systems Windows and macOS Mobile apps iOS and Android
Organizations should manage supported browsers, mobile permissions, and document access centrally. Use HTTPS connections, restrict downloaded tax records, and configure account permissions so only authorized preparers, reviewers, and signers can access the Ty 510D Pte form or its audit trail.
Issues to check before signing
The form’s issuing authority and filing instructions are not identified in the supplied source, so users must verify the controlling instructions before entering tax figures. Estimated income, payment, or withholding figures can be copied incorrectly when supporting worksheets are not retained with the completed Ty 510D Pte form. A signer may receive the document before a reviewer confirms taxpayer identity, required fields, and the applicable reporting period. A signed PDF without its completion certificate or audit trail may provide weaker evidence of signer attribution and transaction history.
Find and fill out the correct ty 2020 510d pte estimated income tax form
airSlate SignNow helps you fill in and sign documents in minutes, error-free. Choose the correct version of the editable PDF form from the list and get started filling it out.
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| MD Form 510D 2024 | 4.7 Satisfied (146 Votes) | |
| MD Form 510D 2023 | 4.8 Satisfied (503 Votes) | |
| MD Form 510D 2022 | 4.8 Satisfied (1624 Votes) | |
| MD Form 510D 2021 | 4.8 Satisfied (1624 Votes) | |
| MD Form 510D 2020 | 4.8 Satisfied (83 Votes) |
What the audit trail records
The signNow audit trail links the Ty 510D Pte document to signer actions, timestamps, completion evidence, and a retrievable record of the transaction.
Authenticate signer:
Capture timestamps:
Preserve document:
Seal completion:
Log actions:
Export evidence:
Security controls for signed records
Transport encryption:
Stored encryption:
Security certification:
Management certification:
Health-data controls:
Electronic signatures:
Retention periods for tax records
Retention depends on the filing context and any applicable state or industry rule. Apply the longer period when requirements overlap.
Three years after filing
Six years for understatement
Indefinite for fraud
Indefinite without return
Longer applicable period
Best practices for retaining this form
A defensible Ty 510D Pte record combines the signed document, supporting figures, signer evidence, and the rule used to determine retention.
Retain the complete tax record
Export and review the audit trail
Limit access to taxpayer information
Document the controlling instructions
Documents requiring separate rules
Verify authority
Notarization
Wills excluded
Real-estate deeds
Questions about completing this form
These answers address document preparation, signatures, plan limits, privacy, and retention without inventing filing instructions absent from the supplied form source.
The supplied source does not identify the issuing agency or official filing instructions. Confirm the form’s authority and tax period before creating a signNow template; signNow can route and preserve the document, but it does not determine whether the form is valid for filing.
Upload the original file again and inspect the detected fields before sending. signNow supports templates and field placement, while the Business plan includes legally binding eSignatures and audit trails; users remain responsible for correcting tax-specific fields.
Use signNow’s audit trail and completion record to document intent, attribution, timestamps, and the final file. ESIGN and UETA support electronic signatures when their legal requirements are met; they do not replace tax-agency instructions or filing requirements.
The signNow Business plan is listed at $8 per user per month with annual billing and includes 100 signature invites per user per year. Confirm current plan terms and overage treatment before routing high-volume tax workflows.
If the Ty 510D Pte record contains protected health information, signNow identifies HIPAA compliance as requiring a BAA. Do not place such information in the workflow until the organization has completed its required contractual and privacy review.
Export the signed document and audit trail together, then apply the retention rule for the underlying tax record. IRC §6501(a) generally provides three years, six years for a 25% understatement, and longer periods in specified cases.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.