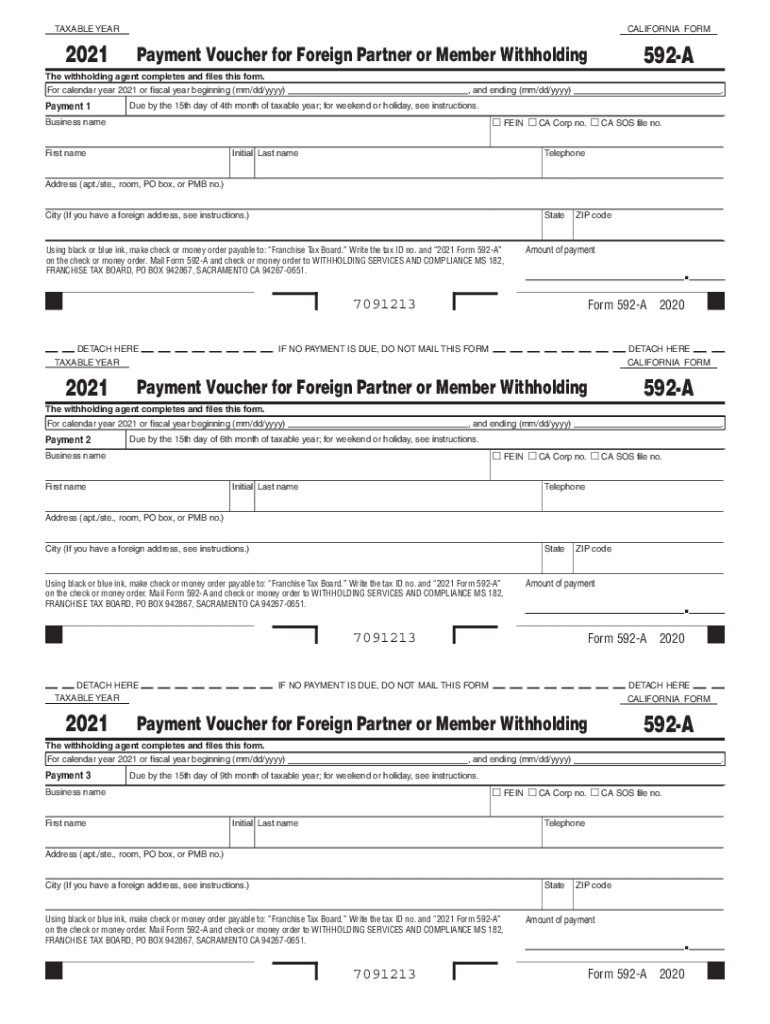
Form 592 A Payment Voucher For Foreign Partner Or Member (2021)
Use a Form 592 A Payment Voucher For Foreign Partner Or Member 2021 template to make your document workflow more streamlined.
What Form 592 A payment voucher does
Form 592 A Payment Voucher For Foreign Partner Or Member (2021) is a California payment voucher used with Form 592 to remit withholding for foreign partners or members. The withholding agent identifies the business, recipient, tax year, and payment amount, then submits the voucher and payment according to California Franchise Tax Board instructions. It is not a federal IRS form and does not replace the related withholding statement. Before signing or transmitting it, confirm the recipient classification, withholding calculation, account information, and current filing instructions with the California Franchise Tax Board.
Who works with this California voucher
A California partnership’s tax administrator can prepare the voucher after reconciling withholding for a foreign partner, route it to an authorized signer, and preserve the signed copy with the related Form 592 records. The workflow reduces manual routing without changing the payer’s tax responsibilities or California filing obligations. A professional-services accounting team handling multiple partnerships can reuse a controlled Form 592 A template, assign recipient-specific fields, and document approval before payment. signNow’s audit trail provides signing evidence, while the team still verifies every amount against California Franchise Tax Board instructions.
How to complete this voucher online
The signNow workflow organizes preparation and authorization of Form 592 A without replacing California Franchise Tax Board payment or filing instructions.
Upload voucher: Upload the 2021 California voucher PDF to signNow. Complete fields: Review auto-detected fields and complete voucher-specific details. Send for signature: Add the authorized signer and send the document. Store evidence: Download the signed voucher with its audit trail.
Quick steps for this voucher
Prepare the California voucher in signNow, verify its tax details, obtain authorization, and preserve the signed record with its audit evidence.
Upload document:
Upload the Form 592 A PDF. Review fields:
Check detected fields against the source. Assign signer:
Add the authorized California signer. Complete workflow:
Send, sign, and download evidence.
Features that support voucher completion
Form 592 A workflows benefit from controlled field review, authorized signing, and evidence preservation while California tax responsibilities remain with the withholding agent.
Field detection
Upload the 2021 voucher and use detected fields as a starting point, while checking every California-specific entry against the source document and related withholding records.
Signer routing
Route the voucher to an authorized representative without printing or manually circulating multiple copies through the partnership’s accounting workflow.
Audit trail
Capture signer intent, timestamps, access events, and document history so the partnership can explain how the completed voucher was authorized.
Record retention
Keep the signed voucher and completion evidence together with Form 592-related records for later reconciliation, review, or response to an inquiry.
Reusable template
Use templates for recurring California partnership withholding workflows while requiring staff to verify each foreign partner or member’s details before sending.
Mobile access
Work from desktop or mobile apps when authorized staff need to review or sign the voucher away from the office.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Recommended voucher workflow settings
Use controlled signing and recordkeeping practices when preparing Form 592 A alongside its related California withholding records.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification with SMS OTP |
| Signature type | Intent-based electronic signature |
| Audit trail | Capture timestamps, access, and actions |
| Document retention | Keep records under applicable California requirements |
| Encryption | Use TLS 1.2/1.3 and AES-256 |
What the voucher audit trail records
The audit trail supplements Form 592 A by documenting how the authorized signer accessed, reviewed, and completed the voucher.
Authenticate signer:
Timestamp actions:
Hash document:
Seal record:
Complete signature:
Export evidence:
Find and fill out the correct 2021 form 592 a payment voucher for foreign partner or member
airSlate SignNow helps you fill in and sign documents in minutes, error-free. Choose the correct version of the editable PDF form from the list and get started filling it out.
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| CA FTB 592-A 2024 | 4.7 Satisfied (168 Votes) | |
| CA FTB 592-A 2023 | 4.8 Satisfied (2103 Votes) | |
| CA FTB 592-A 2022 | 4.8 Satisfied (938 Votes) | |
| CA FTB 592-A 2021 | 4.8 Satisfied (1352 Votes) | |
| CA FTB 592-A 2020 | 4.8 Satisfied (1647 Votes) | |
| CA FTB 592-A 2019 | 4.8 Satisfied (3266 Votes) |
Security controls for signed vouchers
Transport encryption:
Stored encryption:
SOC 2 Type II:
ISO 27001:
ESIGN/UETA:
Signer authentication:



Avoidable Form 592 A filing problems
Matching the voucher to Form 592 and the correct foreign partner or member requires consistent names, tax identifiers, and payment amounts. Entering the wrong tax year or account information can delay California withholding payment processing and complicate reconciliation. A signed voucher does not validate the underlying withholding calculation, so the payer must review California instructions separately. Electronic signing may document authorization, but the completed voucher still must follow the California Franchise Tax Board’s submission process.
Form 592 A processing sequence
Move the voucher from preparation through authorized signing and record retention without treating signature completion as tax filing confirmation.
Prepare the voucher
Deliver to signer
Signer review
Archive records
Best practices for retaining voucher records
Accurate reconciliation, complete audit evidence, controlled access, and authority-based retention make the signed voucher easier to review later.
Reconcile the voucher before signature
Export the audit trail with the voucher
Set retention using the applicable rule
Restrict access to taxpayer information
Key performance indicators that demonstrate SignNow's proven track record.
Troubleshooting Form 592 A workflows
These answers address signing, field review, submission, authentication, and recordkeeping issues that arise when preparing this California withholding voucher.
Upload the original 2021 PDF again and inspect signNow’s detected fields before sending. Auto-detection is a starting point, not a tax validation step. Confirm every payer, recipient, tax-year, and amount entry against California Franchise Tax Board instructions and the related Form 592 records.
A Business plan includes templates, audit trails, and legally binding eSignatures. If the workflow requires bulk sending, Business Premium adds that capability. Select the plan based on document volume and routing needs, not on whether the voucher itself is a California tax form.
An electronic signature can evidence intent and authorization under ESIGN and UETA, but it does not itself submit payment or satisfy every California filing instruction. Follow the California Franchise Tax Board’s current delivery and payment requirements after signing.
Use signer verification, SMS OTP, or stronger authentication where the partnership’s controls require it. Record the signer’s identity and retain the audit trail with the voucher. Authentication supports attribution but does not confirm that the withholding calculation is correct.
Download both the completed voucher and its audit trail after signing. Store them with the related Form 592 records in a controlled location, using retention rules that apply to the partnership’s tax records and California obligations.
If a foreign partner’s details change, void or correct the signing workflow before relying on the record. Do not overwrite the completed document silently; preserve the audit history and reconcile the replacement with the related withholding documentation.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.