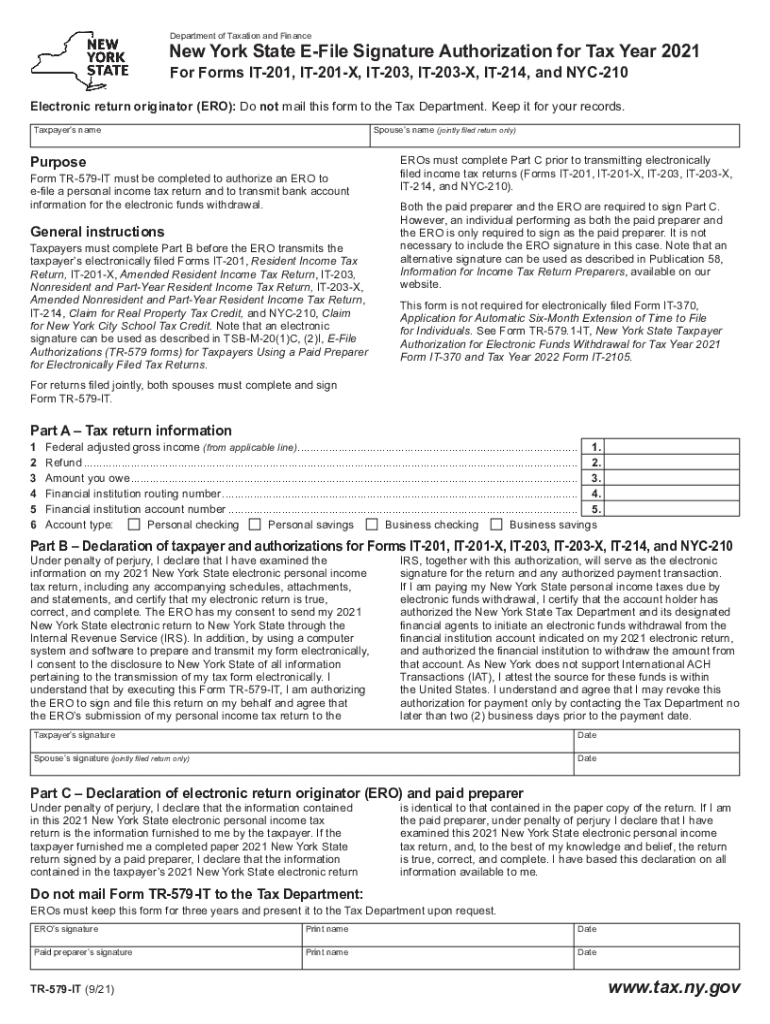
Www Tax Ny Govpitefilenew York State Taxpayer Authorization For Tax Ny Gov
Use a Www tax ny govpitefileNew York State Taxpayer Authorization For Tax ny gov 2021 template to make your document workflow more streamlined.
What this New York authorization does
The New York State taxpayer authorization is a form used to permit a designated representative to discuss or handle specified state tax matters for a taxpayer. The filer identifies the taxpayer, names the representative, defines the tax periods or matters covered, and provides authorization details. After the required parties sign, the completed record can be retained for the related New York tax matter. Electronic signing may be supported when the agency and transaction permit it; confirm New York State Department of Taxation and Finance submission requirements before filing.
Who uses this authorization form
The form serves taxpayers and representatives who need documented authority for a defined New York tax matter.
New York tax professionals can use the authorization to collect taxpayer approvals and document representative access for defined state tax matters. Small businesses can prepare a signed authorization for an accountant or tax representative without coordinating paper copies and manual signature follow-up. Enterprise tax departments can standardize authorization routing, preserve audit trails, and manage access to completed taxpayer records across internal teams.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
How the New York authorization works
Complete the taxpayer authorization in signNow by preparing the document, assigning signers, capturing consent, and preserving the signed record.
Upload the form: Upload the New York State taxpayer authorization document to signNow. Check fields: Review detected fields and add the taxpayer and representative signers. Send for signing: Send the authorization for electronic signatures in the required order. Archive records: Store the completed authorization with its audit trail and signed copy.
Steps to prepare the authorization
Use this short checklist to prepare the New York taxpayer authorization before sending it for signature.
Upload document:
Upload the New York authorization document. Review details:
Review fields for taxpayer and representative details. Assign signers:
Assign required signers and signing order. Finish and store:
Send, complete, and retain the signed record.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
What the authorization audit trail records
A signNow audit trail connects the New York taxpayer authorization to signer identity, document activity, completion timing, and the preserved evidence record.
Authenticate signer:
Capture timestamp:
Link document:
Seal history:
Track events:
Export evidence:
Find and fill out the correct wwwtaxnygovpitefilenew york state taxpayer authorization for taxnygov
airSlate SignNow helps you fill in and sign documents in minutes, error-free. Choose the correct version of the editable PDF form from the list and get started filling it out.
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| NY DTF TR-579-IT 2023 | 4.8 Satisfied (356 Votes) | |
| NY DTF TR-579-IT 2022 | 4.8 Satisfied (1420 Votes) | |
| NY DTF TR-579-IT 2021 | 4.8 Satisfied (1691 Votes) | |
| NY DTF TR-579-IT 2020 | 4.8 Satisfied (993 Votes) | |
| NY DTF TR-579-IT 2018 | 4.8 Satisfied (1006 Votes) | |
| NY DTF TR-579-IT 2016 | 4.7 Satisfied (309 Votes) |
Problems that can delay authorization
Entering a representative’s name or contact details incorrectly can prevent the New York tax authorization from identifying the intended person. Leaving tax periods, tax types, or authorization limits blank can create uncertainty about what the representative may access. Using an outdated agency version may cause the completed authorization to require correction before New York tax processing. Sending the document without confirming every required signature can leave the taxpayer authorization incomplete.
Recordkeeping practices for authorization forms
Accurate scope, controlled access, and a preserved audit history help connect the signed authorization to the New York tax matter it covers.
Verify every authorization field
Preserve the audit trail
Set a documented retention rule
Archive the signed record securely
How long to retain authorization records
Retention depends on the underlying New York tax matter and applicable federal rule; preserve the signed authorization and supporting evidence consistently.
Three years: tax records
Six years: major understatement
Indefinite: fraud or no return
State period: verify matter
Scope period: case records
Security for taxpayer authorizations
Data at rest:
Data in transit:
Security reporting:
Information security:
Protected information:
Electronic signatures:
Questions about signing and filing
These answers address the New York taxpayer authorization workflow, electronic-signature rules, agency acceptance, and signNow configuration issues.
signNow can route the authorization for electronic signatures, but New York State Department of Taxation and Finance submission rules may require a particular form version or delivery method. Confirm the agency’s current instructions before treating a completed electronic record as filed.
A missing taxpayer or representative signature leaves the authorization incomplete. In signNow, review the recipient roles and signing order, then send a reminder or correct the workflow before exporting the final signed document.
The Business plan includes templates, audit trails, and legally binding eSignatures at $8/user/month when billed annually. It does not include every advanced authentication or integration feature, so review plan requirements before configuring the authorization workflow.
New York uses its Electronic Signatures and Records Act, New York State Technology Law §§301–309, rather than UETA. ESIGN generally supports interstate electronic records, but agency-specific acceptance and submission rules still control this tax authorization.
For consumer-facing electronic records, ESIGN requires disclosure of the right to receive paper records, access to the electronic format, and a method to withdraw consent under 15 U.S.C. §7001(c). Apply those requirements when the taxpayer is a consumer.
If a signer cannot open the document, check the email address, signing link, browser, and mobile access. signNow supports web and mobile signing; resend the invitation after correcting recipient details and retain the resulting activity history.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.