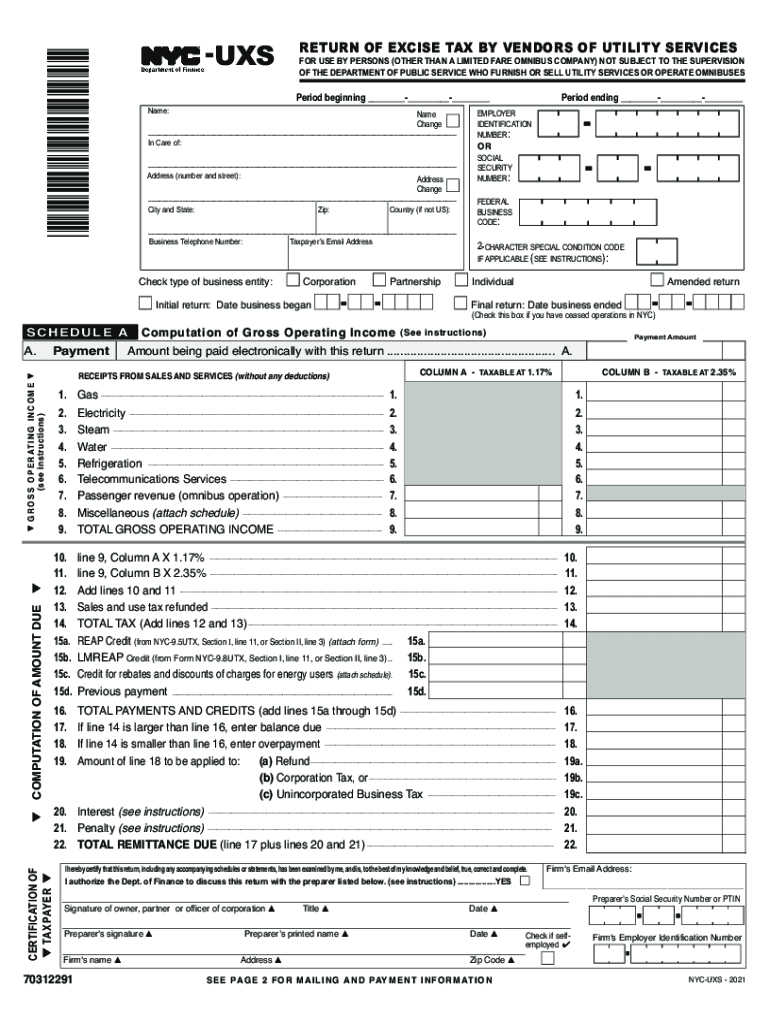
Tm Uxs Return Of Excise Tax By Vendors Of
Use a Fillable Online TM UXS RETURN OF EXCISE TAX BY VENDORS OF 2021 template to make your document workflow more streamlined.
What this vendor excise tax return means
Tm Uxs Return Of Excise Tax By Vendors Of is a named vendor excise-tax return, but the supplied title does not identify an IRS form number, issuing agency, tax, filing period, or required fields. Do not infer those details from the name alone. A filer should confirm the authoritative instructions and applicable state or federal authority before completing it. signNow can upload the confirmed document, detect fillable fields, route it for authorized signatures, and preserve the completed copy and audit trail. Tax filing deadlines and payment obligations remain governed by the issuing authority.
Features for handling this return
signNow provides a controlled document workflow while the issuing authority’s instructions determine the return’s tax content and filing requirements.
Document preparation
Upload the confirmed vendor return and compare the detected fields with the official source before sending it for completion.
Role assignment
Assign vendor, reviewer, and signer fields to named recipients so responsibility for each entry is clear.
Signing order
Collect signatures through an ordered workflow when the issuing authority or internal policy requires review before execution.
Audit trail
Preserve the executed return and completion record together for internal review and later retrieval.
Controlled templates
Use templates only after confirming that the source form, tax period, and instructions remain current.
System connections
Connect approved storage or business systems after confirming that the integration matches the organization’s record policy.
How to prepare and sign this return
Use the issuing authority’s instructions first, then use signNow to prepare, route, sign, and preserve the confirmed return.
Confirm authority:
Confirm the issuing authority and current instructions before entering vendor or tax information. Upload document:
Upload the approved return to signNow and review detected fields against the source document. Assign fields:
Assign each required field to the authorized vendor representative or reviewer. Complete record:
Send the completed return for signature and retain the signed copy with its audit trail.
Recommended workflow setup
Configure the signing workflow around the confirmed return, authorized personnel, and the issuing authority’s record requirements.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification with SMS OTP |
| Signature type | Electronic signature with intent record |
| Audit trail | Enabled with completion certificate |
| Document retention | Apply the authority’s confirmed schedule |
| Encryption | TLS 1.2/1.3 and AES-256 protection |
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
What the audit trail records
The audit trail documents the signing event; it does not replace the issuing authority’s tax records or filing confirmation.
Authenticate signer:
Capture timestamps:
Record document hash:
Seal record:
Track actions:
Export evidence:
Challenges when preparing this return
The title does not identify an IRS form number or agency, so using the wrong instructions could produce an incomplete or misdirected filing. Vendor, purchaser, and tax-period details must match supporting invoices and records; inconsistent entries can delay review or require correction. A signature workflow does not determine the tax due, filing deadline, or payment method established by the issuing authority. Uploading an unofficial template may omit schedules, certification language, or fields required for the applicable excise-tax transaction.
Find and fill out the correct fillable online tm uxs return of excise tax by vendors of
airSlate SignNow helps you fill in and sign documents in minutes, error-free. Choose the correct version of the editable PDF form from the list and get started filling it out.
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| NY DoF NYC-UXS 2022 | 4.8 Satisfied (1225 Votes) | |
| NY DoF NYC-UXS 2021 | 4.8 Satisfied (1287 Votes) | |
| NY DoF NYC-UXS 2020 | 4.8 Satisfied (2628 Votes) | |
| NY DoF NYC-UXS 2019 | 4.8 Satisfied (857 Votes) | |
| NY DoF NYC-UXS 2018 | 4.8 Satisfied (958 Votes) | |
| NY DoF NYC-UXS 2017 | 4.7 Satisfied (167 Votes) |
Legal standing and business value
For a U.S. business transaction, an electronic signature may carry legal effect under ESIGN, 15 U.S.C. ch. 96, and applicable UETA or New York ESRA rules when intent, consent, attribution, and record retention are established. Those laws do not identify this return’s tax obligation or guarantee agency acceptance; confirm filing rules with the issuing authority.

Risks requiring verification
Filing destination
Incomplete return
Agency acceptance
Weak evidence
Retention periods to verify
The form title does not establish a definitive retention period. Apply the rule that governs the confirmed tax or state filing.
Three years from filing
Six years for major understatement
Indefinite for fraud
State period may be longer
Authority-specific schedule
Record-keeping practices for this return
Accurate retention begins with confirming which authority issued this return and what record set supports its entries.
Confirm the authority before preparation
Reconcile fields against source instructions
Export the signed record and audit trail
Apply the governing retention rule



Questions about this return workflow
Because the form title does not identify an agency or form number, resolve document identity and filing rules before relying on an electronic workflow.
Check that the uploaded file is the approved return and that its fields match the issuing authority’s current instructions. signNow Business supports document uploads, templates, and audit trails, but it cannot validate tax form identity.
Review auto-detected fields against the source document, then add or reassign missing fields before sending. Field detection assists preparation; the vendor remains responsible for accurate tax, vendor, and transaction information.
Use the authorized signer’s verified email and add SMS OTP when policy requires stronger authentication. signNow records signing events, while ESIGN and UETA focus on intent, consent, attribution, and reproducible records.
The Business plan is listed at $8 per user per month with annual billing and includes audit trails. It does not establish the return’s deadline, tax amount, or agency acceptance.
SignNow’s ESIGN and UETA compliance supports electronic signing workflows, but tax agencies may impose separate submission rules. Confirm whether the completed return must be uploaded, mailed, or filed through another channel.
Retain the executed document, completion record, source instructions, and supporting records under the applicable authority’s schedule. IRC §6501(a) provides federal assessment periods, but state or agency rules may differ.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.