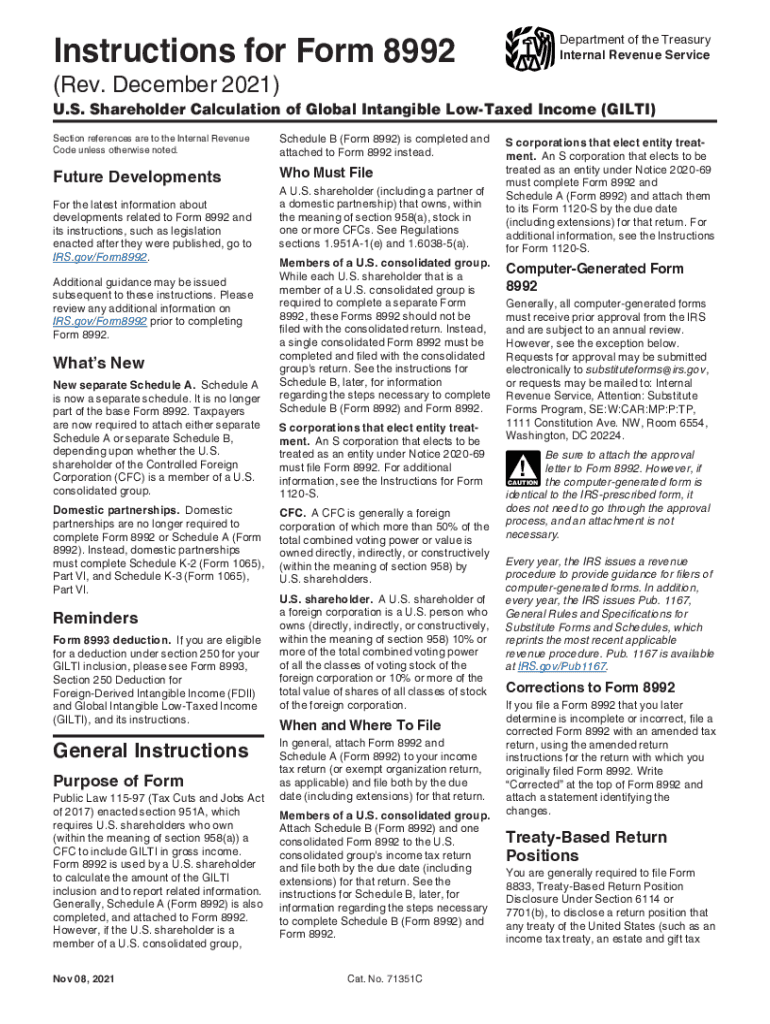
Rev Rul 2 Internal Revenue Service
Use a Rev Rul 2 Internal Revenue Service 2021 template to make your document workflow more streamlined.
Rev. Rul. 2 overview
Rev. Rul. 2 is an Internal Revenue Service revenue ruling that explains how federal tax law applies to the specific facts and legal question addressed in that ruling. It is administrative guidance, not a substitute for the Internal Revenue Code, Treasury regulations, or professional advice. A reader should identify the ruling’s stated transaction, tax provision, effective date, and conclusion before relying on it. For electronic records connected with a related business transaction, ESIGN and UETA may support electronic signatures when intent, consent, attribution, and record retention requirements are satisfied.
Who works with Rev. Rul. 2 records
Rev. Rul. 2 is most useful when a tax conclusion must be connected to documented facts, approvals, and retained transaction evidence.
Tax practitioners use Rev. Rul. 2 records to document how a client transaction was compared with the ruling’s stated facts and cited authority before filing or advising the client. Financial-services teams use signed ruling records to preserve approvals, transaction assumptions, and reviewer comments when tax treatment affects account or payment documentation. Enterprise tax departments use signNow templates, assigned fields, and audit trails to standardize internal review while retaining the source ruling with each transaction file.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
How Rev. Rul. 2 works
Rev. Rul. 2 works by connecting stated facts, applicable tax law, and the IRS conclusion in a published administrative ruling.
Identify ruling: The ruling states the IRS conclusion. Review facts: Read the stated facts and legal reasoning. Match circumstances: Compare those facts with your transaction. Record application: Document the conclusion and supporting records.
Complete Rev. Rul. 2 online
Use this sequence to prepare the Rev. Rul. 2 record, obtain signatures, and preserve evidence of the completed transaction.
Upload document:
Upload the Rev. Rul. 2 document. Check fields:
Review detected fields and add missing fields. Send for signing:
Assign signers and send the document. Store records:
Download the signed copy and audit trail.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Risks of misapplying Rev. Rul. 2
Interpretation errors
Authority gap
Record deficiency
Application uncertainty
Rev. Rul. 2 processing timeline
Rev. Rul. 2 has no filing deadline established by the supplied authority; processing depends on document preparation and signer availability.
Prepare document
Deliver to signers
Signer turnaround
Complete and archive
Find and fill out the correct rev rul 2021 2 internal revenue service
airSlate SignNow helps you fill in and sign documents in minutes, error-free. Choose the correct version of the editable PDF form from the list and get started filling it out.
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| IRS Instructions 8992 2024 | 4.6 Satisfied (38 Votes) | |
| IRS Instructions 8992 2022 | 4.8 Satisfied (199 Votes) | |
| IRS Instructions 8992 2021 | 4.8 Satisfied (211 Votes) |
Rev. Rul. 2 record retention
Retention depends on the tax record and limitation period involved. Apply the relevant IRS rule to the underlying transaction, not merely to the signature event.
Three years tax records
Six years understatement
Indefinite fraud records
State-specific retention period
Permanent authority file
Audit trail for Rev. Rul. 2
A signNow audit trail records the signing events that help connect the completed Rev. Rul. 2 document to its identified signers and source authority.
Authenticate signer:
Capture timestamp:
Protect document:
Track activity:
Export audit trail:
Link authority:
Signer authentication for Rev. Rul. 2
Two-factor authentication:
PKI certificates:
X.509 signatures:
ID verification:
Signer attribution:
Completion certificate:
Rev. Rul. 2 document challenges
The ruling’s conclusion may not apply when the transaction facts differ from the facts expressly addressed by the IRS. A signed copy without the source ruling and cited tax authority may not show why the transaction received its documented treatment. Taxpayer identification information in an uploaded record can be exposed when recipients, permissions, or download access are configured incorrectly. Electronic consent requirements may apply when records are provided to consumers, including disclosure of paper-record rights under 15 U.S.C. §7001(c).
Rev. Rul. 2 troubleshooting
Resolve document, authority, consent, and retention questions before relying on a signed Rev. Rul. 2 record.
Use signNow’s document editor to upload the Rev. Rul. 2 file, place required signature and date fields, and assign each field to the correct signer. Business includes templates and audit trails; verify the underlying ruling before sending.
A signNow signature does not validate the tax interpretation itself. Confirm the ruling’s facts, cited Internal Revenue Code provisions, and effective date against IRS source material, then retain the completed document and audit trail as transaction evidence.
Business includes legally binding eSignatures and audit trails. Business Premium adds bulk send, while Enterprise adds advanced signer authentication. Select the plan based on signer volume and required controls, not on the ruling’s legal authority.
For consumer-facing records, obtain electronic-record consent and preserve access to the signed copy under 15 U.S.C. §7001(c). signNow can capture the signing event, but the sender remains responsible for required disclosures.
Use signNow’s audit trail to preserve signer identity evidence, timestamps, IP information, and document activity. ESIGN and UETA focus on intent, consent, attribution, and reproducible records; an audit trail supports those elements but does not replace tax substantiation.
Do not use an electronic signature to bypass a statutory exception. ESIGN excludes wills, codicils, testamentary trusts, court orders, and certain other records. Confirm whether the related transaction requires notarization, witnesses, or paper filing under applicable state law.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.