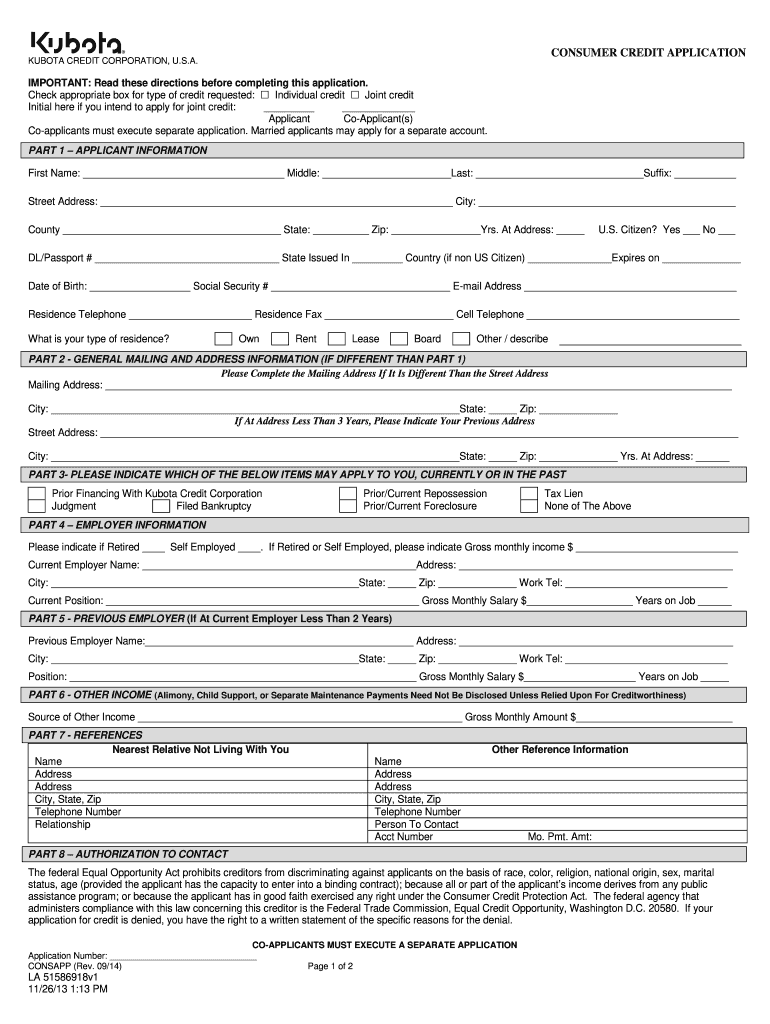
Consumer Credit Application
Create a custom Consumer Credit Application Pdf 2014 that meets your industry’s specifications.
What a consumer credit application does
A Consumer Credit Application is a document a person completes to request credit from a lender, creditor, or financing provider. It records identifying information, requested credit terms, income, employment, housing, and other facts used to evaluate the request. The applicant reviews the disclosures, provides any required supporting information, and signs the completed application. With signNow, a lender can upload the application, detect fillable fields, send it to the applicant, collect an electronic signature, and store the completed record with an audit trail. Approval decisions remain with the creditor.
Who uses this credit application
Consumer lenders
Banks, credit unions, auto finance companies, and consumer lenders use the application to collect borrower information before underwriting. Required fields should match the creditor’s policy and applicable disclosure obligations.
Financing businesses
Retailers and service providers offering financing use the application to gather applicant details, requested terms, and consent before reviewing a credit request.
How the application workflow works
The signNow workflow moves the Consumer Credit Application from a lender-controlled template to a signed, retrievable credit record.
Upload application: Upload the lender’s Consumer Credit Application template to signNow. Detect fields: Auto-detect fillable fields and confirm applicant information fields. Send to applicant: Send the application to the borrower for review and signature. Store evidence: Store the signed application with its audit trail and completion certificate.
How the audit trail protects evidence
The audit trail connects the Consumer Credit Application to signer identity, timing, document integrity, and retrievable completion evidence.
Authenticate signer:
Capture timestamp:
Hash document:
Seal record:
Preserve history:
Export evidence:
Platform requirements for applicants
Applicants can complete the Consumer Credit Application in supported desktop browsers or through signNow mobile apps for iOS and Android. The workflow requires an internet connection for delivery and electronic record access.
Browsers Chrome, Firefox, Safari, Edge Desktop systems Windows and macOS Mobile apps iOS and Android signNow apps
Lenders should test field placement, identity checks, and document access on managed Windows, macOS, iOS, and Android devices before sending applications at scale. Device controls and access permissions remain the lender’s responsibility.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Choose the right signing method
- Use the web app when lending staff prepare, route, and monitor Consumer Credit Applications from a desktop workflow with centralized document control.
- Use the mobile app when applicants or loan staff need to review and sign a Consumer Credit Application from an iOS or Android device.
- Use kiosk mode when a branch employee supervises completion on a shared device without transferring control between separate email accounts.
- Use a shareable signing link when applicants need access through a controlled web link rather than an individual email invitation.
Recommended application workflow setup
Configure the Consumer Credit Application around verified access, intentional signing, audit evidence, controlled retention, and encrypted records.
| Setting | Recommendation |
|---|---|
| Authentication and provisioning | Use verified email with role-based user access |
| Signature type | Use an electronic signature with clear intent |
| Audit trail | Retain timestamps, signer actions, and IP details |
| Document retention | Follow lender policy and applicable state law |
| Encryption | Use TLS 1.2 or 1.3 and AES-256 |
Find and fill out the correct consumer credit application 2014 2019 form
airSlate SignNow helps you fill in and sign documents in minutes, error-free. Choose the correct version of the editable PDF form from the list and get started filling it out.
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| Kubota Consumer Credit Application 2014 | 4.8 Satisfied (8687 Votes) | |
| Kubota Consumer Credit Application 2012 | 4.7 Satisfied (196 Votes) | |
| Kubota Consumer Credit Application 2008 | 4.8 Satisfied (95 Votes) |
Security for credit applications
Data in transit:
Data at rest:
Control assurance:
Security management:
Electronic signatures:
Protected health data:
Privacy and disclosure pitfalls
Collecting Social Security numbers and income details in unnecessary copies increases exposure of sensitive borrower information. Failing to provide the required ESIGN consumer disclosure can undermine consent to electronic records under 15 U.S.C. §7001(c). Leaving a shared signing link open can allow an unintended person to access the Consumer Credit Application. Granting every team member edit access can obscure who changed applicant data before signature.
Legal standing for electronic applications
A Consumer Credit Application can support an electronic lending record when the applicant intends to sign, consents to electronic records, can access and reproduce the document, and the creditor preserves evidence linking the signature to the applicant. ESIGN, 15 U.S.C. ch. 96, and applicable state law, including UETA, generally recognize qualifying electronic signatures; exclusions include wills, certain court orders, and family law decrees.

Retain credit application records carefully
Retention depends on the application’s purpose, jurisdiction, and related records; establish the schedule before collecting signatures.
Set the retention period
Export the audit evidence
Secure borrower records
Apply legal holds
Risks of an incomplete application
Consent dispute
Underwriting error
Disclosure challenge
Evidence weakness
Pricing and plan comparison
signNow pricing is verified from its annual billing information; competitor prices and feature details are marked when unavailable in the supplied source.
| Features | signNow | DocuSign | Adobe Sign | PandaDoc | Dropbox Sign |
|---|---|---|---|---|---|
| Starting annual price | $8/user/month | Not verified | Not verified | Not verified | Not verified |
| Free trial availability | 7 days, no card | Not verified | Not verified | Not verified | Not verified |
| Bulk send availability | Business Premium | Not verified | Not verified | Not verified | Not verified |
| Audit trail availability | Business plan | Not verified | Not verified | Not verified | Not verified |
Consumer credit application troubleshooting
Resolve the issue by checking the document fields, signer identity, electronic consent, plan limits, and record controls in that order.
The Business plan includes templates and audit trails for Consumer Credit Applications. If the workflow requires bulk sending to many applicants, Business Premium adds bulk send at $15 per user per month when billed annually.
A lender collecting a Consumer Credit Application electronically should provide the ESIGN consumer disclosure, explain the right to receive paper records, confirm electronic access, and explain withdrawal procedures under 15 U.S.C. §7001(c).
Use signNow’s audit trail and certificate of completion to connect the applicant’s action, timestamp, and final document. Stronger signer authentication is available through Enterprise features and should match the lender’s risk policy.
Business is listed at $8 per user per month with annual billing and includes 100 signature invites per user per year. Additional invites may incur overage fees, so volume should be reviewed before rollout.
If the application contains protected health information, signNow identifies HIPAA compliance as requiring a business associate agreement. The lender must separately determine whether HIPAA applies to its role and transaction.
ESIGN and UETA generally recognize electronic signatures when intent, consent, attribution, and record reproduction are established. They do not remove exclusions for wills, certain court orders, or family law decrees.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.