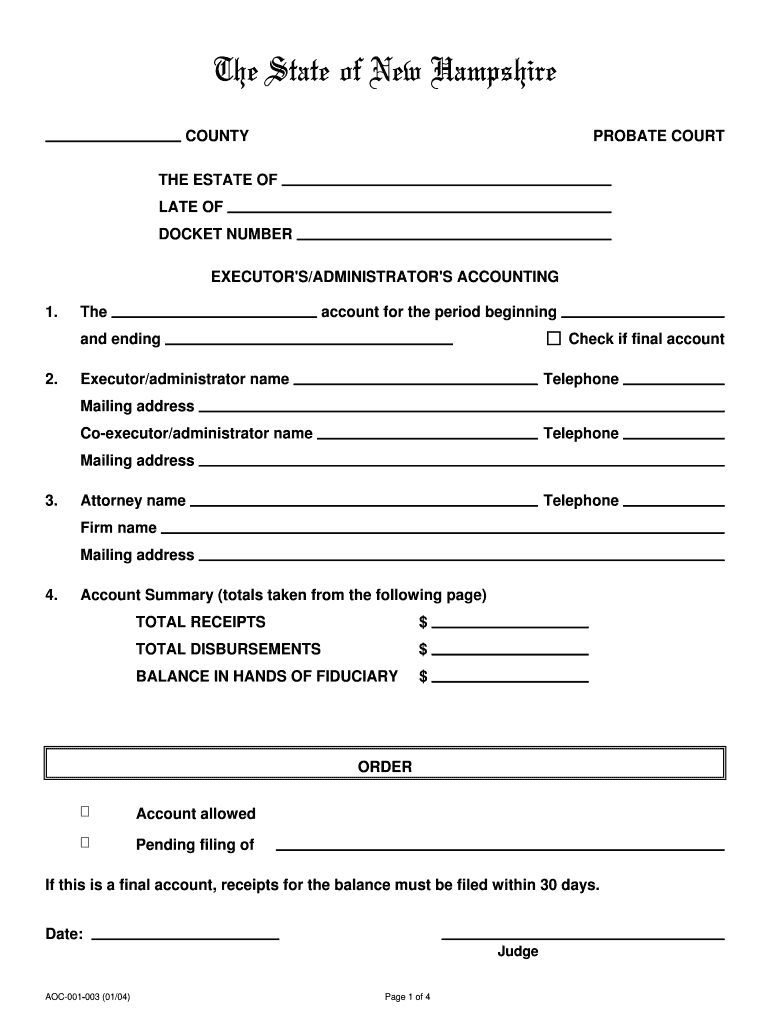
Instructions For Completing Executor'sadministrator's Accounting Form
Use a Instructions For Completing Executor'sAdministrator's Accounting template to make your document workflow more streamlined.
What this executor accounting form records
An Executor's Administrator's Accounting Form is a court or estate-administration record that organizes money received, expenses paid, assets handled, distributions made, and the balance remaining during an executor's administration of an estate. The executor or administrator completes each accounting period with supporting documentation, identifies the estate and fiduciary, and submits or shares the record according to the probate court's instructions and applicable state law. Because requirements differ by jurisdiction, confirm the required schedules, attachments, review period, and signature or notarization rules with the probate court or an estate attorney before filing.
Who uses this estate accounting form
Executor or administrator
The executor or administrator prepares the accounting from estate bank records, receipts, invoices, investment statements, tax documents, and distribution records. The fiduciary must follow the probate court's approved format and deadline, identify transactions clearly, and provide supporting documents when required.
Reviewing parties
Probate counsel, beneficiaries, conservatorship reviewers, and court staff use the accounting to examine receipts, disbursements, proposed distributions, and the ending balance. Their review may identify missing proof, unexplained transactions, or totals requiring correction before approval.
Business types handling estate accounts
The form is most useful where fiduciaries must reconcile estate transactions, obtain review, and preserve an accountable record.
Solo estate practitioners can prepare one estate ledger, route it to the executor, and retain the signed accounting with supporting probate records. Probate law firms can standardize accounting templates, assign review roles, and preserve an audit trail for multiple estates without combining separate fiduciary records. Trust departments and fiduciary offices can coordinate administrators, beneficiaries, and counsel while applying controlled access to transaction schedules and signed approvals.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
Complete the executor accounting form
Use this sequence to prepare, review, sign, and preserve the estate accounting record.
Upload form:
Upload the accounting form and supporting schedules. Check fields:
Review detected fields and add missing entries. Assign roles:
Assign the executor, administrator, or reviewer. Send review:
Send the completed accounting for review. Sign record:
Apply required signatures and dates. Store evidence:
Download the signed form and audit trail.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
How the accounting audit trail works
The audit trail records evidence around the executor's approval without replacing the probate court's filing requirements.
Authenticate signer:
Capture timestamps:
Hash document:
Seal record:
Log activity:
Export trail:
Retention schedule for estate records
Use the court's order and the estate's tax and state-law obligations together; the accounting itself has no single nationwide retention period.
Court-directed period
Tax records: 3 years
Tax records: 6 years
Tax records: indefinitely
State-law extension
Record-keeping practices for estate accounts
Accurate retention and a complete audit trail help demonstrate how estate funds were handled.
Match retention to court instructions
Export the audit trail
Archive sensitive estate records
Reconcile before final approval
Security controls for estate records
Encryption controls:
Independent assurance:
Security certification:
Sensitive data safeguards:
Privacy controls:
Electronic signature framework:
State rules and document exclusions
Court format
Notarization rule
Wills and codicils
Real-estate transfers
Challenges when preparing estate accounts
Receipts and disbursements may be entered in inconsistent categories, making the ending estate balance difficult to reconcile. Missing bank statements, invoices, or distribution receipts can prevent beneficiaries or the court from verifying reported transactions. A fiduciary may submit an accounting before resolving disputed entries, creating avoidable review questions and amendment requests. Sharing the form through uncontrolled email can expose beneficiary information, account details, and other estate records.
Troubleshoot executor accounting workflows
Use these answers to resolve signing, consent, field, plan, and probate-acceptance questions for this accounting record.
Upload the accounting PDF again and verify that each required field is present. signNow's document editor can detect fillable fields, but unusual scans or handwritten schedules may require manual placement before the executor receives the document.
Confirm that the executor's email address is correct, then resend the invitation or provide a controlled signing link. Business includes templates and audit trails; stronger authentication options should be selected when the estate contains sensitive financial information.
A typed or drawn signature can qualify as an electronic signature when intent, consent, attribution, and record retention are established under ESIGN and applicable state law. Confirm whether the probate court requires wet ink, notarization, or a specific local form.
For consumer-facing electronic records, ESIGN requires disclosure of the right to paper records, access capability, and a way to withdraw consent under 15 U.S.C. §7001(c). Obtain appropriate consent before using an electronic accounting workflow with a consumer signer.
Business includes 100 signature invites per user per year when billed annually, with overage fees. Business Premium adds bulk send, while Enterprise adds advanced signer authentication. Select the plan based on actual invite volume and required controls.
signNow is ESIGN and UETA compliant, with audit trails and encrypted data controls. That platform capability does not decide whether a particular probate court accepts electronic filing; confirm filing, notarization, and service rules with the court handling the estate.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.