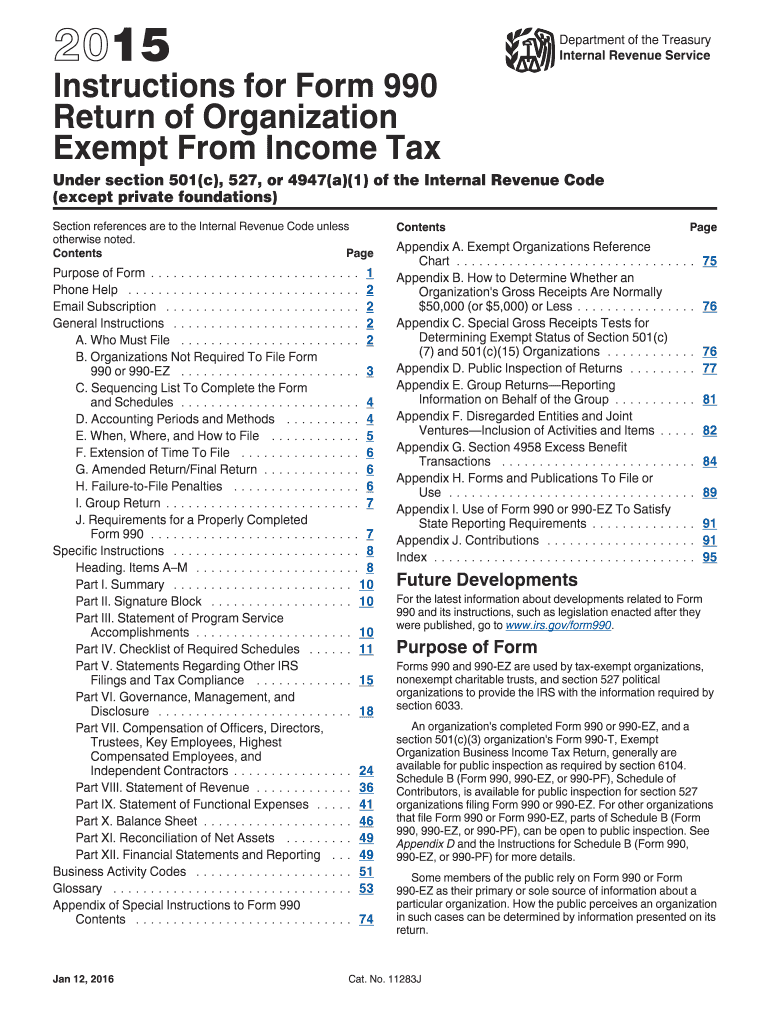
Form 990 Instructions (2015)
Use a Form 990 Instructions 2015 template to make your document workflow more streamlined.
What Form 990 Instructions (2015) explains
Form 990 Instructions (2015) explains how an exempt organization completes the 2015 IRS Form 990, including its core return, schedules, financial questions, governance disclosures, and filing mechanics. The instructions help organizations determine which parts apply, report amounts consistently, and identify supporting schedules before an authorized officer reviews the return. signNow can hold the instruction PDF and related approval records in one electronic workflow, but the instructions do not replace the IRS form, filing requirements, or professional tax advice. Confirm applicable requirements with the IRS and the organization’s tax adviser.
Who benefits from Form 990 workflows
Form 990 Instructions (2015) is most useful to nonprofit teams that coordinate financial reporting, schedule review, and authorized approval.
A small nonprofit finance office can upload the 2015 instructions, assign schedule reviews, and preserve one approval record without coordinating paper copies across staff and an external accountant. A regional nonprofit network can reuse controlled signNow templates for board or officer acknowledgments, while administrators manage permissions and retain separate audit trails for each organization’s Form 990 preparation cycle. A national nonprofit’s tax department can connect signNow with Microsoft 365, Google Workspace, or Salesforce to route Form 990 review records while central administrators control access and retention policies.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
Who uses Form 990 Instructions (2015)
Nonprofit finance teams
Tax directors and nonprofit finance teams use the 2015 instructions to interpret Form 990 schedules, reconcile financial data, and coordinate authorized officer review before submission.
Tax advisers
External accountants and authorized officers use controlled copies to review organizational data, resolve schedule questions, and retain evidence of internal approval.
How Form 990 instructions move through signNow
Use signNow to prepare the 2015 instructions, coordinate authorized reviewers, and retain a traceable completion record.
Upload: Upload the 2015 instruction document Review: Review fields against IRS guidance Send: Route acknowledgments to authorized officers Archive: Store the completed record and audit trail
Complete Form 990 instructions online
Follow a controlled signNow workflow for reviewing the 2015 instructions and documenting authorized approval.
Upload:
Upload the 2015 instructions PDF. Check:
Review schedules and required fields. Assign:
Add authorized officer fields. Send:
Send for electronic approval. Store:
Export the completed record.
How the signNow audit trail works
The audit trail records the approval evidence surrounding Form 990 Instructions (2015), rather than replacing the IRS return or filing process.
Authenticate signer:
Timestamp action:
Hash document:
Seal record:
Track activity:
Retrieve evidence:
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Recommended Form 990 workflow setup
Use a controlled preparation and approval workflow that preserves the 2015 instructions, signer identity, and filing-related records.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification with SMS OTP |
| Signature type | Typed or drawn electronic signature |
| Audit trail | Enabled with completion certificate |
| Document retention | Three years from filing (IRC §6501(a)) |
| Encryption | TLS 1.2/1.3 and AES-256 |



Find and fill out the correct 2015 form 990 instructions
airSlate SignNow helps you fill in and sign documents in minutes, error-free. Choose the correct version of the editable PDF form from the list and get started filling it out.
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| IRS 990 Instructions 2022 | 4.8 Satisfied (1096 Votes) | |
| IRS 990 Instructions 2021 | 4.8 Satisfied (1287 Votes) | |
| IRS 990 Instructions 2020 | 4.8 Satisfied (1427 Votes) | |
| IRS 990 Instructions 2019 | 4.8 Satisfied (351 Votes) | |
| IRS 990 Instructions 2018 | 4.8 Satisfied (2833 Votes) | |
| IRS 990 Instructions 2017 | 4.7 Satisfied (425 Votes) |
Platform requirements for Form 990 workflows
Form 990 Instructions (2015) can be reviewed in signNow through Chrome, Firefox, Safari, or Edge on Windows and macOS. The signNow mobile apps support iOS and Android access for review and signing tasks.
Browsers Chrome, Firefox, Safari, and Edge Desktop systems Windows and macOS desktop access Mobile apps iOS and Android signNow apps
Organizations should confirm that managed devices permit signNow access, electronic-record consent, and required authentication. Enterprise deployments can evaluate SSO provisioning, API access, and retention controls against their nonprofit governance policy, IRS recordkeeping practices, and applicable state requirements.
Retention periods for Form 990 records
Retain the completed return, approval evidence, and supporting records according to the applicable federal and state rules.
Three years after filing
Six years for major understatement
Indefinite for fraud
Indefinite without filing
State period may be longer
Record-keeping practices for Form 990
Preserve the 2015 instructions, completed review record, audit trail, and supporting schedules with retention decisions tied to IRS and state requirements.
Preserve the exact 2015 version
Apply the applicable IRS period
Separate drafts from approvals
Archive supporting schedules securely
Privacy and disclosure pitfalls
Personal addresses, officer information, and financial details can be exposed when the wrong Form 990 copy is shared externally. An officer’s approval may be captured without documenting the organization’s consent to electronic records under ESIGN requirements. Broad workspace permissions can let unauthorized users alter Form 990 working files before the final review. Separate versions of the 2015 instructions can cause staff to apply schedule guidance inconsistently across one filing.
Security for Form 990 records
Encryption:
Security report:
Information security:
Electronic records:
Signer authentication:
Protected information:
Legal standing of electronic approval records
For U.S. transactions, ESIGN (15 U.S.C. ch. 96) and applicable UETA laws generally recognize electronic records and signatures when intent, consent, attribution, and reproducible retention are demonstrated. Those laws do not replace IRS filing rules and exclude wills, codicils, certain court orders, and family-law decrees.

Documents outside this workflow
Notarization rules
Wills and codicils
Court filings
Family law
Real-estate deeds
Key performance indicators that demonstrate SignNow's proven track record.
Form 990 Instructions troubleshooting
Resolve document-version, approval, plan, retention, and compliance questions before relying on a completed Form 990 workflow.
Upload the Form 990 Instructions (2015) PDF as the source document, then use signNow’s field tools to add review, date, and acknowledgment fields. Auto-detection can assist preparation, but staff must compare every field with the IRS instructions.
Business includes legally binding eSignatures, templates, audit trails, and mobile apps at $8/user/month when billed annually. Business Premium adds bulk send at $15/user/month; choose it only when repeated distribution is required.
Use signNow’s audit trail to record the signer, timestamps, actions, and completion certificate. ESIGN and UETA establish electronic-signature validity when intent, consent, attribution, and record retention requirements are satisfied.
The 2015 instructions explain Form 990 completion but do not authorize an IRS filing by themselves. Complete the applicable IRS return and schedules, then follow the IRS filing method and deadline that apply to the organization.
Keep the signed approval record and related tax documents according to the organization’s record policy and applicable IRS requirements. IRC §6501(a) generally allows assessment for three years after filing, with longer periods for specific circumstances.
Business plans include ISO 27001 and SOC 2 Type II details, while HIPAA compliance requires a BAA. Select stronger authentication, access controls, and retention practices when the workflow contains sensitive donor or officer information.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.