Consumer Loan Application (2013 2026)
Create a custom Consumer Loan Application Pdf 2013 that meets your industry’s specifications.
What the consumer loan application does
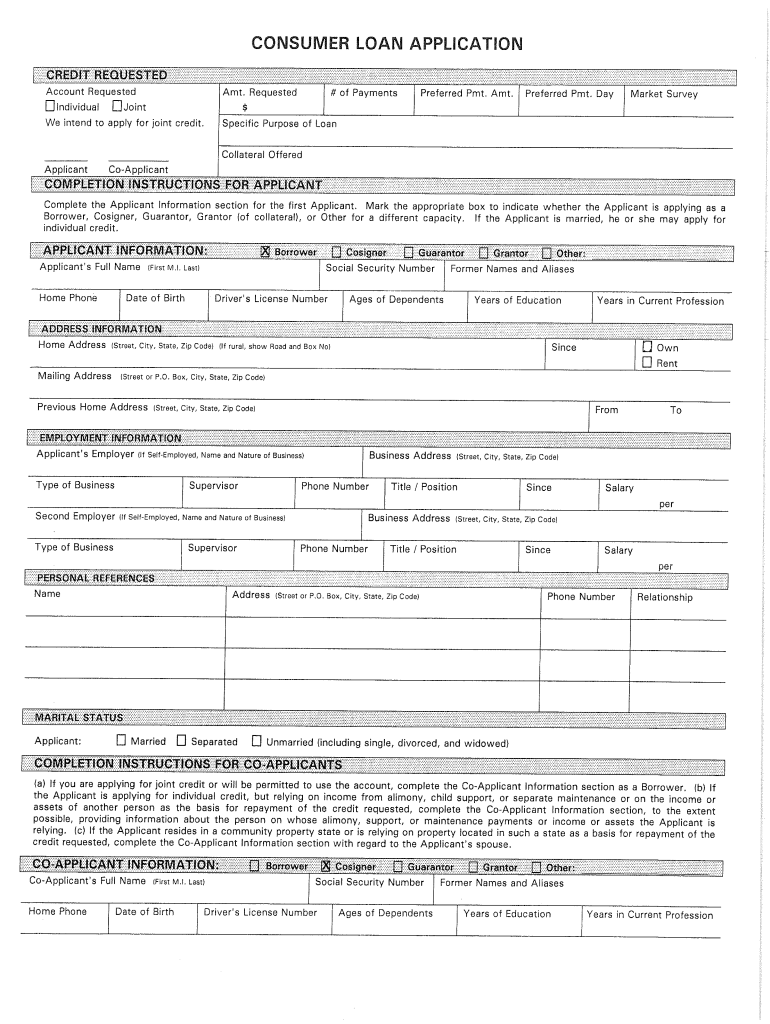
A Consumer Loan Application (2013 2026) collects the borrower information a lender needs to evaluate a personal credit request. Applicants generally provide identifying details, requested loan terms, income, employment, housing costs, assets, liabilities, and authorization for the lender to review the submission. The form is not a government tax filing or a universal federal form; its exact fields depend on the lender’s template. With signNow, a lender uploads the PDF, adds fillable fields and signature blocks, sends it to the borrower, and stores the completed record with an audit trail.
Who completes this loan application
Consumer lending teams at credit unions use the Consumer Loan Application (2013 2026) to collect borrower identity, income, employment, housing, and requested-loan details before underwriting. A signNow template helps loan officers send the same controlled application to applicants and preserve signed records for review. Community-bank loan officers use this application when applicants need to complete financial information remotely. signNow lets the officer upload the Consumer Loan Application (2013 2026), place fields over borrower sections, request signatures, and retain the completed PDF with its audit trail for internal processing.
Who uses the consumer loan application
Consumer lenders
Loan officers use the application to gather borrower identity, income, employment, housing, and requested-loan information before underwriting. A controlled signNow template standardizes required fields, routes the document to each signer, and produces a completed PDF with an audit trail for the lender’s file.
Borrowers
Borrowers and co-borrowers complete their assigned sections, review the requested loan information, and sign the authorization and certification portions. Remote signing helps applicants return the Consumer Loan Application (2013 2026) without printing, scanning, or coordinating an in-person meeting.
How the loan application workflow works
The signNow workflow moves the Consumer Loan Application (2013 2026) from lender preparation through borrower completion and documented storage.
Upload: Upload the lender-approved PDF. Prepare: Auto-detect fields, then correct placements. Assign: Assign borrower and co-borrower recipients. Complete: Send, sign, and store the completed record.
Features for consumer loan applications
signNow connects field preparation, borrower signing, routing, and evidence preservation around the lender’s Consumer Loan Application (2013 2026).
Field placement
Upload the Consumer Loan Application (2013 2026) PDF and add borrower, co-borrower, lender, date, initials, and signature fields without rebuilding the document from scratch.
Remote signing
Send the application to the borrower by email or signing link, making remote completion possible when an office appointment is unnecessary.
Signer routing
Route the application to a co-borrower or lender representative in a defined order, reducing missed signatures and incomplete submission packages.
Audit trail
Capture timestamps, signer actions, and document history in an audit trail that travels with the completed loan application record.
Reusable template
Reuse an approved application template so loan officers consistently collect the lender’s required borrower and authorization information across new submissions.
Mobile access
Allow applicants to review and sign from supported mobile apps when completing the Consumer Loan Application (2013 2026) away from a desktop.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Security for borrower applications
Transport encryption:
Storage encryption:
Independent assurance:
Security certification:
Electronic signatures:
Protected health information:



Find and fill out the correct consumer loan application form unibank
airSlate SignNow helps you fill in and sign documents in minutes, error-free. Choose the correct version of the editable PDF form from the list and get started filling it out.
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| *2013 UniBank Consumer Loan Application [2013-05] 2013 | 4.8 Satisfied (10092 Votes) |
What the audit trail records
The audit trail documents the evidence surrounding completion of the Consumer Loan Application (2013 2026), rather than replacing the application itself.
Authenticate signer:
Timestamp event:
Hash document:
Seal record:
Build audit trail:
Retrieve evidence:
Recommended loan application setup
Configure the Consumer Loan Application (2013 2026) around borrower identity, signing evidence, controlled access, and the lender’s documented retention policy.
| Setting | Recommendation |
|---|---|
| Authentication method | Email link with SMS OTP |
| Signature type | Electronic signature with intent |
| Audit trail | Export with completed PDF |
| Document retention | Follow lender policy and state law |
| Encryption | TLS 1.2/1.3 and AES-256 |
Record-keeping practices for loan applications
Preserve the completed application, consent evidence, audit trail, and supporting records under a documented lender retention policy.
Apply the lender’s documented retention schedule
Export the audit trail with each application
Limit access to borrower financial information
Archive completed applications securely
Retention periods for loan records
The application has no single nationwide retention period; apply the lender’s policy and the rule governing the underlying record.
Three years: federal tax records
Six years: substantial understatement
Indefinite: fraud or no return
Until resolved: legal hold
State period: longer requirement
Privacy and completion pitfalls
Borrowers may enter income or housing figures inconsistently across the application and supporting documents, forcing underwriting staff to request clarification before evaluating the loan request. A lender may send a Consumer Loan Application (2013 2026) without capturing electronic-record consent, creating an evidence gap for consumer-facing electronic delivery under 15 U.S.C. §7001(c). Unrestricted sharing can expose Social Security numbers, account details, employment data, and liabilities to employees who do not need access to the application. Missing co-borrower signatures, dates, or authorization fields can leave the application incomplete and delay underwriting or require a new signing request.
Consumer loan application troubleshooting
These answers address field assignment, electronic consent, signer authentication, plan selection, and legal compliance for this loan application workflow.
Upload the original Consumer Loan Application (2013 2026) PDF again and inspect each detected field before sending. signNow templates allow the sender to add or adjust fields manually, which helps correct missing borrower, co-borrower, date, and signature placements.
Use signNow’s routing controls to assign separate fields to the borrower, co-borrower, and lender representative. Check each recipient’s role before sending so one signer cannot complete another person’s certification or authorization section.
For a consumer-facing electronic record, provide the ESIGN disclosure required by 15 U.S.C. §7001(c), including paper-record access and withdrawal procedures. signNow can capture the signing event, but the lender remains responsible for the disclosure and consent design.
The Business plan is listed at $8/user/month when billed annually and includes legally binding eSignatures, templates, and audit trails. Business Premium is $15/user/month annually and adds bulk send; choose based on the lender’s documented workflow.
signNow’s Business plan includes audit trails, while Enterprise adds advanced signer authentication. The lender should select an authentication method appropriate for borrower risk, then preserve the resulting identity and event evidence with the application.
signNow is ESIGN and UETA compliant, but those laws do not replace lender obligations under applicable consumer-credit, privacy, or state laws. Review the application’s disclosures, consent language, retention policy, and state requirements before production use.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.