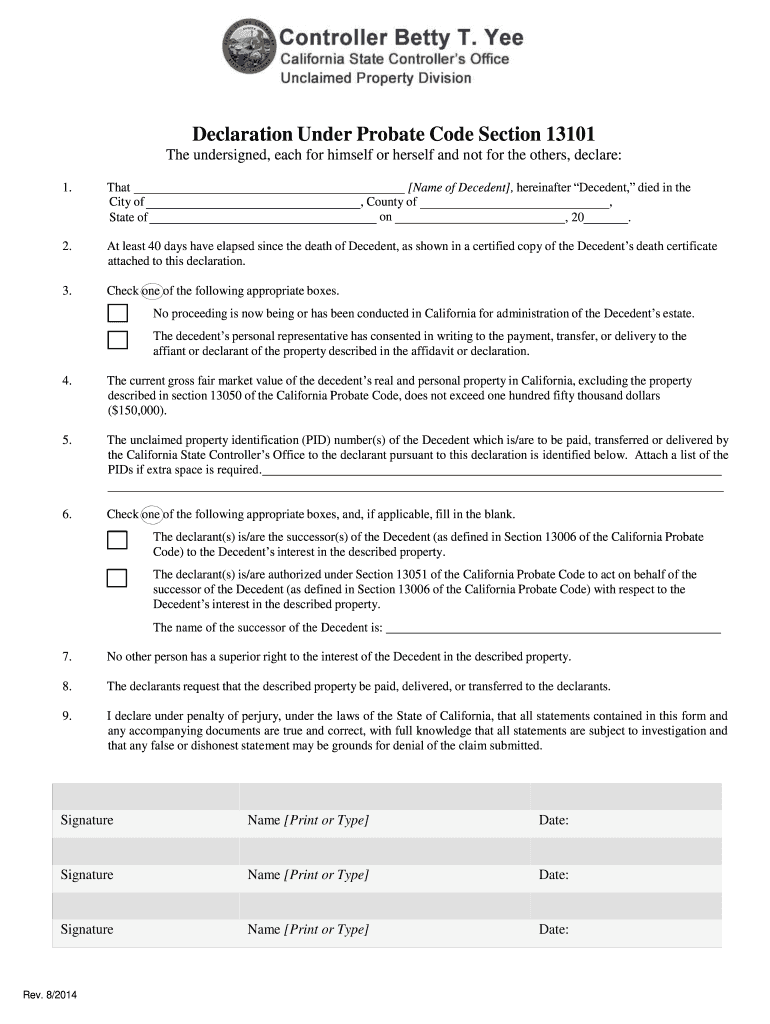
Declaration Under Probate Code Section 13101
Use a Declaration Under Probate Code Section 13101 2014 template to make your document workflow more streamlined.
What this California probate declaration does
Declaration Under Probate Code Section 13101 is a California small-estate declaration used by an eligible successor to request transfer of qualifying personal property without a full probate administration. The declarant identifies the decedent, confirms statutory eligibility, describes the property, and signs under the required formalities. The recipient, such as a bank or custodian, may request supporting records and independent verification. It is not a will, court order, deed, or family-law filing, and California Probate Code requirements control whether the recipient can rely on it.
Legal standing and document scope
A Section 13101 declaration can support a personal-property transfer when it satisfies California Probate Code requirements and is accepted by the relevant holder. ESIGN and UETA generally support electronic records and signatures, but they exclude wills, testamentary trusts, court orders, and family-law decrees. Confirm notarization, delivery, and institutional requirements before relying on an electronic copy.

Who commonly handles this declaration
A California probate attorney can prepare a Section 13101 declaration for a successor seeking personal property without opening a full probate estate. The attorney uses signNow to collect the declarant’s information, signature, supporting records, and audit trail while preserving a reviewable electronic copy for the client file. A bank or credit-union estate operations specialist may receive a Section 13101 declaration before releasing qualifying personal property. signNow helps the institution route the declaration to authorized reviewers, capture signer authentication, and retain the completed document with its certificate and transaction history.
Who uses the declaration and why
Probate practices
California probate attorneys and estate paralegals use the declaration for successor-property transfers, supporting it with death certificates, entitlement evidence, and recipient-specific documentation before signature collection.
Financial custodians
Banks, credit unions, and property custodians review declarations before releasing qualifying personal property, using controlled routing, identity checks, and completed audit records for internal approval.
Complete the declaration in signNow
Use this workflow to prepare the Section 13101 declaration, collect the required signature, and preserve evidence of completion.
Upload form:
Upload the approved declaration PDF. Check fields:
Review detected fields and add missing signature, date, and initials fields. Add recipients:
Enter the declarant and reviewer details. Send document:
Send the declaration for signature and required review. Archive record:
Download the completed PDF and audit trail.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Recommended workflow configuration
Configure the Section 13101 workflow around signer identity, recipient acceptance, document integrity, and restricted record access.
| Setting | Recommendation |
|---|---|
| Authentication method | Email link with SMS verification |
| Signature type | Electronic signature with intent |
| Audit trail | Export certificate with completed PDF |
| Document retention | Follow recipient policy and law |
| Encryption | TLS 1.2/1.3 and AES-256 |
What the audit trail records
The audit trail documents how the Section 13101 declaration moved from delivery through signature and completion, supporting later review by authorized parties.
Authenticate signer:
Capture timestamps:
Record document hash:
Seal transaction:
Log activity:
Export evidence:
Security controls for estate records
Transport encryption:
Stored encryption:
Security certification:
Information security:
Electronic signature law:
Signer authentication:
Find and fill out the correct declaration probate form
airSlate SignNow helps you fill in and sign documents in minutes, error-free. Choose the correct version of the editable PDF form from the list and get started filling it out.
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| *2014 CA Declaration Under Probate Code Section 13101 [2014-08] 2022 | 4.8 Satisfied (166 Votes) | |
| *2014 CA Declaration Under Probate Code Section 13101 [2014-08] 2014 | 4.8 Satisfied (3785 Votes) |
Platform requirements for completing the form
A current Chrome, Firefox, Safari, or Edge browser on Windows, macOS, iOS, or Android can access the signNow workflow for this declaration. Use a TLS 1.2 or later connection when uploading personal and estate information.
Supported browsers Chrome, Firefox, Safari, and Edge Operating systems Windows 10, macOS, iOS, and Android Secure connection TLS 1.2 or later connection
Use a managed device when the declaration contains account numbers, addresses, or death-related records. Organizations can apply signNow access controls, SSO provisioning, and audit-trail export policies before sending the completed Section 13101 declaration to a bank, custodian, or legal file.
Processing stages for the declaration
The workflow has four operational stages, while California Probate Code Section 13101 does not establish one universal processing deadline.
Prepare the document
Deliver to signers
Collect signatures
Archive the record
Retention rules for related records
The declaration itself has no single universal retention period in the supplied California authority. Apply the controlling record category and the receiving institution’s documented policy.
Three years: federal tax records
Six years: substantial understatement
Indefinite: fraud or no return
No fixed period: probate declaration
Recipient policy: longer period
Best practices for Section 13101
Accuracy, recipient confirmation, and a complete audit record reduce avoidable rejection of a Section 13101 declaration.
Verify every statutory fact before signing
Preserve the approved declaration template
Confirm recipient acceptance requirements first
Archive the complete transaction record
Privacy and disclosure pitfalls
Uploading a death certificate or account record to the wrong recipient can expose addresses, account numbers, and other estate information. A declarant may sign without reviewing statutory eligibility, successor status, property description, or the recipient’s additional documentation requirements. Shared links, unrestricted folders, or broad administrator permissions can expose a completed Section 13101 declaration beyond the estate matter team. Consumer-facing electronic delivery may require consent disclosures and access procedures under 15 U.S.C. §7001(c).
State-specific limits and exclusions
Notarization requirement
Wills excluded
Family law documents
Real-estate deeds
Section 13101 troubleshooting questions
These answers address field setup, statutory scope, electronic-consent requirements, authentication evidence, and signNow plan limitations relevant to this declaration.
Upload the original PDF again, then use signNow’s field detection and manually confirm each signature, date, and initials field. Do not assume a blank line is an interactive field; inspect the completed preview before sending the California declaration.
The Section 13101 declaration is not a will, court order, deed, or family-law decree. ESIGN and UETA exclusions still apply, so confirm California Probate Code requirements and the recipient’s acceptance rules before treating an electronic signature as sufficient.
Use signNow’s audit trail and completion certificate to document intent, attribution, timestamps, delivery, and signer actions. Those records support evidentiary review, but they do not cure missing statutory eligibility, notarization, or recipient-specific documentation.
The Business plan includes legally binding eSignatures, audit trails, templates, and mobile apps at $8 per user per month when billed annually. It includes 100 signature invites per user annually; overage fees may apply.
Consumer-facing electronic records can require a paper-rights disclosure, electronic-access capability, and withdrawal procedures under 15 U.S.C. §7001(c). Add those controls when the declarant is a consumer and the transaction falls within the statute.
If a recipient requires notarization, use the recipient’s specified California procedure rather than assuming an electronic signature satisfies it. signNow can preserve the signed record, but platform completion does not replace an independently required notarial act.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.