1003 (2005)
Use a Blank 1003 2005 template to make your document workflow more streamlined.
What 1003 (2005) covers
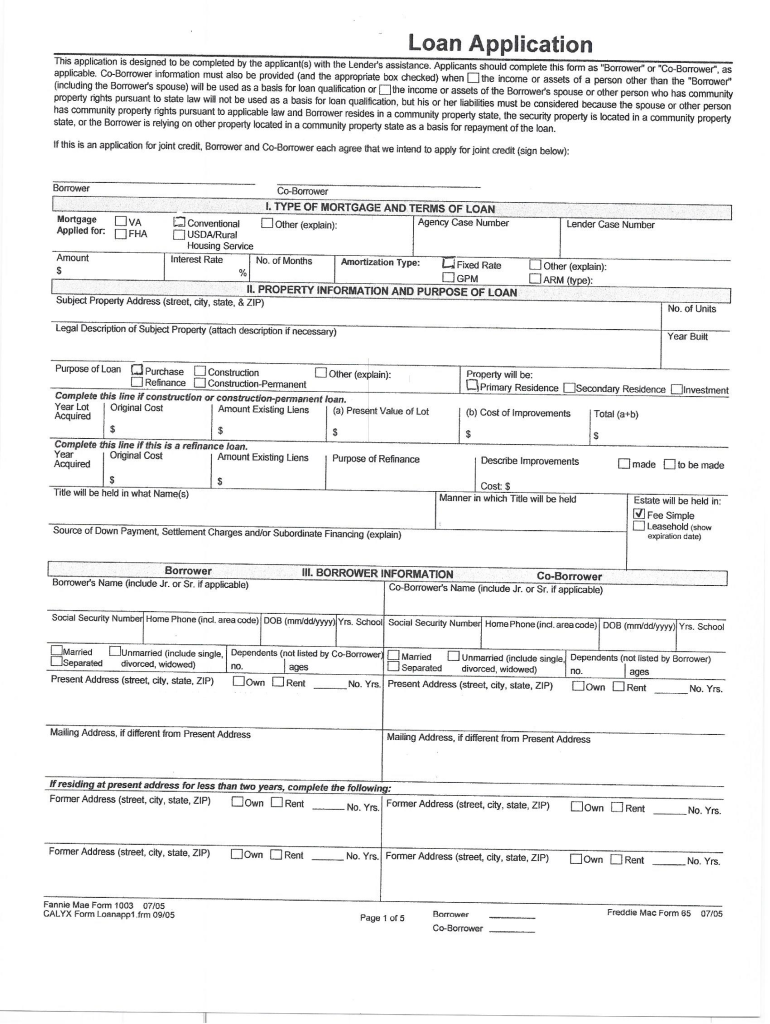
1003 (2005) is the Uniform Residential Loan Application used to collect the information a lender needs to evaluate a residential mortgage request. It organizes the borrower’s identity, residence history, employment, income, assets, liabilities, property, loan terms, and declarations in one application record. Borrowers complete the applicable sections, review accuracy, and sign where required. Loan officers and processors then use the completed form with supporting documentation during underwriting. Electronic signing can be legally recognized under ESIGN and applicable state law when intent, consent, attribution, and record retention are established.
Who benefits from 1003 (2005) workflows
1003 (2005) is most useful where mortgage application data, signatures, supporting records, and audit evidence must remain coordinated.
Independent mortgage brokers can prepare 1003 (2005) applications for borrowers, assign co-borrower fields, and collect signatures remotely while keeping each application’s activity record organized for lender submission. Mortgage lenders and loan-processing teams can reuse controlled templates, route applications to the right parties, and preserve signed 1003 (2005) records with audit trails for underwriting and compliance review. Enterprise lending operations can connect 1003 (2005) workflows with systems such as NetSuite, Salesforce, Google Drive, or Box, reducing manual transfer between application processing and approved document storage.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
Who uses 1003 (2005)
Mortgage lending
Mortgage lenders, loan officers, and borrowers use 1003 (2005) to organize borrower identity, employment, income, assets, liabilities, property details, and requested financing before underwriting review.
Loan processing
Loan processors and compliance teams use the completed application to coordinate supporting documents, verify entered information, and preserve a consistent record for the lender’s review process.
Features for completing 1003 (2005)
The workflow focuses on accurate borrower data, coordinated signatures, traceable activity, and controlled storage for mortgage processing.
Structured application
Captures borrower identity, addresses, employment, income, assets, debts, property details, and requested financing in one organized application record.
Field preparation
Lets the sender upload 1003 (2005), detect fillable fields, and prepare the document for borrower or co-borrower completion.
Signer routing
Routes the application to the required parties in a defined signing order, reducing manual email coordination during loan processing.
Audit trail
Preserves timestamps, signer activity, and document history so the lender can review evidence associated with the completed application.
Reusable templates
Supports reusable templates for recurring 1003 (2005) workflows while allowing transaction-specific borrower and property information.
Secure storage
Provides a completed electronic record that authorized users can store with the loan file and retrieve for review.
Complete 1003 (2005) in signNow
Prepare the exact application, confirm the assigned parties, and preserve the completed record with its audit evidence.
Upload form:
Upload the 1003 (2005) PDF to signNow. Check fields:
Use auto-detection, then verify each fillable field. Assign signers:
Assign borrower and co-borrower fields correctly. Send application:
Send the application through the selected workflow. Store record:
Review the signed copy and audit trail.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Recommended 1003 (2005) workflow setup
Use a controlled signing workflow that verifies participants, preserves evidence, and places the completed application in the lender’s approved record system.
| Setting | Recommendation |
|---|---|
| Authentication method | Email link with SMS OTP |
| Signature type | Typed or drawn electronic signature |
| Audit trail | Enabled with exportable completion record |
| Document retention | Lender-approved loan-file schedule |
| Encryption | TLS in transit and AES-256 at rest |
How the 1003 (2005) audit trail works
The audit trail preserves evidence showing who handled the 1003 (2005), what they did, and when each event occurred.
Authenticate signer:
Timestamp actions:
Hash document:
Seal record:
Log events:
Export evidence:
Find and fill out the correct calyx point 1003 forms
airSlate SignNow helps you fill in and sign documents in minutes, error-free. Choose the correct version of the editable PDF form from the list and get started filling it out.
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| Calyx Form - Loanapp1.frm 2009 | 4.8 Satisfied (2439 Votes) | |
| Calyx Form - Loanapp1.frm 2005 | 4.8 Satisfied (4298 Votes) |
Security for 1003 (2005)
Digital certificates:
Certificate identity:
Two-factor authentication:
SMS OTP:
ID verification:
Audit evidence:
Platform requirements for 1003 (2005)
Complete 1003 (2005) in a supported browser such as Chrome, Firefox, Safari, or Edge, using Windows or macOS; signNow also provides iOS and Android mobile apps.
Browsers Chrome, Firefox, Safari, Edge Desktop systems Windows and macOS Mobile access iOS and Android apps
Lenders should also confirm managed-device policies, network access, identity-verification availability, and storage permissions before deployment. Enterprise workflows may require SSO, API access, or controlled provisioning so completed 1003 (2005) records move into the approved loan-file environment.



Risks when 1003 (2005) is mishandled
Incomplete application
Data discrepancy
Weak attribution
Missing audit trail
Examples of signNow document workflows
Real-estate and enterprise customer stories show workflow patterns relevant to preparing, routing, signing, and retaining 1003 (2005).
Real estate
Martin Properties needed to execute property-related documents remotely while maintaining an efficient mobile workflow for necessary parties.
- Mobile and offline document processing
Tim Martin, founder of Martin Properties, reports that his organization processes and executes documents online with compliance and built-in security, including mobile and offline work. The story illustrates how a real-estate operation can use signNow to coordinate signed property documents without relying exclusively on in-person meetings.
Enterprise operations
Xerox connected signNow with NetSuite to coordinate signatures on documents requiring the right people and formats.
- Integrated role-based document routing
Kodi-Marie Evans, director of NetSuite Operations at Xerox, describes flexibility in obtaining the right signatures on the right documents and formats through the integration. For a 1003 (2005) workflow, comparable integration design can help connect application routing with an enterprise system, subject to the lender’s controls.
Troubleshooting 1003 (2005) workflows
These answers address field detection, signer identity, electronic-signature validity, retention, and plan selection for 1003 (2005).
Upload the correct 1003 (2005) PDF and confirm that OCR or auto-detection identified every intended field. Add missing text, date, initials, or signature fields manually before assigning recipients. Preview the document from each signer’s perspective to catch misplaced or overlapping fields.
Use signNow’s recipient roles and routing order to distinguish borrower, co-borrower, loan officer, and other required participants. A Business plan supports templates and audit trails; confirm the selected plan includes the routing controls your lending workflow requires.
The 1003 (2005) may be signed electronically when the transaction satisfies ESIGN and applicable state requirements, including intent, consent, attribution, and record retention. For consumer-facing records, provide the ESIGN paper-record disclosure and access information required by 15 U.S.C. §7001(c).
Enable stronger signer verification when the lender’s risk policy requires it. signNow supports two-factor authentication and SMS OTP; advanced signer authentication is associated with the Enterprise plan in the product plan details.
Export the completed 1003 (2005) and its audit trail from signNow, then place both in the lender’s approved loan-file repository. Retention is controlled by applicable lender, investor, federal, and state requirements rather than one universal period.
The Business plan is listed at $8 per user per month with annual billing, while Business Premium is $15 and includes bulk send. Paid plans include 100 signature invites per user per year; overage terms should be reviewed before high-volume deployment.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.