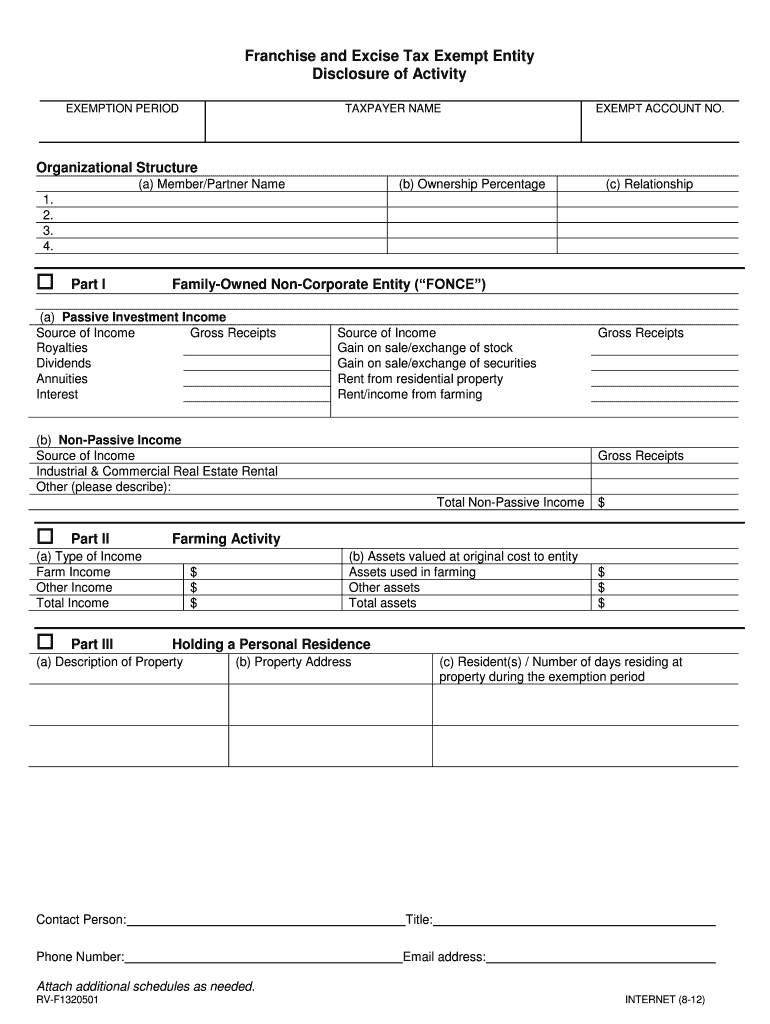
Franchise And Excise Tax Exempt Entity Disclosure Of Activity Form (2012)
Get started with a Franchise And Excise Tax Exempt Entity Disclosure Of Activity Form 2012, complete it in a few clicks, and submit it securely.
What this tax exemption disclosure does
The Franchise And Excise Tax Exempt Entity Disclosure Of Activity Form (2012) is a disclosure used by an exempt entity to report activity relevant to franchise and excise tax treatment. It identifies the entity, describes applicable activity, and records the basis for claiming exempt status. The completed form should match the entity’s governing records and supporting tax documentation. After review, authorized personnel can complete and sign the form electronically through signNow, preserving the signed document and an audit trail for internal records and later review.
Who uses this tax activity disclosure
Tax-exempt entities
Tax-exempt entities use this disclosure to identify qualifying activity, document their exemption basis, and support consistent franchise and excise tax reporting.
Tax professionals
Accountants and administrators review activity details, preserve supporting records, and coordinate authorized signatures before submitting the completed disclosure.
Business types using this disclosure
The form is most useful where an entity must explain activity supporting its franchise and excise tax exemption position.
A tax-exempt nonprofit or other qualifying entity uses the disclosure to document its activity and exemption position before authorized personnel sign the 2012 form for its tax records. A small-business accountant prepares the entity information, checks the activity description against supporting records, and routes the completed disclosure to an officer or authorized representative for execution. An enterprise tax department uses reusable signNow templates, controlled signer routing, and audit trails to standardize entity disclosures while preserving each signed record with its supporting compliance file.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
How this disclosure moves through signNow
Complete this four-stage flow to prepare, sign, and preserve the Franchise And Excise Tax Exempt Entity Disclosure Of Activity Form (2012).
Upload form: Upload the 2012 disclosure PDF to signNow. Prepare fields: Review detected fields and add missing fields. Route signing: Send the disclosure to authorized representatives. Archive record: Store the signed form with its audit trail.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
How the disclosure audit trail works
The audit trail records identity, timing, document integrity, and retrieval details after this tax disclosure moves through signing.
Signer authentication:
Timestamp capture:
Document hashing:
Tamper-evident seal:
Action history:
Audit export:
Features for completing this disclosure
signNow organizes the 2012 disclosure workflow around accurate field placement, authorized signing, audit evidence, and controlled record handling.
Form preparation
Upload the 2012 disclosure and place fields over its entity, activity, exemption, date, and signature areas without recreating the form.
Signer routing
Route the completed disclosure to authorized representatives in a defined signing order, reducing missed approvals before tax records are finalized.
Audit trail
Capture signer actions, timestamps, and document history so the entity can connect the executed disclosure with its internal tax file.
Reusable template
Keep a reusable copy of the disclosure workflow for recurring entity reviews while preserving each completed transaction separately.
Mobile signing
Use signNow’s mobile apps when an authorized representative reviews or signs the disclosure away from a desktop workstation.
Record export
Export the completed disclosure and audit evidence for controlled storage with the entity’s tax and governance records.
Find and fill out the correct franchise and excise tax exempt entity disclosure of activity 2012 form
airSlate SignNow helps you fill in and sign documents in minutes, error-free. Choose the correct version of the editable PDF form from the list and get started filling it out.
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| TN RV-F1320501 2016 | 4.8 Satisfied (1815 Votes) | |
| TN RV-F1320501 2012 | 4.6 Satisfied (722 Votes) | |
| TN RV-F1320501 2009 | 4.7 Satisfied (316 Votes) |
Recommended disclosure workflow setup
Configure the 2012 disclosure around authorized signing, documented evidence, encryption, and the applicable tax-record retention rule.
| Setting | Recommendation |
|---|---|
| Authentication method | Email link with SMS OTP |
| Signature type | Typed or drawn eSignature |
| Audit trail | Enabled with completion certificate |
| Document retention | Three years from filing under IRC §6501(a) |
| Encryption | AES-256 at rest and TLS 1.2/1.3 |
Security for tax disclosure records
Stored data:
Data transfer:
Security report:
Security standard:
Electronic signatures:
Privacy controls:
Privacy and disclosure pitfalls
Entering an entity name that differs from governing or tax records can create an identity mismatch during review. Describing activity too broadly may obscure why the entity claims franchise and excise tax exemption. Sending the disclosure before confirming signer authority can leave the executed record without proper organizational approval. Sharing completed records without access controls can expose entity tax information to unauthorized recipients.
Retention periods for tax disclosures
Keep this disclosure with the tax records it supports, applying the controlling federal rule and any longer state requirement.
Three years from filing
Six years for understatement
Indefinite for fraud
State period if longer
Policy-based supporting records
Best practices for preserving tax records
Accurate field review and controlled retention help connect the signed disclosure with the entity’s underlying tax evidence.
Match retention to the underlying tax record
Export the audit trail after completion
Validate entity and activity details
Document state retention requirements
Troubleshooting this tax disclosure workflow
These answers address field accuracy, signer access, electronic evidence, plan selection, and retention for the 2012 disclosure.
Open the uploaded PDF in signNow and inspect every field before sending. If auto-detection misses an entity, activity, date, or signature field, add the correct field manually and compare the final document with the original 2012 form.
The Business plan includes legally binding eSignatures, templates, audit trails, mobile apps, ISO 27001, SOC 2, and GDPR support. Business Premium adds bulk send; choose it only when repeated distribution requires that feature.
Use signNow’s audit trail to document signer actions, timestamps, and document history. ESIGN and UETA recognize electronic signatures when intent, consent, attribution, and record retention requirements are satisfied; retain the disclosure in a reproducible format.
If the signer cannot access the invitation, verify the email address, resend the request, or generate a signing link where appropriate. Do not forward a completed disclosure through an uncontrolled channel because tax information may be exposed.
Business Premium includes bulk send, while Enterprise adds advanced signer authentication, formula fields, and conditional fields. For one entity-specific disclosure, use direct signer routing rather than bulk distribution unless every recipient receives the correct form.
Apply the federal schedule to the tax records supporting the disclosure: IRC §6501(a) generally uses three years from filing, §6501(e) uses six years for a 25% understatement, and §6501(c) can require indefinite retention.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.