26 Usc 7530 Application Of Earned Income Tax Credit To
Use a 26 USC 7530 Application Of Earned Income Tax Credit To 2024 template to make your document workflow more streamlined.
What this reference means
26 U.S.C. § 7530 is a citation to the Internal Revenue Code, not enough information to identify a standalone IRS application. A person using this page should first confirm the current statutory text and determine which IRS form, schedule, authorization, or supporting record applies to the transaction. The citation alone does not establish taxpayer eligibility, a filing deadline, a signature requirement, or an issuing agency. After identifying the correct document, signNow can support upload, field placement, electronic signing, delivery, and audit-trail retention where ESIGN, UETA, IRS instructions, and applicable state law permit.
How to handle this statutory reference
26 U.S.C. § 7530 is a statutory reference, so verify the related IRS document before preparing or signing anything.
Confirm scope:
Confirm the authority and purpose before preparing any related tax record. Identify filing:
Use the applicable IRS form or schedule identified by the underlying transaction. Upload document:
Upload the relevant document and review detected fields in signNow. Prepare signing:
Add authorized recipients, signature fields, and required dates before sending. Store evidence:
Send the completed record and retain its audit trail with supporting evidence.
Recommended workflow configuration
Configure the workflow around the underlying IRS document, signer identity, applicable retention rule, and required evidence.
| Setting | Recommendation |
|---|---|
| Authentication method | Email authentication with SMS OTP |
| Signature type | Electronic signature under ESIGN and UETA |
| Audit trail | Export with the signed tax record |
| Document retention | Three years from filing under IRC §6501(a) |
| Encryption | TLS 1.2 or 1.3 and AES-256 |
Audit-trail handling for this record
An audit trail documents the signing event; it does not replace the IRS form, instructions, or authority supporting the tax position.
Authenticate signer:
Capture timestamps:
Protect document:
Seal record:
Export evidence:
Archive record:
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Record-keeping practices for this reference
Retention depends on the underlying tax record, not the citation alone; document the applicable authority before archiving.
Apply the correct federal retention period
Export the audit trail with the record
Archive taxpayer records securely
Match retention to the underlying record
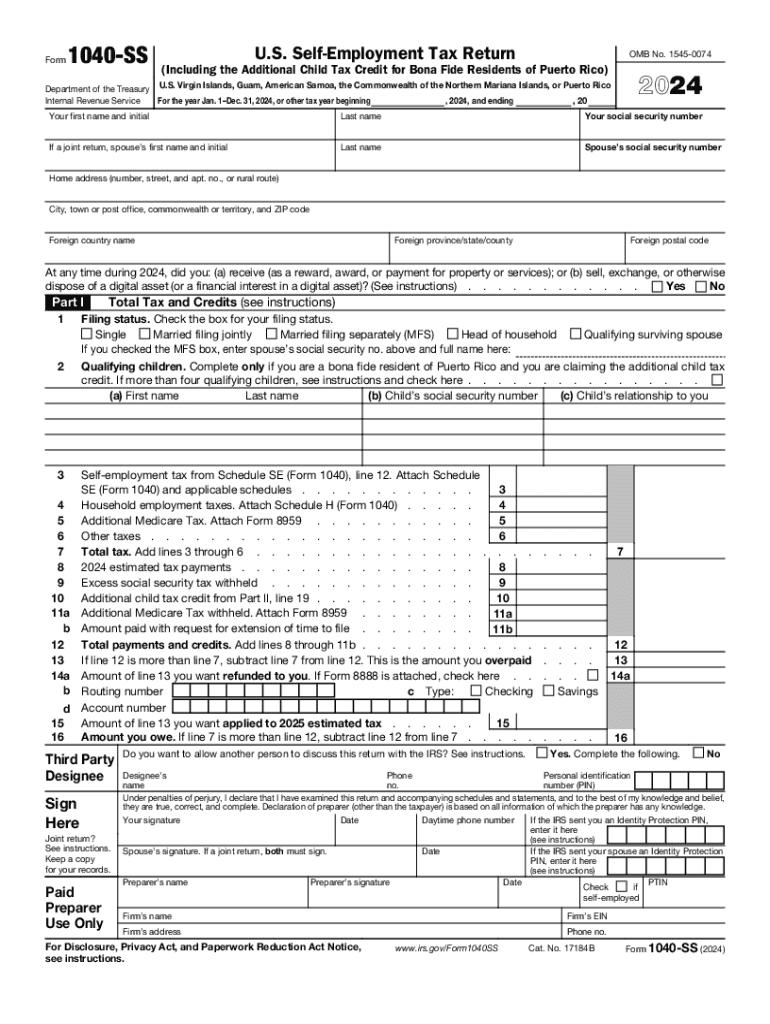
Find and fill out the correct 26 usc 7530 application of earned income tax credit to
airSlate SignNow helps you fill in and sign documents in minutes, error-free. Choose the correct version of the editable PDF form from the list and get started filling it out.
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| IRS 1040-SS 2024 | 4.6 Satisfied (87 Votes) | |
| IRS 1040-SS 2023 | 4.8 Satisfied (787 Votes) | |
| IRS 1040-SS 2022 | 4.8 Satisfied (2322 Votes) | |
| IRS 1040-SS 2021 | 4.8 Satisfied (2502 Votes) | |
| IRS 1040-SS 2020 | 4.8 Satisfied (900 Votes) | |
| IRS 1040-SS 2018 | 4.8 Satisfied (1334 Votes) |
Retention schedule for related tax records
The citation does not create its own retention period; apply the rule governing the actual tax record and filing.
Before preparation
Three years: federal tax records
Six years: 25% understatement
Indefinite: fraud or no return
State rules may extend
Security for related tax records
Encrypted transit:
Encrypted storage:
Independent assurance:
Security certification:
Electronic signatures:
Protected health information:
Challenges to address before signing
Treating a U.S. Code citation as a completed IRS application can lead to missing fields, unsupported claims, and incorrect filing instructions. Using an unverified earned-income threshold or deadline may misstate eligibility because the citation alone does not identify the underlying tax form. Sending taxpayer information without reviewing recipients, access permissions, and consumer electronic-record consent can create avoidable disclosure and evidence problems. Archiving only a signed PDF while omitting the signNow Audit Trail can weaken proof of delivery, signer action, and record integrity.
Risks requiring verification
Citation uncertainty
Wrong document
State-law variation
Missing audit trail
Troubleshooting this statutory reference
Most issues arise because this citation is treated as a form; first identify the actual IRS document and then configure its signing workflow.
Section 26 U.S.C. § 7530 is not itself an IRS form. Use the applicable IRS form or schedule identified by the transaction, then upload that document to signNow. Do not invent fields, a filing deadline, or an issuing agency from the citation alone.
The citation may be incomplete, mistyped, or sourced from a document library label. Confirm the text in the current U.S. Code and compare it with the related IRS instructions before collecting signatures or relying on the reference for tax treatment.
Business includes audit trails, templates, mobile apps, and legally binding eSignatures. Business Premium adds bulk send, while Enterprise adds advanced signer authentication. Select the plan based on workflow volume and control requirements, not the statutory citation.
A signNow signature can support electronic records under ESIGN and UETA when intent, consent, attribution, and record retention are established. Consumer-facing records may require the disclosure and access procedures in 15 U.S.C. §7001(c).
Export the signed document and Audit Trail from signNow, then preserve the supporting tax materials under the applicable IRS rule. IRC §6501(a) generally uses three years from filing, with six years for a 25% income understatement.
A citation-only document cannot establish tax eligibility or replace IRS instructions. Have a qualified tax professional verify the underlying form, taxpayer facts, filing position, and any applicable state requirements before submission or reliance.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.