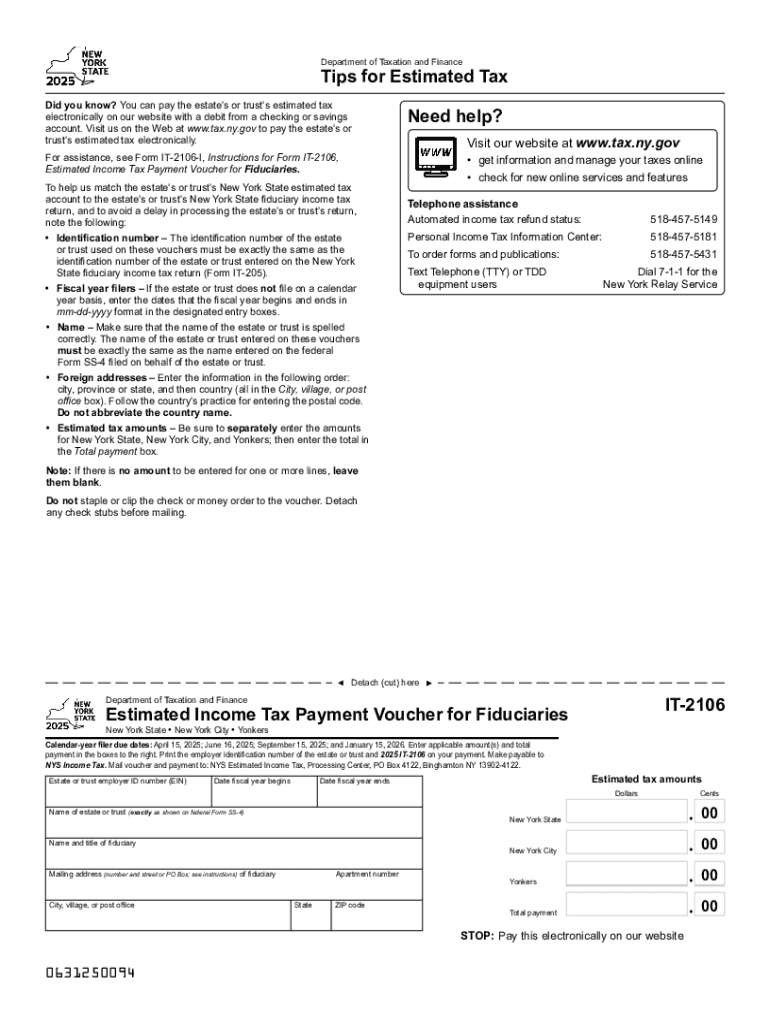
Form It 2106 Estimated Income Tax Payment Voucher For Fiduciaries Tax Year (2025 2026)
Use a Form IT 2106 Estimated Income Tax Payment Voucher For Fiduciaries Tax Year 2025 template to make your document workflow more streamlined.
What Form It 2106 covers
Form It 2106 Estimated Income Tax Payment Voucher For Fiduciaries Tax Year (2025 2026) is a payment voucher used with fiduciary estimated income tax reporting. It identifies the fiduciary taxpayer, tax period, estimated payment amount, and remittance details. Complete the applicable taxpayer and payment fields from the governing return and payment instructions, then review every amount before signing or submitting. signNow can upload the voucher, detect fillable fields, route it for an authorized signature, and preserve the completed record with an audit trail. Confirm filing and payment instructions with the applicable tax authority.
Who uses this fiduciary payment voucher
Fiduciaries
Fiduciaries and estate administrators use the voucher to document estimated tax payments for estates or trusts, entering the correct tax year, taxpayer details, payment amount, and authorized signature before retaining the completed record.
Tax professionals
Tax professionals and finance teams prepare payment vouchers from fiduciary tax records, route them to authorized signers, and preserve the signed voucher and audit trail for internal controls and tax documentation.
How the voucher workflow works
The signNow process keeps preparation, authorization, and record retention in one documented sequence.
Upload voucher: Upload the fiduciary payment voucher PDF to signNow. Check fields: Auto-detect fields and verify tax-year information. Route signature: Assign the authorized fiduciary signer and send. Archive record: Store the signed voucher with its audit trail.
Recommended voucher workflow setup
Use role-based access, a retained audit trail, and secure storage when preparing this fiduciary payment voucher.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification with SMS OTP |
| Signature type | Typed or drawn electronic signature |
| Audit trail | Enabled with completion certificate |
| Document retention | At least 3 years from filing (IRC §6501(a)) |
| Encryption | TLS 1.2/1.3 and AES-256 |
What the voucher audit trail records
The audit trail documents how the fiduciary payment voucher moved from upload through authorization and final record retention.
Authenticate signer:
Capture timestamp:
Protect document:
Seal completion:
Retrieve evidence:
Export records:
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Voucher preparation and signing stages
Processing depends on the accuracy of the fiduciary’s tax information and the signer’s review of the payment amount.
Prepare the voucher
Deliver to signer
Review and sign
Archive the record
Retention periods for voucher records
Choose the retention period that matches the record’s legal category and any longer state or organizational requirement.
Three years from filing
Six years for HIPAA
Six years for broker-dealers
Three years for payroll
Seven years for SOX
Find and fill out the correct form it 2106 estimated income tax payment voucher for fiduciaries tax year 772032559
airSlate SignNow helps you fill in and sign documents in minutes, error-free. Choose the correct version of the editable PDF form from the list and get started filling it out.
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| NY IT-2106 2025 | 4.7 Satisfied (92 Votes) | |
| NY IT-2106 2024 | 4.7 Satisfied (126 Votes) | |
| NY IT-2106 2022 | 4.8 Satisfied (1334 Votes) | |
| NY IT-2106 2021 | 4.8 Satisfied (4620 Votes) |
Risks of inaccurate voucher handling
Fiduciary information
Payment amount
Signature evidence
Record retention
Privacy and disclosure pitfalls
The voucher may expose fiduciary names, taxpayer identification details, addresses, and payment amounts when shared by email or downloaded without access controls. A signer may approve an estimated payment without reviewing the tax year, fiduciary identity, or amount against the supporting fiduciary return. Consumer-facing workflows may require an electronic-record disclosure and proof that the signer can access and retain the voucher. Broad workspace permissions can allow unauthorized users to view, change, or download fiduciary payment records and completion certificates.
Best practices for voucher records
Accuracy checks, controlled access, audit-trail export, and rule-based retention help preserve this fiduciary payment record.
Verify every voucher field
Export the audit evidence
Apply the correct retention period
Restrict access to records
Security for fiduciary tax records
Transport encryption:
Stored document security:
Control assurance:
Security management:
Electronic signatures:
Protected information:


Key performance indicators that demonstrate SignNow's proven track record.
Troubleshooting fiduciary voucher workflows
These answers address field detection, signer authorization, electronic-record consent, plan selection, and retention for this fiduciary payment voucher.
Upload the voucher as a PDF, then use signNow field detection to identify editable areas. Verify that fiduciary identity, tax year, payment amount, and signature fields are mapped correctly before sending. Detection does not validate tax calculations or determine whether the voucher belongs with a particular return.
Use signNow’s Business plan for legally binding eSignatures, templates, mobile apps, and audit trails at $8 per user per month when billed annually. The plan includes 100 signature invites per user annually; additional invite charges may apply, so review usage before routing multiple vouchers.
An email link can establish delivery, but stronger signer attribution may require SMS OTP or another enabled authentication method. Configure the appropriate control, preserve the completion certificate, and confirm intent, consent, attribution, and reproducible record retention under ESIGN and UETA.
For a consumer-facing electronic record, provide the ESIGN disclosure describing the right to paper records, electronic access, and consent withdrawal procedures under 15 U.S.C. §7001(c). Keep the disclosure and completed voucher together so consent evidence remains available with the tax record.
The voucher’s payment amount should come from the fiduciary’s supporting tax calculation, not from signNow. Correct the source document or prepare a new version, then route the revised voucher for signature and retain the superseded version according to policy.
After completion, download the signed voucher and certificate of completion from signNow, restrict workspace permissions, and apply the relevant retention rule. IRS records generally use three years from filing under IRC §6501(a), with longer periods for specified circumstances.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.