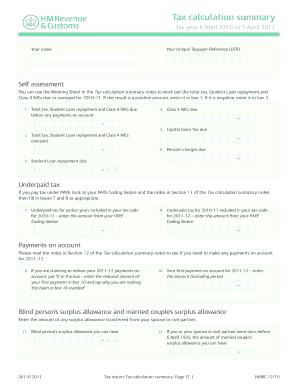
SA110 2011
Use a Sa110 2011 template to make your document workflow more streamlined.
What SA110 2011 is and does
SA110 2011 is a named form that can be prepared as an electronic document and routed for signature through signNow. The available workflow is practical: upload the file, let the editor detect fillable areas, add or correct fields, identify the signer, and send it for completion. signNow records signing events in an audit trail and provides a completed copy for storage. The form’s issuing instructions, required fields, filing destination, and deadline must be confirmed from the authoritative SA110 2011 instructions before submission.
Who uses SA110 2011
Tax and finance teams
Businesses and advisers can use signNow to route SA110 2011 for review, complete form fields, collect signatures, and preserve an audit trail with the final electronic record.
Small business filers
Small businesses can prepare SA110 2011 from a reusable signNow template, send it to an authorized signer, and retain the completed copy without paper handling.
How to complete SA110 2011
Use this signNow sequence to prepare, route, complete, and preserve SA110 2011 as an electronic record.
Upload form:
Upload the SA110 2011 PDF to signNow. Check fields:
Review detected fields and add missing fields. Send form:
Add the authorized signer and send the form. Store record:
Review the signed copy and export its audit trail.
Recommended SA110 2011 workflow setup
Configure authentication, signatures, audit evidence, retention, and encryption before sending SA110 2011 to its intended signer.
| Setting | Recommendation |
|---|---|
| Authentication method | Email link with SMS OTP |
| Signature type | Typed or drawn eSignature |
| Audit trail | Export with completed SA110 2011 |
| Document retention | Three years from filing under IRC §6501(a) |
| Encryption | TLS 1.2/1.3 and AES-256 |
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Inside the SA110 2011 audit trail
The audit trail documents what happened to SA110 2011 during signing, providing a separate evidence record from the visible completed form.
Authenticate signer:
Capture timestamp:
Record document history:
Seal evidence:
Retrieve records:
Archive exports:
Find and fill out the correct sa110
airSlate SignNow helps you fill in and sign documents in minutes, error-free. Choose the correct version of the editable PDF form from the list and get started filling it out.
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| UK HMRC SA110 2025 | 4.5 Satisfied (26 Votes) | |
| UK HMRC SA110 2011 | 4.6 Satisfied (60 Votes) |
SA110 2011 retention schedule
Retention depends on the underlying record and authority. Use the federal periods below only where SA110 2011 forms part of that documented tax record.
Three years from filing
Six years for major understatement
Indefinite for fraud or omission
State period if longer
Full governing period
Record-keeping practices for SA110 2011
Preserve SA110 2011 with its audit evidence, access controls, and the retention rule that actually governs your underlying transaction.
Confirm the applicable retention period
Export the audit trail with the form
Archive the completed record securely
Document your organization’s retention policy
SA110 2011 compliance risks
Missing required field
Unclear signer identity
Audit trail unavailable
Uncontrolled document access
SA110 2011 completion challenges
A scanned SA110 2011 may require manual field placement when the PDF lacks an interactive form layer. A signer may complete the signature field but leave a required date, checkbox, or identification field blank. Sending the document without confirming the authoritative SA110 2011 instructions can produce an incorrect filing destination or deadline. Keeping only the signed PDF, without its signNow audit trail, weakens the evidence supporting signer attribution and document history.
SA110 2011 troubleshooting questions
Use these answers to resolve signing, field-detection, authentication, plan, and record-retention questions for SA110 2011 in signNow.
If the uploaded SA110 2011 file has no detected fields, open it in signNow’s editor and add text, date, checkbox, and signature fields manually. The Business plan supports templates and audit trails, while Business Premium adds bulk send for repeated form workflows.
signNow’s Business plan includes legally binding eSignatures and audit trails. Before sending SA110 2011, confirm the signer’s intent and electronic consent, especially for consumer-facing transactions covered by the ESIGN Act, 15 U.S.C. §7001(c).
Use signNow’s SMS authentication or stronger signer-authentication options where identity risk requires it. A typed or drawn signature can satisfy ESIGN and UETA when intent, attribution, consent, and record retention are documented.
The Business plan includes 100 signature invites per user annually, with overage fees. Business Premium includes bulk send, while the Site License uses $1.50 per signature invite and is intended for high-volume document workflows.
Export the completed SA110 2011 and its certificate of completion from signNow, then store both under your organization’s retention policy. The audit trail records signing activity, timestamps, and related events for evidentiary review.
If a required SA110 2011 field is incomplete, void or correct the document before relying on it. Keep the original record, completed version, and audit trail together; ESIGN requires electronic records to remain accessible and reproducible.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.