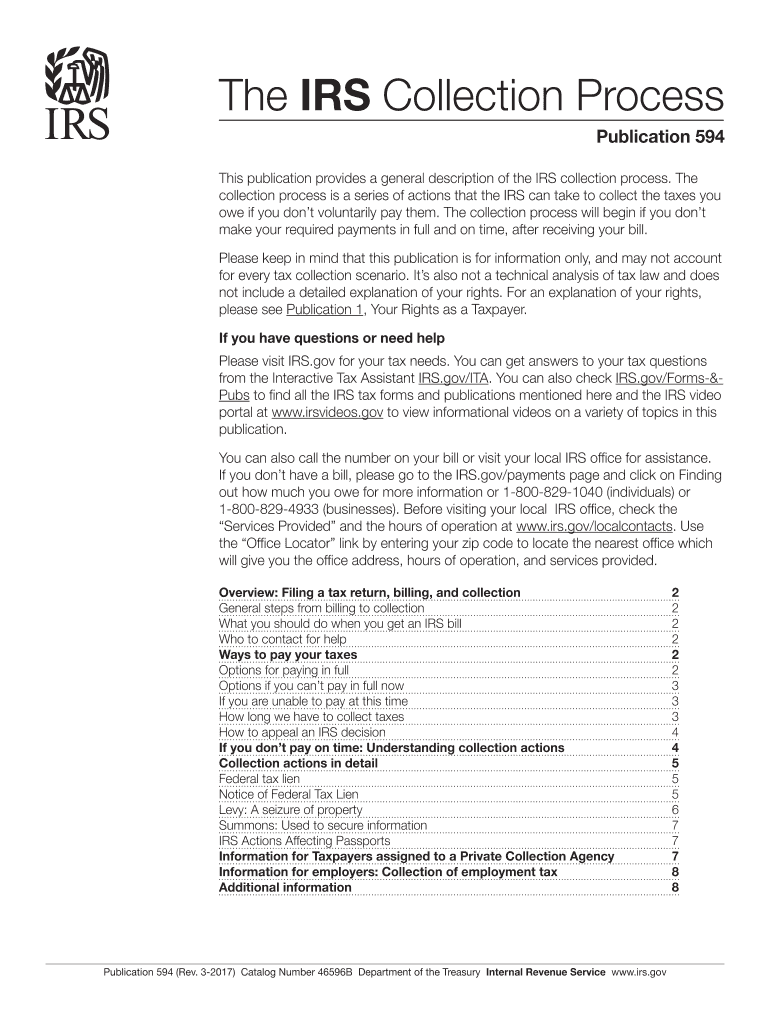
IRS Publication 594 Form
Use a Irs Publication 594 Form 2017 template to make your document workflow more streamlined.
What IRS Publication 594 actually is
IRS Publication 594 is an IRS guide to the federal tax collection process, not a taxpayer return or standalone filing form. It explains how the IRS collects unpaid taxes, including notices, payment options, liens, levies, and taxpayer rights. The publication helps readers understand collection activity and available responses, but it does not itself create a payment plan, discharge a liability, or replace an IRS notice. Use the current IRS source for operative deadlines and instructions, and use signNow only to distribute, acknowledge, or archive related records when appropriate.
Business users of IRS Publication 594
IRS Publication 594 explains the federal collection process, so users should distribute it as reference material rather than treat it as a substitute for an IRS filing form.
Solo tax practitioners can prepare client-facing copies of IRS Publication 594, capture acknowledgments, and retain the related correspondence in one organized electronic record. Accounting firms can route IRS collection-process materials to clients for review, using reusable signNow templates and delegated sending without changing the publication’s official IRS content. Enterprise finance teams can standardize distribution of IRS Publication 594 across departments, preserving access controls and audit trails while directing tax questions to the IRS or qualified advisers.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
How to handle IRS Publication 594
The workflow should distinguish distributing IRS guidance from submitting a legally operative IRS form or response.
Confirm the document: Confirm the IRS source and document purpose before creating a signNow workflow. Prepare the copy: Upload the publication and review any detected fields or annotations manually. Add acknowledgment: Add acknowledgment fields only when recipients must confirm receipt or review. Archive the record: Send the controlled copy, capture responses, and preserve the completed audit trail.
Steps for preparing IRS Publication 594
Use these steps when the publication is being distributed for review or acknowledgment rather than filed as an IRS return.
Confirm source:
Verify the current IRS Publication 594 source copy. Upload copy:
Upload the document to signNow. Review fields:
Review auto-detected fields and add only needed acknowledgments. Send document:
Send the copy to authorized recipients. Archive evidence:
Export the completed record and audit trail.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
What the audit trail records
For IRS Publication 594, the audit trail documents handling of the publication copy; it does not certify an IRS filing or collection outcome.
Signer authentication:
Timestamp capture:
Document integrity:
Tamper-evident sealing:
Activity history:
Audit-trail export:
Processing IRS Publication 594 Form
Use a controlled workflow to prepare, distribute, review, and archive materials associated with IRS Publication 594 Form.
Document preparation
Delivery to signers
Signer turnaround
Completion and archival
Find and fill out the correct irs publication 594 2017 form
airSlate SignNow helps you fill in and sign documents in minutes, error-free. Choose the correct version of the editable PDF form from the list and get started filling it out.
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| IRS Publication 594 2024 | 4.8 Satisfied (89 Votes) | |
| IRS Publication 594 2018 | 4.8 Satisfied (4951 Votes) | |
| IRS Publication 594 2017 | 4.6 Satisfied (206 Votes) | |
| IRS Publication 594 2015 | 4.8 Satisfied (184 Votes) |
Best practices for IRS Publication 594
Accurate handling starts by distinguishing this IRS explanatory publication from a return, notice, payment arrangement, or other legally operative tax document.
Identify the publication before sending
Keep IRS content unchanged
Separate acknowledgment from filing
Archive records with authority
Challenges when handling IRS Publication 594
Treating IRS Publication 594 as a filing form can lead to missing the separate IRS notice, return, or payment instructions that actually govern the taxpayer’s case. Adding a signature field without a documented acknowledgment purpose can falsely suggest that signing the publication changes collection status or establishes an IRS-approved arrangement. Sending an outdated publication without checking the current IRS source can leave recipients relying on explanations that no longer reflect current collection procedures. Storing the publication without its related notice, correspondence, or audit trail can make the organization’s record incomplete during a tax-document review.
Security for IRS Publication 594 records
Data in transit:
Data at rest:
Service assurance:
Security management:
Electronic signatures:
Protected health data:
Recommended workflow setup
Configure the workflow to preserve IRS Publication 594 as reference material and distinguish acknowledgments from official tax filings.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification with SMS OTP |
| Signature type | Acknowledgment signature only |
| Audit trail | Enable completion history and export |
| Document retention | Apply IRC §6501(a) policy review |
| Encryption | Use TLS 1.2/1.3 and AES-256 |



Key performance indicators that demonstrate SignNow's proven track record.
IRS Publication 594 troubleshooting
These answers separate IRS collection guidance from the signNow workflow used to distribute, acknowledge, and preserve related records.
IRS Publication 594 is explanatory guidance, not itself a tax return or payment agreement. Use signNow to distribute or acknowledge it, then follow the separate IRS notice and instructions controlling the taxpayer’s case.
Upload the source PDF, inspect signNow’s detected fields, and remove any unintended signature or date fields. Publication 594 should not be altered to imply an IRS filing or approval.
The Business plan includes templates, audit trails, and mobile apps at $8 per user per month when billed annually. Business Premium adds bulk send at $15 per user per month annually.
Use signNow’s audit trail to document delivery, acknowledgment, timestamps, and signer actions. That record supports process evidence, but it does not replace IRS records or determine the applicable tax deadline.
For consumer-facing electronic records, ESIGN requires disclosure of the right to paper, electronic-access capability, and withdrawal procedures under 15 U.S.C. §7001(c). Obtain appropriate consent before electronic delivery.
If the publication accompanies personal tax information, restrict recipients and permissions, preserve the source copy, and export the completed audit trail. Consult the IRS or a tax professional for case-specific collection rights.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.