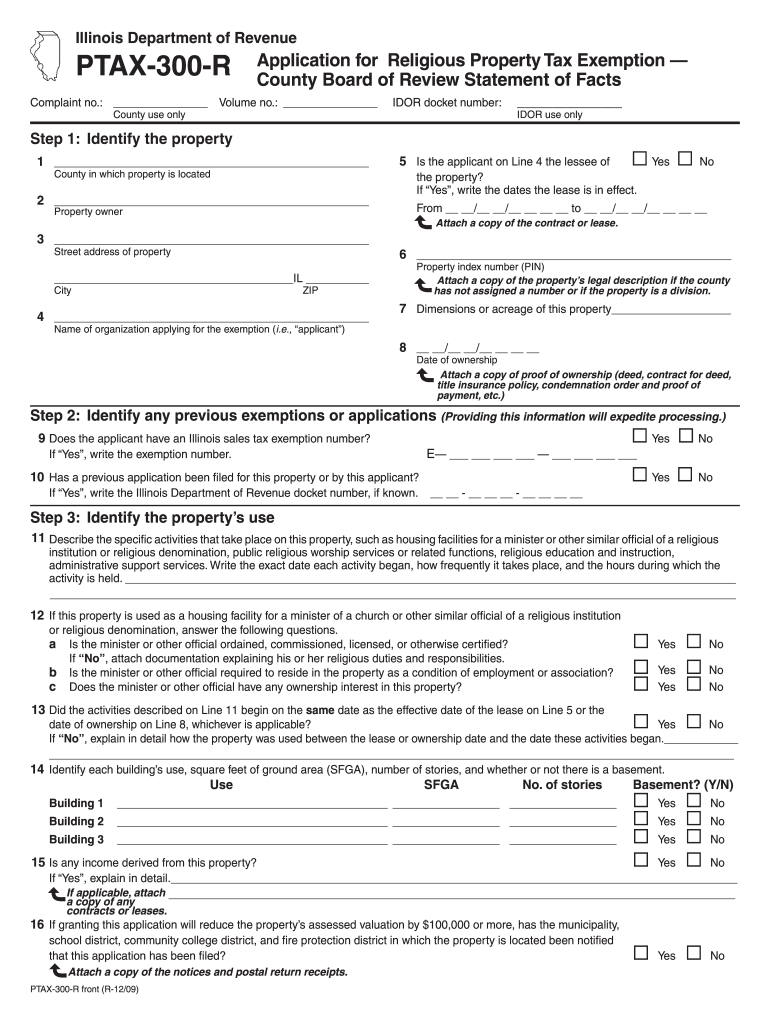
Ptax 300 R Form (2009)
Use a Ptax 300 R Form 2009 template to make your document workflow more streamlined.
What the Ptax 300 R form does
The Ptax 300 R Form (2009) is a dated tax-related record that must be completed from its original instructions and submitted or retained according to the responsible jurisdiction’s requirements. Its exact fields, reviewing authority, and filing treatment depend on the transaction for which it is used, so users should not substitute a newer edition or infer filing rules from the form name alone. signNow can upload the document, identify fillable areas, route it to authorized signers, capture an audit trail, and preserve the executed copy.
Legal standing for business records
A completed Ptax 300 R Form (2009) may be admissible when the parties show intent, consent, signer attribution, and reliable record retention under ESIGN and applicable UETA provisions. Electronic treatment does not extend to wills, testamentary trusts, court orders, official court filings, or covered family-law decrees.

Who benefits from this form workflow
The Ptax 300 R Form (2009) is most useful when an organization must preserve an exact historical edition, obtain accountable signatures, and maintain a reproducible record.
A tax professional or financial-services team can use the Ptax 300 R Form (2009) as a controlled client-document workflow, preserving the exact 2009 edition, signer identity, completed PDF, and audit trail instead of exchanging disconnected attachments by email. A property or business office can route the form to an authorized representative, collect required signatures remotely, and retain the completed record with supporting correspondence. signNow’s templates and audit trails help separate reusable document structure from transaction-specific entries. An enterprise records team can standardize access and retention for multiple offices handling the Ptax 300 R Form (2009). Administrators can use shared templates, controlled sending permissions, and exported audit trails while local staff complete only assigned fields.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
Who uses the Ptax 300 R form
Tax and accounting
Tax professionals and accounting teams use signNow to circulate the Ptax 300 R Form (2009), gather authorized signatures, and preserve the signed PDF with its audit trail. The workflow is useful when a historical form edition must remain unchanged while transaction-specific values are completed and reviewed before filing or delivery.
Business offices
Business and property offices use the form workflow for authorized representatives, counterparties, and internal reviewers. signNow can route the document in order, capture completion evidence, and retain the final record, but the responsible agency’s instructions still determine whether additional submission, notarization, or paper delivery is required.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Complete the Ptax 300 R form
Use the original 2009 form, verify every jurisdiction-specific instruction, and preserve the completed document with its signing history.
Upload the form:
Upload the original form to preserve its layout and instructions. Check fields:
Review detected fields and add missing signer, date, or text fields. Send for signing:
Enter recipient details and send the prepared form for completion. Store records:
Download the completed record and retain its audit trail securely.
Recommended Ptax 300 R form setup
Configure the Ptax 300 R Form (2009) workflow around signer attribution, audit evidence, controlled access, and the retention rule applicable to the transaction.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification with SMS OTP |
| Signature type | Electronic signature with signer intent |
| Audit trail | Export with the completed PDF |
| Document retention | Apply IRC §6501(a) or applicable state rule |
| Access and encryption | Role-based access with encrypted storage |
Find and fill out the correct ptax 300 r 2009 form
airSlate SignNow helps you fill in and sign documents in minutes, error-free. Choose the correct version of the editable PDF form from the list and get started filling it out.
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| 2009 IL DoR PTAX-300-R [2009-12] 2017 | 4.8 Satisfied (14581 Votes) | |
| 2009 IL DoR PTAX-300-R [2009-12] 2009 | 4.7 Satisfied (1292 Votes) |
How the audit trail supports this form
The audit trail separates the Ptax 300 R Form (2009) signing evidence from the form’s substantive tax or filing instructions.
Authenticate signer:
Capture timestamps:
Hash document:
Seal record:
Review history:
Export evidence:
Ptax 300 R form retention schedule
Retention depends on the filing circumstances and applicable jurisdiction. Apply the federal periods below, then confirm any longer state requirement.
Three years after filing
Six years after filing
Indefinitely for fraudulent returns
Indefinitely without a return
State periods may be longer
State rules and document exclusions
Notarization required
Real-estate deed
Wills and codicils
Court orders
Privacy and disclosure pitfalls
The completed Ptax 300 R Form (2009) may contain financial or identifying information; sending it to an unintended recipient can expose data beyond the transaction’s authorized participants. A signer may complete fields without receiving the ESIGN consumer disclosure, creating a consent and access issue for a consumer-facing electronic transaction. Shared templates can expose prior transaction data if staff fail to remove old names, addresses, amounts, or attachments before preparing a new Ptax 300 R Form (2009). Broad workspace permissions can allow unauthorized users to download the completed form or audit trail, weakening access control over the retained record.
Record-keeping practices for the Ptax 300 R form
Accurate completion and defensible retention require preserving the original form, signed copy, audit trail, and applicable federal or state retention rule together.
Verify the 2009 form edition
Export the signed record and audit trail
Match retention to the tax rule
Archive securely and review state rules
Ptax 300 R form troubleshooting
These answers address field detection, signer identity, consumer disclosures, plan limits, excluded documents, and retention for the Ptax 300 R Form (2009).
Upload the original Ptax 300 R Form (2009) as a PDF, then inspect signNow’s detected fields. Add text, date, initials, and signature fields manually when the scan does not expose usable form controls. Field detection does not validate tax or jurisdictional requirements.
The Business plan includes legally binding eSignatures, templates, and audit trails at $8 per user per month with annual billing. It includes 100 signature invites per user per year; additional usage can create overage fees, so review volume before sending repeatedly.
Use signNow’s signer authentication options, including SMS codes where configured, and retain the audit trail. ESIGN and UETA focus on intent, consent, attribution, and reproducible records; authentication strength should match the sensitivity of the Ptax 300 R transaction.
For a consumer-facing transaction, provide the ESIGN consumer disclosure and confirm the signer can access the electronic record. The disclosure must address the right to paper records and withdrawal procedures under 15 U.S.C. §7001(c).
A signature workflow does not authorize excluded documents. Wills, codicils, testamentary trusts, court orders, official court filings, and specified family-law decrees remain outside ESIGN’s ordinary electronic-record treatment and require the applicable state or court process.
After completion, download the signed Ptax 300 R Form (2009) and its audit trail from signNow, restrict access, and apply the relevant IRC §6501 period. Confirm state rules separately because state retention requirements can exceed federal requirements.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.