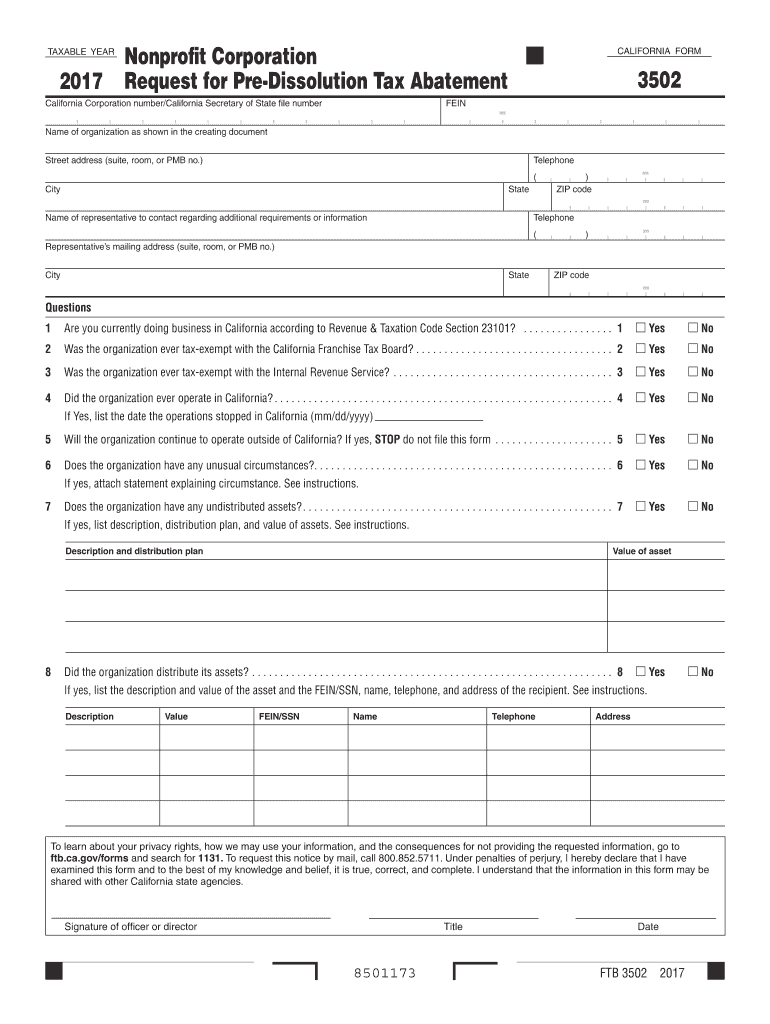
Request For Pre Dissolution Tax Abatement
Use a Request For Pre Dissolution Tax Abatement 2017 template to make your document workflow more streamlined.
What this tax abatement request does
A Request For Pre Dissolution Tax Abatement is a written request asking the responsible U.S. tax authority to reduce, waive, or otherwise address a tax liability before a business dissolves. The request generally identifies the taxpayer, entity, tax period, assessed amount, requested relief, and supporting explanation. Because the supplied form name does not identify an issuing agency, jurisdiction, filing deadline, eligibility test, or official field list, confirm those requirements with the relevant state tax department, IRS office, or legal adviser before signing. signNow can route the completed document for electronic signatures and preserve its audit trail.
Who uses this abatement request
Dissolving businesses
A dissolving business or its authorized representative can use the request to present entity information, tax-period details, assessed liability, requested relief, and supporting records to the responsible tax authority. The authority and filing route must be confirmed before submission.
Tax and legal advisers
Tax professionals and attorneys can coordinate preparation and signatures when the entity’s records require review. They should verify state or federal jurisdiction, authorization, attachments, and any paper, notarization, or agency-specific submission requirement before relying on an electronic copy.
How the request moves through signNow
The signNow workflow turns the completed tax request into a controlled signing package without deciding whether the requested abatement is legally available.
Upload form: Upload the Request For Pre Dissolution Tax Abatement file to signNow. Check fields: Review auto-detected fields and add missing tax information fields. Send request: Assign authorized signers and send the request in order. Archive record: Complete signatures, then store the signed file and audit trail.
Steps to complete this request
Prepare the tax facts first, then use signNow to route the request and preserve a complete signing record.
Upload documents:
Upload the completed request and supporting documents. Review fields:
Check detected fields against the original form. Assign signers:
Add authorized recipients and signature fields. Complete request:
Send, sign, and download the completed record.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Recommended setup for the tax request
Configure the request around signer identity, document integrity, controlled access, and the retention policy required by the responsible tax authority.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification with SMS OTP |
| Signature type | Electronic signature with recorded intent |
| Audit trail | Certificate of completion and action log |
| Retention and encryption | Retain under tax policy; AES-256 at rest |
| User provisioning | Admin-managed roles and shared templates |
How the audit trail supports this request
The audit trail records who handled the abatement request, what happened, and when, creating a reviewable signing history separate from the request’s tax analysis.
Authenticate signer:
Capture timestamps:
Hash document:
Seal record:
Store evidence:
Export trail:
Find and fill out the correct 2017 request for pre dissolution tax abatement
airSlate SignNow helps you fill in and sign documents in minutes, error-free. Choose the correct version of the editable PDF form from the list and get started filling it out.
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| 2017 CA FTB 3502 [2017] 2024 | 4.7 Satisfied (38 Votes) | |
| 2017 CA FTB 3502 [2017] 2022 | 4.8 Satisfied (120 Votes) | |
| 2017 CA FTB 3502 [2017] 2021 | 4.8 Satisfied (4116 Votes) | |
| 2017 CA FTB 3502 [2017] 2020 | 4.6 Satisfied (577 Votes) | |
| 2017 CA FTB 3502 [2017] 2019 | 4.8 Satisfied (868 Votes) | |
| 2017 CA FTB 3502 [2017] 2017 | 4.8 Satisfied (196 Votes) |
Retention periods for related tax records
Retention depends on the tax authority, filing facts, and any applicable state rule; the form name alone does not establish one universal period.
Three years from filing
Six years for understatement
Authority-specific retention period
Longer state period
Indefinite fraud exception
Signer authentication and certificates
PKI support:
X.509 certificates:
Two-factor authentication:
SMS OTP:
ID verification:
Email authentication:
Pitfalls when preparing the request
Entering an incorrect entity name or tax account number can prevent the responsible authority from matching the request to its records. Requesting relief without identifying the tax period, assessed liability, or supporting reason leaves the reviewer without a defined abatement basis. Sending the document to an unauthorized signer can weaken attribution and delay acceptance of the dissolution-related tax request. Sharing the completed request without access controls can expose tax identifiers, financial details, and dissolution information to unintended recipients.
Best practices for preparing the request
Accuracy depends on matching the request to the responsible authority, the entity’s dissolution facts, and its supporting tax records.
Confirm the governing tax authority
Match fields to supporting records
Review fields before sending
Archive the signed evidence
Key performance indicators that demonstrate SignNow's proven track record.
Troubleshooting this tax request
These answers separate signNow workflow questions from agency-specific tax requirements that must be confirmed before filing.
The supplied form name does not identify a state or federal agency. Confirm the destination with the responsible tax authority before sending. signNow can route and audit the document, but it does not determine jurisdiction or eligibility.
Upload the original file again and inspect signNow’s detected fields before sending. Add missing fields manually, compare every value with the source document, and confirm that each signer has the correct role and email address.
Business includes legally binding electronic signatures, templates, and audit trails at $8/user/month when billed annually. The plan includes 100 signature invites per user annually, with overage fees applying after the included amount.
Business Premium adds bulk send at $15/user/month billed annually. It may fit repeated abatement requests, but the supplied form information does not establish that multiple recipients or documents are required.
signNow states that ESIGN and UETA compliance is available. Under 15 U.S.C. ch. 96 and applicable state law, preserve signer intent, consent, attribution, and a reproducible record; confirm any agency-specific paper rule separately.
Export the completed document and certificate of completion, then store them with the tax file. Apply the responsible authority’s retention rule; IRC §6501(a) is relevant to federal assessment periods, not a universal retention command for every request.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.