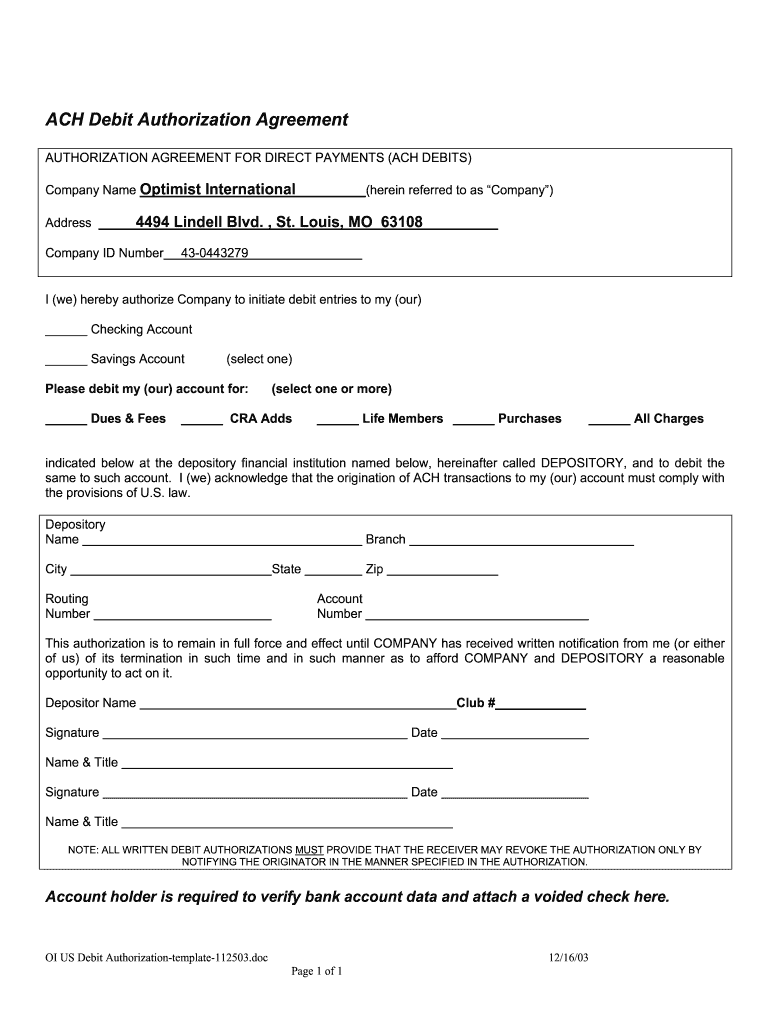
Ach Debit Authorization Agreement Form
Use a Ach Debit Authorization Agreement Form 2003 template to make your document workflow more streamlined.
What an ACH authorization agreement does
An Ach Debit Authorization Agreement Form gives a business permission to withdraw funds from a customer’s bank account under stated terms. The signer normally provides account-holder information, routing and account numbers, debit frequency, effective dates, amount limits, and authorization language. The business uses the signed record to support recurring or one-time ACH activity and to respond to payment disputes. With signNow, the sender uploads the form, checks fillable fields, routes it to the signer, and retains the completed agreement with its audit trail.
Who uses an ACH authorization agreement
Payment operations
Businesses collecting recurring customer payments use the form to record account details, debit frequency, effective dates, and authorization terms before initiating ACH transactions.
Account holders
Customers and account holders review the debit terms, provide bank information, and sign electronically when the organization offers compliant electronic-record consent.
Complete the ACH authorization agreement
Use signNow to prepare the agreement, capture authorization, and preserve the completed document with evidence of each signing event.
Upload form:
Upload the ACH authorization agreement to signNow. Check fields:
Review detected fields and add missing account or signature fields. Send request:
Enter signer details and send the agreement for completion. Store record:
Review the signed agreement, certificate, and audit trail.
How the Ach authorization audit trail works
The audit trail records who authorized ACH debits, when each event occurred, and how the completed agreement remained protected afterward.
Signer authentication:
Timestamp capture:
Document hashing:
Tamper-evident sealing:
Event history:
Audit export:
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Recommended ACH authorization setup
Configure the ACH authorization workflow around signer identity, electronic consent, audit evidence, retention, and controlled access for payment operations.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification with SMS OTP for higher assurance |
| Signature type | Typed or drawn electronic signature with signer intent |
| Audit trail | Retain completion certificate and detailed event history |
| Document retention | Three years from filing for IRS records (IRC §6501(a)) |
| Encryption | TLS 1.2 or 1.3 in transit and AES-256 at rest |
Security for ACH authorization records
Transport security:
Stored data:
Security reporting:
Security certification:
Electronic signatures:
Health information:
Find and fill out the correct ach debit authorization agreement form
airSlate SignNow helps you fill in and sign documents in minutes, error-free. Choose the correct version of the editable PDF form from the list and get started filling it out.
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| *2003 ACH Debit Authorization Agreement [2003-12-16] 2003 | 4.8 Satisfied (12840 Votes) |



Legal standing of ACH authorization
A signed ACH authorization can provide evidence of intent, consent, and transaction terms when the record identifies the signer and remains reproducible. ESIGN, 15 U.S.C. ch. 96, and UETA generally recognize qualifying electronic signatures, but ACH rules, consumer disclosures, and state requirements still apply.

Record-keeping practices for ACH authorizations
Keep each signed ACH authorization connected to its audit trail, transaction context, and applicable U.S. retention rule.
Set retention by record type
Export the signed record
Protect archived authorizations
Control authorization changes
Risks of incomplete ACH authorization
Unauthorized debit dispute
Payment processing failure
Weaker dispute response
Invalid recurring debit
Challenges when completing ACH authorization forms
Bank routing and account numbers can be entered incorrectly, causing rejected debits or requiring a corrected authorization before processing. A signer may approve recurring withdrawals without clearly reviewing amount limits, frequency, effective dates, or cancellation instructions. Organizations may retain the signed agreement but lose the audit trail, making signer identity and authorization timing harder to establish. Consumer-facing workflows may omit electronic-record disclosures required by ESIGN before the signer consents to electronic delivery.
ACH authorization troubleshooting and FAQs
Resolve field, signer, disclosure, retention, and plan questions before relying on an electronically signed ACH authorization agreement.
Upload the original ACH agreement again, then review signNow’s detected fields before sending. Add explicit fields for account-holder name, routing number, account number, authorization date, debit terms, and signature so the signer cannot overlook required information.
The Business plan includes legally binding eSignatures, templates, audit trails, and mobile apps at $8/user/month when billed annually. Business Premium adds bulk send at $15/user/month, while Enterprise adds advanced signer authentication at $30/user/month.
Use signNow’s SMS one-time password or another available authentication control when email-only evidence is insufficient. Stronger authentication supports attribution, but the agreement should still state authorization terms clearly and preserve the audit trail.
For a consumer-facing electronic record, provide the ESIGN disclosure required by 15 U.S.C. §7001(c), including paper-record access, electronic access, and consent-withdrawal procedures. Obtain consent before relying on electronic delivery of the agreement.
Export the completed ACH agreement and certificate of completion from signNow, then preserve the event history with the transaction record. For federal tax records, IRC §6501(a) generally provides a three-year baseline from filing, subject to exceptions.
signNow supports ESIGN and UETA electronic signatures, but those laws do not replace ACH network, bank, consumer-protection, or state requirements. Confirm the debit authorization language and processing rules applicable to your payment program.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.