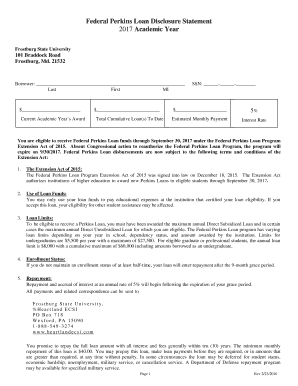
Initial Mortgage Disclosure Statement
Use a Initial Mortgage Disclosure Statement Pdf 2017 template to make your document workflow more streamlined.
What an initial mortgage disclosure statement covers
An Initial Mortgage Disclosure Statement is a lender-provided document that explains the estimated terms, costs, and conditions of a proposed mortgage before closing. It helps applicants review the loan amount, interest rate, projected payments, estimated closing costs, and other transaction details. The lender prepares the disclosure from the application and loan scenario, then delivers it for review and any required acknowledgment. With signNow, a lender can upload the statement, detect fillable fields, route it to the borrower, capture an electronic signature, and retain the completed record with its audit trail.
Who uses this mortgage disclosure
Mortgage lenders
Mortgage lenders and loan officers use the statement to present estimated loan terms, projected payments, and settlement charges for borrower review. Operations staff can prepare fields, route the document to applicants and co-borrowers, and preserve the signed version with transaction evidence.
Borrowers
Borrowers and co-borrowers review the loan-specific figures before acknowledging the disclosure. A controlled electronic workflow helps them access the same statement remotely, complete assigned fields, and receive a copy suitable for their records.
How the disclosure workflow works
A lender can move the Initial Mortgage Disclosure Statement from preparation through signed archival in four controlled stages.
Upload document: Upload the lender-prepared disclosure and inspect detected fields. Assign fields: Confirm borrower, lender, and loan-specific field assignments. Request signature: Send the statement for review and electronic acknowledgment. Archive record: Store the signed statement with its audit trail.
What the audit trail records
The audit trail supplies transaction evidence around the Initial Mortgage Disclosure Statement, separate from preparing fields or assigning signers.
Authenticate signer:
Capture timestamp:
Hash document:
Seal history:
Track delivery:
Export evidence:
Recommended disclosure workflow setup
Configure the Initial Mortgage Disclosure Statement workflow around verified signer identity, electronic consent, evidence capture, and controlled record storage.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification with SMS OTP |
| Signature type | Electronic acknowledgment under ESIGN and UETA |
| Audit trail | Capture timestamps, IP address, and signer actions |
| Document retention | Apply lender policy and applicable state requirements |
| Encryption | TLS 1.2/1.3 and AES-256 at rest |
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Best practices for mortgage disclosures
Accurate field mapping, informed consent, and controlled retention reduce errors when preparing this borrower-facing loan disclosure.
Verify every loan-specific disclosure value
Assign fields to each responsible signer
Document consent and preserve evidence
Control access and template reuse
Challenges when preparing the statement
Transcribing loan terms into the Initial Mortgage Disclosure Statement can create mismatches between the disclosure, underwriting file, and borrower-facing payment estimates. Incorrect field assignment may send lender certifications or borrower acknowledgment fields to the wrong recipient, requiring cancellation and reissue of the signing request. Outdated templates can retain superseded interest rates, fees, contact information, or payment assumptions that no longer match the applicant’s current loan scenario. Incomplete audit records make it harder to show when the borrower received, reviewed, acknowledged, and retained the specific disclosure version.
Find and fill out the correct initial mortgage disclosure statement pdf
airSlate SignNow helps you fill in and sign documents in minutes, error-free. Choose the correct version of the editable PDF form from the list and get started filling it out.
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| *2017 Frostburg State University Federal Perkins Loan Disclosure Statement [2016-02-23] 2017 | 4.8 Satisfied (2404 Votes) |
Features for completing the statement
signNow connects document preparation, borrower signing, evidence capture, and controlled storage for the Initial Mortgage Disclosure Statement workflow.
Field detection
Upload the lender-approved disclosure and use detected fields to reduce manual placement errors across borrower, co-borrower, and lender sections.
Role assignment
Assign loan-specific fields and signature locations to the correct recipient before sending the statement for review and acknowledgment.
Remote delivery
Route the disclosure by email or signing link while keeping the borrower’s transaction connected to one controlled request.
Audit evidence
Capture signer actions, timestamps, delivery events, and completion evidence for the exact disclosure version presented.
Record access
Keep the completed statement and certificate of completion available for controlled retrieval by authorized mortgage staff.
Data protection
Use encryption and compliance controls to protect borrower information during transmission and storage.
Security for mortgage disclosure records
Transit protection:
Stored protection:
Control assurance:
Security certification:
Signature compliance:
Regulated workflows:
User roles for mortgage disclosures
Mortgage operations administrators can maintain a shared Initial Mortgage Disclosure Statement template, control who may edit loan fields, and monitor completed packets through centralized account controls. Delegated sending lets approved loan officers initiate borrower requests without granting broad administrative access to the entire workspace. Loan teams can separate preparation, review, and signing responsibilities through role-based permissions. A coordinator may upload and assign fields, a licensed lender representative may review the disclosure, and the borrower receives only the fields and documents required for that transaction.



Legal standing of electronic acknowledgment
An electronic acknowledgment may be admissible when the borrower demonstrates intent, consents to electronic records, can be attributed to the signer, and the lender retains an accurate reproducible record under ESIGN, 15 U.S.C. ch. 96, and applicable state law such as UETA. Wills, certain court filings, and family-law decrees remain excluded.

Troubleshooting mortgage disclosure workflows
Resolve field, consent, evidence, plan, and compliance questions before treating an electronically signed disclosure as complete.
Use signNow’s document upload and field-detection workflow, then inspect every detected field manually. The lender remains responsible for confirming loan-specific values, borrower names, property details, projected payments, and estimated charges before sending.
Verify the recipient order and field assignments in the signNow editor. Add the borrower, co-borrower, and lender representative as separate recipients when required, then send a corrected request rather than asking a recipient to sign another party’s fields.
For consumer-facing electronic records, review the ESIGN Act requirement in 15 U.S.C. §7001(c): disclose paper rights, demonstrate electronic access, and explain consent withdrawal procedures. Configure the signNow workflow to present the required notice before acknowledgment.
A completed signNow request includes signing events and an audit trail. Export the Initial Mortgage Disclosure Statement with its certificate of completion, timestamps, recipient actions, and delivery evidence, then store it under the lender’s approved retention policy.
The Business plan includes legally binding eSignatures, audit trails, templates, and mobile apps at $8/user/month when billed annually. Business Premium is $15/user/month annually and adds bulk send and kiosk mode; choose based on the lender’s workflow.
signNow reports ESIGN and UETA compliance, with TLS 1.2/1.3 encryption in transit and AES-256 encryption at rest. Compliance does not replace lender duties to verify disclosure accuracy, obtain required consent, or follow mortgage-specific retention rules.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.