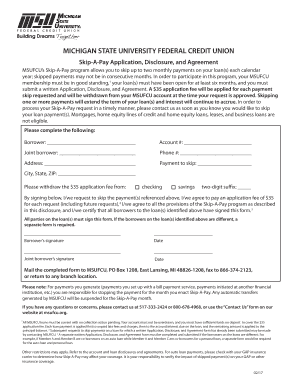
Skip A Pay Application, Disclosure, And Agreement
Use a Skip A Pay Application, Disclosure, And Agreement 2017 template to make your document workflow more streamlined.
What this Skip A Pay form does
The Skip A Pay Application, Disclosure, And Agreement is a lender-provided document used to request and document a permitted payment deferral. The applicant supplies the information required by the lender, reviews the disclosed effect on the loan or account, and agrees to the stated terms. The form does not itself establish eligibility, fees, deferred-payment treatment, or approval criteria; those details come from the lender’s program and the form’s language. With signNow, staff can upload the approved PDF, detect or place fields, route it for signature, and retain the completed record with an audit trail.
Who completes this Skip A Pay form
Lenders
Credit unions and lenders use the form to document a member’s Skip A Pay request, disclosures, eligibility information, and agreement terms.
Borrowers
Borrowers review the payment-deferral terms, provide required information, and sign the agreement electronically when permitted by the lender.
Features for this Skip A Pay workflow
signNow connects the specific application, disclosure, and agreement steps into one controlled electronic workflow for lender and borrower review.
Form preparation
Upload the lender-approved Skip A Pay PDF and place signature, date, and borrower information fields without recreating the document.
Signer routing
Route the application, disclosure, and agreement to the correct borrower and lender representative in a defined signing order.
Audit trail
Capture timestamps, IP information, and signing actions so the completed agreement has supporting transaction evidence.
Mobile signing
Let borrowers review and sign the payment-deferral document from a supported desktop or mobile workflow.
Reusable template
Save a reusable approved template after the lender reviews field placement and signing requirements.
Record export
Export the signed agreement with its completion certificate and audit trail for controlled record storage.
How this Skip A Pay form works
The workflow moves the specific application, disclosure, and agreement from preparation through signature and record storage.
Upload form: Upload the lender’s Skip A Pay form into signNow. Review fields: Auto-detect fillable fields and review required entries. Send document: Send the completed application and disclosure to signers. Store record: Store the signed agreement with its audit trail.
What the audit trail records
For this form, the audit trail connects the borrower’s review and signature to the final application, disclosure, and agreement.
Authenticate signer:
Capture timestamp:
Protect document:
Record activity:
Retrieve evidence:
Export record:
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Recommended Skip A Pay setup
Use a controlled signing workflow that connects the member’s application, disclosure, agreement, and completed record.
| Setting | Recommendation |
|---|---|
| Authentication method | Email link with SMS OTP |
| Signature type | Electronic signature with signer intent |
| Audit trail | Capture timestamps, IP address, and actions |
| Document retention | Follow lender policy and applicable state law |
| Encryption | TLS 1.2/1.3 and AES-256 protection |



Find and fill out the correct skip a pay application disclosure and agreement
airSlate SignNow helps you fill in and sign documents in minutes, error-free. Choose the correct version of the editable PDF form from the list and get started filling it out.
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| MSUFCU Skip-A-Pay Application Disclosure and Agreement 2018 | 4.8 Satisfied (3800 Votes) | |
| MSUFCU Skip-A-Pay Application Disclosure and Agreement 2017 | 4.8 Satisfied (2754 Votes) | |
| MSUFCU Skip-A-Pay Application Disclosure and Agreement 2010 | 4.8 Satisfied (2569 Votes) |
Legal standing of the signed agreement
A completed Skip A Pay Application, Disclosure, And Agreement records the borrower’s request, disclosed terms, and signing intent. For U.S. transactions, ESIGN, 15 U.S.C. ch. 96, and applicable state electronic-transactions law, including UETA or New York ESRA, can support electronic records when consent, attribution, and retention requirements are met.

Processing stages for this form
Processing time depends on field accuracy, lender review, borrower response, and the organization’s archival procedure.
Prepare the document
Deliver to signer
Review and sign
Complete and archive
Challenges when completing this form
Applicants omit loan or account information, leaving the lender unable to match the Skip A Pay request to the correct record. Disclosure language is changed without approval, creating inconsistency between the application, agreement, and the lender’s approved program terms. A missing signature or date leaves the request incomplete and may prevent processing under the lender’s internal policy. A scanned document is stored without its audit trail, weakening evidence of who reviewed and signed the agreement.
Risks of incomplete Skip A Pay records
Missing consent
Weak attribution
Incomplete disclosure
Record gap
Best practices for this agreement
A controlled process reduces incomplete applications and preserves evidence that the borrower reviewed and accepted the lender’s stated Skip A Pay terms.
Use the approved form version
Verify borrower and loan details
Preserve the complete record
Test the signing workflow
Security for signed Skip A Pay records
Transit protection:
Storage protection:
Security reporting:
Security management:
Electronic records:
Signer verification:
Skip A Pay troubleshooting questions
These answers address field detection, electronic consent, plan limits, security, and record handling for this payment-deferral form.
If the Skip A Pay PDF has no detected fields, upload the lender-approved file again and place signature, date, and required text fields manually before sending. signNow templates can preserve the reviewed field layout for later applications.
A borrower can sign electronically when the lender permits electronic records and obtains required consent. ESIGN, 15 U.S.C. §7001, requires consumer disclosure and access procedures for covered consumer records, so follow the lender’s approved consent process.
The Business plan includes legally binding eSignatures, templates, audit trails, and mobile apps at $8 per user per month with annual billing. It includes 100 signature invites per user per year; overage terms should be reviewed before volume use.
Use Business Premium when the lender needs bulk send for multiple approved recipients. The plan is $15 per user per month with annual billing and adds bulk send, kiosk mode, request payments, and quick invite links.
signNow encrypts data in transit with TLS 1.2/1.3 and at rest with AES-256. HIPAA compliance requires a business associate agreement and applies only when the workflow genuinely involves protected health information.
Download the completed document and audit trail together, then apply the lender’s retention policy and state-specific requirements. ESIGN and UETA support record reproduction, but neither sets one universal retention period for this form.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.