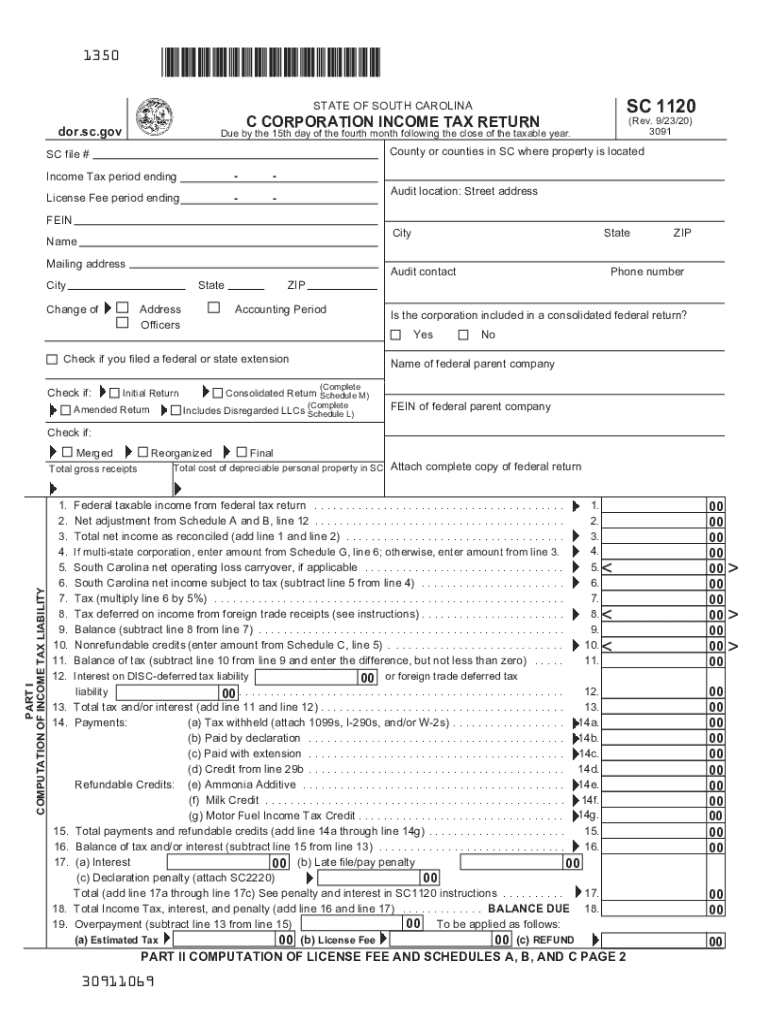
Due By The 15TH Day Of The Fourth Month Following The Close Of The Taxable Year
Use a Due By The 15th Day Of The Fourth Month Following The Close Of The Taxable Year 2020 template to make your document workflow more streamlined.
What this tax deadline means
Due By The 15TH Day Of The Fourth Month Following The Close Of The Taxable Year is a scheduling rule that places an obligation on the fifteenth day of the fourth month after a business taxable year closes. It is not, by itself, a named IRS form. A calendar-year business generally calculates from a December 31 year end, while a fiscal-year business uses its own closing date. Confirm the specific return, payment, extension, and filing instructions with the IRS because the phrase alone does not identify the required submission.
Who uses this tax deadline reference
Business finance teams
Finance teams calculate the fifteenth-day deadline from the taxable year end, collect authorized approvals, and preserve signed supporting records with related accounting workpapers.
Tax professionals
Tax professionals use the phrase as a scheduling reference, then confirm the exact return, payment, extension, and IRS submission requirements before advising the business.
How to calculate the deadline
Calculate the date from the actual taxable year end, then validate the specific filing obligation before preparing documents.
Confirm year end: Identify the taxable year end used by the business. Count four months: Count four calendar months after that closing month. Set the date: Set the target on the fifteenth day. Verify IRS instructions: Confirm the specific IRS filing and payment rules.
Complete the supporting document online
Use this sequence to prepare the specific tax-year record, obtain approval, and preserve signing evidence before the calculated deadline.
Upload document:
Upload the tax-year document to signNow. Check fields:
Review auto-detected fields and correct omissions. Assign signers:
Assign authorized signers and required dates. Complete workflow:
Send, monitor completion, and export evidence.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
How signNow records signing evidence
The audit trail documents the signing event for the tax-year record; it does not replace IRS filing, payment, or acceptance evidence.
Open the record:
Authenticate the signer:
Capture timestamps:
Seal completion evidence:
Deliver the final copy:
Export the audit trail:
Processing stages for the tax deadline
Use the calculated fifteenth-day deadline to coordinate preparation, approval, signing, and evidence storage without confusing signing with IRS filing.
Prepare the document
Send to signers
Complete signer review
Archive the evidence
Find and fill out the correct due by the 15th day of the fourth month following the close of the taxable year
airSlate SignNow helps you fill in and sign documents in minutes, error-free. Choose the correct version of the editable PDF form from the list and get started filling it out.
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| SC DoR SC1120 2022 | 4.8 Satisfied (1110 Votes) | |
| SC DoR SC1120 2020 | 4.8 Satisfied (4178 Votes) | |
| SC DoR SC1120 2019 | 4.8 Satisfied (2628 Votes) | |
| SC DoR SC1120 2018 | 4.8 Satisfied (8892 Votes) | |
| SC DoR SC1120 2017 | 4.7 Satisfied (752 Votes) | |
| SC DoR SC1120 2016 | 4.7 Satisfied (1732 Votes) |
Federal retention periods for tax records
Apply the retention period to the underlying tax record, signed evidence, and filing circumstances rather than to the deadline phrase alone.
Three years from filing
Six years for 25% understatement
Indefinite retention for fraud
Indefinite retention without filing
Longer state or industry period
Best practices for this tax deadline
Accurate date calculation, document review, and evidence retention reduce avoidable filing and approval errors.
Confirm the taxable year end before calculating
Match the deadline to the applicable IRS filing
Verify tax-year references before sending
Preserve the signed record and audit trail
Challenges when calculating the tax deadline
Businesses may confuse this phrase with a specific tax form, creating uncertainty about which return, payment, or supporting record is actually due. The fourth-month calculation depends on the taxable year’s closing date, so calendar-year and fiscal-year businesses may have different filing deadlines. Electronic signature workflows can preserve approval evidence, but they do not replace IRS filing instructions, payment procedures, or any required tax return. Late preparation can leave insufficient time to verify accounting records, obtain authorized signatures, and retain submission evidence before the calculated due date.
Risks when the deadline is mishandled
Incorrect taxable year
Missing audit trail
Unauthorized signer
State retention conflict
Troubleshooting this tax deadline workflow
Resolve date-calculation, signing, filing, and retention questions by separating signNow’s evidence workflow from the underlying IRS obligation.
signNow Business includes templates and audit trails at $8 per user per month with annual billing. Upload the tax-year record, review detected fields, assign authorized signers, and verify the final document before sending. The plan does not determine the IRS filing deadline.
No. ESIGN and UETA support electronic signature validity when intent, consent, attribution, and record retention requirements are met, but a signNow signature does not constitute IRS filing or payment. Follow the applicable IRS return instructions separately.
Check whether the taxable year ended on the date used for calculation. Count four calendar months after the closing month and use the fifteenth day of that resulting month, then confirm the applicable IRS instructions or tax professional’s advice.
Signers can review and complete assigned fields from signNow’s web or mobile apps. If a field is missing, reopen the document before sending, use auto-detected fields as a starting point, and manually confirm every tax-year, date, and signature field.
Use stronger authentication when the tax record contains sensitive financial information. signNow supports two-factor authentication options, while ESIGN and UETA focus on intent, consent, attribution, and record retention rather than requiring one universal authentication method.
Export the completed document and audit trail from signNow after signing. Retain them under IRC §6501(a): generally three years from filing, six years for an understatement exceeding 25 percent, or indefinitely for fraud or an unfiled return.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.