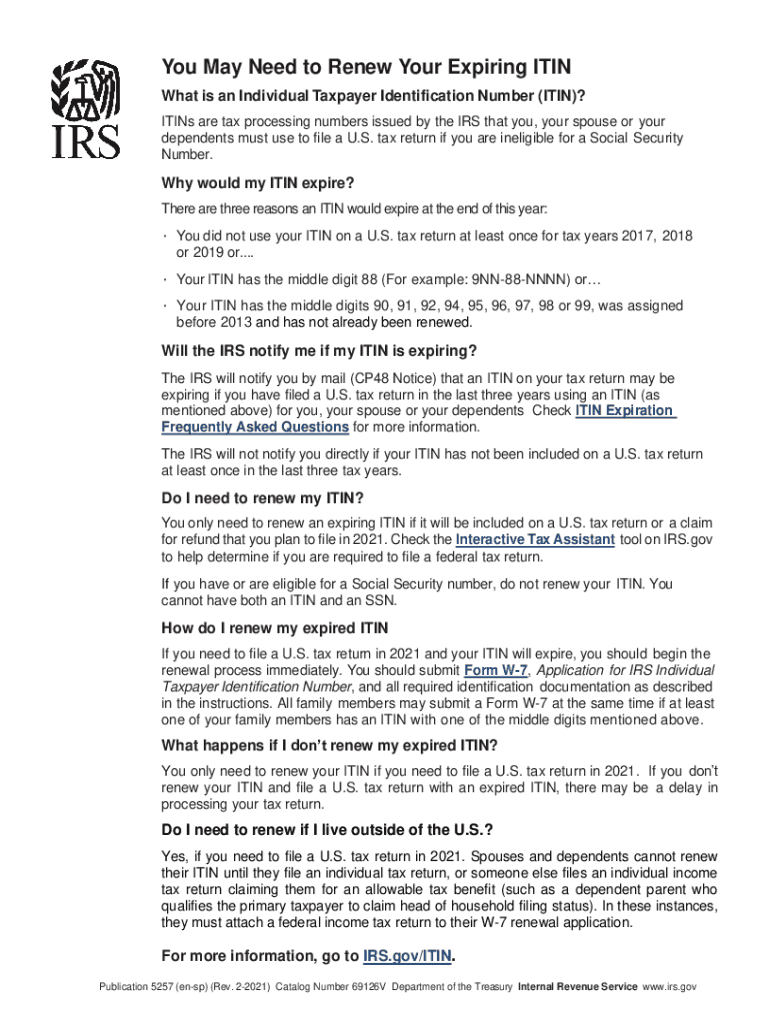
Publication 5257 En Sp Internal Revenue Service
Use a Publication 5257 en sp Internal Revenue Service 2021 template to make your document workflow more streamlined.
What Publication 5257 means
Publication 5257 En Sp Internal Revenue Service is an IRS publication identified by its English and Spanish edition label; the title alone does not establish a filing deadline, tax threshold, or signature requirement. Confirm the publication’s instructions, audience, and current revision before completing it. signNow can hold the source PDF, detect fillable fields, route designated signature fields, and preserve the completed copy with an audit trail. IRS instructions, not the eSignature platform, control whether the document must be filed, retained, or submitted through another channel.
Who benefits from this workflow
Publication 5257 workflows differ by organization, but each user should confirm the IRS publication’s intended audience and current instructions first.
Solo tax practitioners can prepare and send Publication 5257 from a reusable signNow template, then retain the signed copy and audit trail with the client file. Financial-services teams can route IRS publications through designated reviewers, using assigned fields and audit history to document who completed each required section. Enterprise tax departments can connect signNow with Microsoft 365, NetSuite, or controlled storage, standardizing publication handling across offices without changing IRS instructions.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
Useful features for Publication 5257
signNow features address the practical work of preparing, routing, signing, and retaining this IRS publication without changing the IRS instructions.
Reusable template
Upload the IRS publication once, then reuse a reviewed template for recurring internal requests. Field placement reduces repeated manual preparation while preserving the publication’s original pages.
Assigned fields
Assign signature and date fields to the responsible recipient before delivery. Clear field ownership helps prevent incomplete returns and makes the requested action visible to the signer.
Audit trail
Capture signing events, timestamps, and document history with the completed publication. The resulting evidence supports internal review under ESIGN and UETA requirements.
Flexible delivery
Route the document through email invitations or signing links. Recipients can review the exact publication before applying their signature and receiving the completed copy.
Mobile access
Use signNow mobile apps when staff prepare or review Publication 5257 away from a desk. The workflow keeps the source document and signing record connected.
Connected storage
Connect completed records with Google Drive, Box, or Microsoft 365. Storage integrations reduce duplicate downloads and help teams apply an established document-control policy.
Complete Publication 5257 online
Use this sequence to prepare the IRS publication, route its required signature fields, and preserve evidence of completion.
Upload the PDF:
Upload the current IRS publication PDF to signNow. Review detected fields:
Let signNow detect fillable fields, then review placement. Assign the signer:
Add the responsible recipient and required signature fields. Complete and retain:
Send, monitor completion, and store the signed record.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Recommended Publication 5257 setup
Configure the workflow around signer attribution, document integrity, audit evidence, and the applicable IRS retention period.
| Setting | Recommendation |
|---|---|
| Authentication method | Email invitation with SMS verification |
| Signature type | Typed or drawn electronic signature |
| Audit trail | Export completion certificate and action history |
| Document retention | Three years from filing (IRC §6501(a)) |
| Encryption | AES-256 at rest and TLS 1.2/1.3 in transit |
Inside the signNow audit trail
The audit trail records who handled Publication 5257, when actions occurred, and how the completed record can be retrieved.
Authenticate signer:
Capture timestamps:
Hash document:
Seal record:
Log actions:
Export evidence:
Find and fill out the correct publication 5257 en sp internal revenue service
airSlate SignNow helps you fill in and sign documents in minutes, error-free. Choose the correct version of the editable PDF form from the list and get started filling it out.
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| *2020 IRS Publication 5257 (EN-SP) [2020-08] 2021 | 4.8 Satisfied (2963 Votes) | |
| *2020 IRS Publication 5257 (EN-SP) [2020-08] 2020 | 4.8 Satisfied (1493 Votes) |
Security for signed records
Encrypted storage:
Encrypted transfer:
Independent controls:
Security certification:
U.S. eSignature:
Protected health data:



Record retention and audit practices
Retain the completed publication, supporting evidence, and audit history according to the applicable IRS recordkeeping rule and your organization’s policy.
Apply the applicable IRS period
Export the audit trail
Restrict sensitive records
Test secure retrieval
Retention periods for IRS records
Retention depends on the underlying tax record and circumstances; use the applicable IRS rule rather than assigning one universal period.
Three years from filing
Six years for understatement
Upon request when required
Indefinite for fraud
State rules may be longer
Risks of incomplete handling
Missing required information
Unclear signer attribution
Lost supporting records
Incorrect IRS handling
Publication 5257 troubleshooting
Use the IRS publication instructions for substantive answers, and use signNow controls for document preparation, signing evidence, and record handling.
Upload the original PDF again and verify that its page order and required fields match the IRS source. signNow Business supports document upload, field placement, templates, and audit trails; it does not validate IRS-specific instructions.
Review the recipient email, resend the invitation, or create a fresh signing link. Business includes legally binding eSignatures and audit trails; SMS authentication and stronger controls depend on the configured plan and workflow.
A typed or drawn signature can evidence intent under ESIGN and UETA when consent, attribution, and record retention requirements are met. Use signNow’s audit trail to preserve timestamps, actions, and signer evidence.
Consumer-facing electronic records require a clear paper-record disclosure, access to the electronic format, and a withdrawal process under 15 U.S.C. §7001(c). Configure the disclosure before sending if the recipient is a consumer.
Business is listed at $8/user/month with annual billing and includes 100 signature invites per user per year. Business Premium adds bulk send, while Enterprise adds advanced signer authentication; confirm current plan limits before sending.
signNow is ESIGN and UETA compliant, but the IRS controls the publication’s filing and acceptance rules. Preserve the completed PDF and audit trail, then follow the publication’s instructions for submission or delivery.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.