Treasury, IRS Issue Final Regulations On The Foreign Tax Credit
Use a Treasury, IRS Issue Final Regulations On The Foreign Tax Credit 2020 template to make your document workflow more streamlined.
What the final foreign tax credit regulations address
Treasury and the IRS issued final regulations explaining how U.S. taxpayers determine whether foreign income taxes qualify for the foreign tax credit and how those taxes are allocated and apportioned. The rules address creditability, including the net gain requirement, and coordinate the credit with deductions, sourcing, expense allocation, and related international tax provisions. Businesses use the regulations when preparing cross-border tax positions, documenting foreign levies, and evaluating credit claims. They are regulatory guidance, not a standalone taxpayer return or payment form, so the applicable tax year and transaction facts remain essential.
Business types that use the regulations
The regulations matter most where foreign taxes, cross-border income, and documented internal approval meet a U.S. tax reporting process.
Solo international tax practitioners can send a client-specific foreign-tax analysis for approval, preserve the signed conclusion, and keep review evidence with the engagement file without coordinating paper exchanges. Regional accounting firms can standardize recurring review packets for clients with overseas operations, assigning tax, partner, and client approvals while retaining an audit trail for each completed memorandum. Large multinational tax departments can connect controlled approval workflows to finance systems, separate access by entity, and preserve signed certifications supporting foreign tax credit positions across multiple jurisdictions.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
Who uses these regulations and related records
Corporate tax teams
U.S. multinational tax departments use the regulations to review foreign income taxes, coordinate creditability analyses, and preserve supporting workpapers. signNow can route internal approvals and retain signed certifications or memoranda with an audit trail, but it does not determine the tax result.
Tax advisers
International tax advisers and accounting firms apply the rules when documenting foreign levies, sourcing income, and preparing a client’s credit position. signNow supports controlled review and signature collection for engagement records; the IRS regulations and the client’s facts remain the governing authority.
How to prepare a signed tax record
Use signNow for the approval and evidence workflow around the regulations; tax professionals must still determine the correct foreign tax credit treatment.
Upload records:
Upload the final regulations summary, tax memorandum, or approval record to signNow. Add fields:
Review detected fields and add names, dates, initials, and signature fields. Route review:
Send the document to designated reviewers in the required order. Archive evidence:
Collect signatures and retain the completed record with its audit trail.
How the signed review flow works
The workflow creates evidence of review around the regulations; it does not replace the taxpayer’s technical analysis or IRS filing obligations.
Prepare document: Upload the foreign-tax record and identify each reviewer or signer. Define evidence: Place fields for factual confirmation, approval, signature, and date. Collect approvals: Send the record through the assigned review sequence. Preserve record: Store the signed PDF and audit trail with the tax workpapers.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Features for foreign tax credit records
signNow organizes the review and signature evidence surrounding foreign tax credit analyses while the IRS regulations govern the underlying tax conclusion.
Approval routing
Route a foreign-tax memorandum to tax, finance, and legal reviewers without circulating paper copies or unmanaged email attachments.
Audit trail
Capture signer identity, timestamps, and document activity so the approval record can support an organized compliance file.
Reusable templates
Use reusable templates for recurring foreign-tax analyses while updating tax-year assumptions before each send.
Controlled access
Protect taxpayer and foreign-levy information with controlled access and encrypted document handling.
Remote review
Collect approvals from reviewers working outside the office through signNow mobile applications and browser-based signing.
System connections
Connect approved records to systems such as NetSuite, Microsoft 365, Google Drive, or Box for organized storage.
Recommended workflow configuration
Configure the approval record around the taxpayer’s tax year, reviewer roles, and applicable IRS retention requirements.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification with SMS OTP |
| Signature type | Electronic signature with signer intent |
| Audit trail | Retain completion certificate and activity log |
| Document retention | Three years from filing under IRC §6501(a) |
| Encryption | TLS 1.2/1.3 in transit and AES-256 at rest |



Find and fill out the correct treasury irs issue final regulations on the foreign tax credit
airSlate SignNow helps you fill in and sign documents in minutes, error-free. Choose the correct version of the editable PDF form from the list and get started filling it out.
| Versions | Form popularity | Fillable & printable |
|---|---|---|
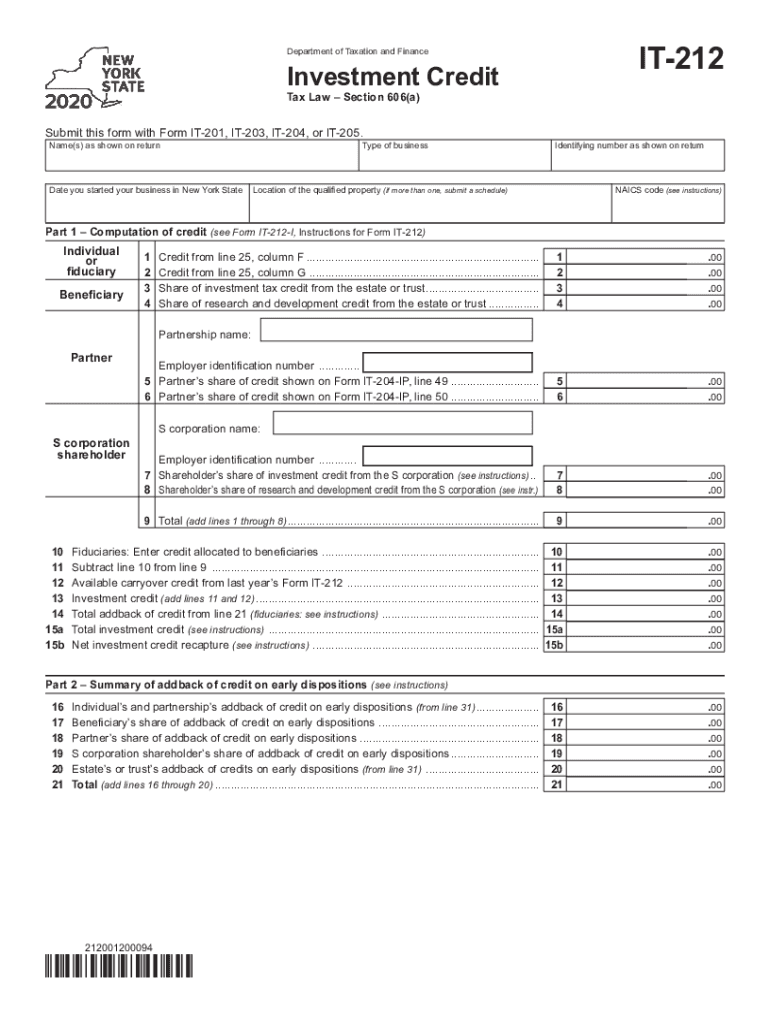
| NY IT-212 2024 | 4.7 Satisfied (133 Votes) | |
| NY IT-212 2023 | 4.8 Satisfied (584 Votes) | |
| NY IT-212 2022 | 4.8 Satisfied (1270 Votes) | |
| NY IT-212 2021 | 4.8 Satisfied (1865 Votes) | |
| NY IT-212 2020 | 4.8 Satisfied (5214 Votes) |
Security for foreign-tax records
Encryption:
Security report:
Information security:
U.S. eSignatures:
Access controls:
Document evidence:
What the audit trail records
The audit trail supplements the tax workpapers by documenting the approval event, signer activity, and completed record.
Authenticate signer:
Timestamp activity:
Track document history:
Seal evidence:
Control retrieval:
Export archive:
Milestones for completing the review
No universal signature deadline applies to this regulatory document; coordinate completion with the taxpayer’s applicable return and workpaper schedule.
Prepare analysis
Deliver to reviewers
Obtain signatures
Archive completion
Retention periods for tax records
Retention depends on the taxpayer’s filing, understatement, fraud, and recordkeeping facts; the periods below come from IRC §6501(a) and should be applied with tax advice.
Three years from filing
Six years for understatement
Indefinite for fraud
Tax workpaper schedule
Longer policy period
Privacy and document-control challenges
Uploading workpapers containing taxpayer identification numbers can expose sensitive data if access permissions are broader than the tax team’s actual need. A signed tax memorandum may omit the taxpayer’s electronic-consent record, making it harder to show who approved the documented foreign tax position. Sharing a foreign-tax analysis through an unrestricted link can disclose confidential income, levy, or ownership information to unintended recipients. Using one template for different tax years can carry forward outdated regulatory assumptions, foreign-tax amounts, or allocation conclusions.
Risks of incomplete tax documentation
Tax position rejected
Audit trail gap
Regulatory mismatch
Confidentiality breach
Questions about foreign tax credit records
These answers separate signNow’s document workflow from the IRS rules that determine the tax treatment of foreign taxes.
Business includes legally binding eSignatures, templates, and audit trails, with annual pricing of $8 per user per month. Use Business Premium at $15 per user per month when bulk send is required for recurring tax packets.
signNow supports ESIGN and UETA compliance, but those frameworks do not decide whether a foreign levy is creditable. A tax professional must apply the Treasury regulations and document the levy, sourcing, allocation, and tax-year facts.
Use signNow’s audit trail and completion certificate to preserve signer identity, timestamps, and activity. Keep the signed memorandum with the underlying tax workpapers and follow the taxpayer’s applicable IRS retention policy.
The foreign tax credit regulations are not a substitute for Form 1116, Form 1118, or another applicable tax filing. Use the relevant IRS form and instructions for reporting, then retain the signed analysis as supporting documentation.
Business Premium includes bulk send, while Business includes templates and audit trails. Select the plan based on the number of separate approval packets and whether identical documents must be sent repeatedly.
For taxpayer information, restrict workspace access, use controlled recipient routing, and preserve the signed record in an approved repository. signNow states that its platform supports SOC 2 Type II, ISO 27001, and AES-256 encryption.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.