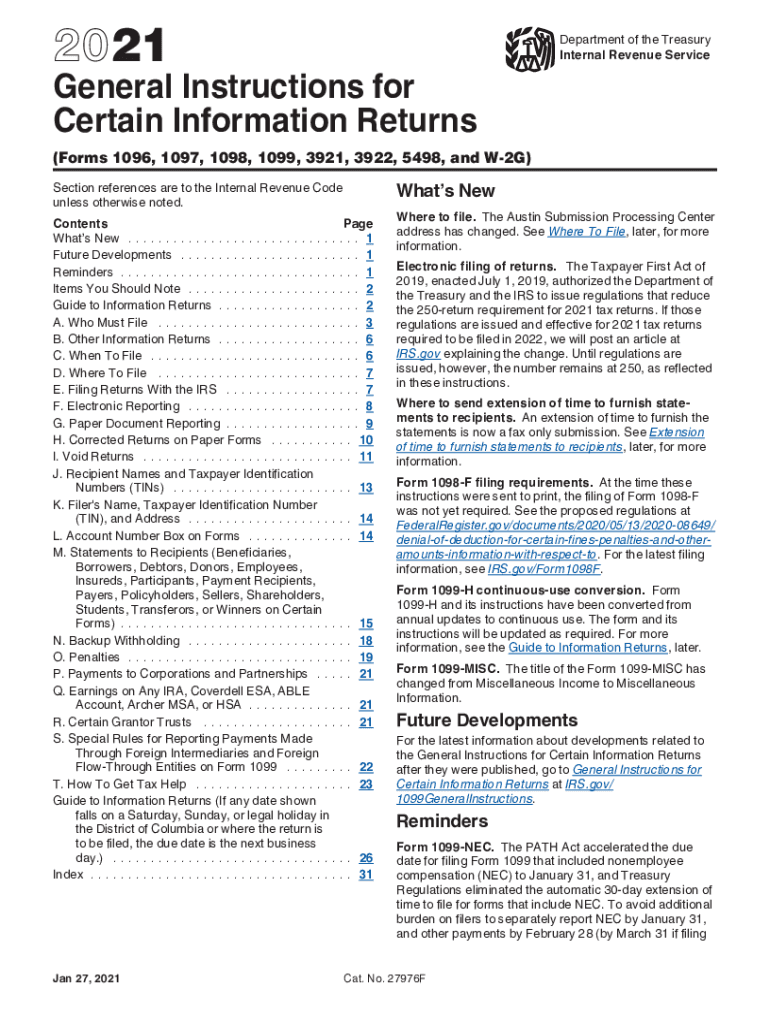
Www IRS Govinstructionsi1099giGeneral Instructions For Certain Information IRS Tax Forms
Use a Www irs govinstructionsi1099giGeneral Instructions For Certain Information IRS Tax Forms 2021 template to make your document workflow more streamlined.
What these IRS instructions cover
These IRS instructions explain how payers prepare and report certain information returns, including how taxpayer and payment details support reporting. For payments made on or after January 1, 2026, the Form 1099-NEC and related information-return threshold is $2,000 per payee under OBBBA, P.L. 119-21; prior years use $600. signNow can upload the document, detect fillable fields, route it for signature, and retain the completed record with an audit trail, but it does not replace IRS filing or tax advice.
Who uses these IRS instructions
The instructions primarily guide payers and payees handling taxpayer information and information-return reporting obligations.
Independent contractors use the instructions to provide taxpayer information to payers, review name and identification details, and sign related records before payment reporting. A signNow template can standardize collection without changing the IRS-required information. Small-business finance teams use the instructions to classify payments, collect taxpayer information, approve information returns, and preserve signed evidence. The workflow helps separate document preparation from the payer’s final IRS filing responsibility. Enterprise accounts-payable departments use controlled templates, role-based access, and audit trails for high-volume payee records. Business Premium may support bulk sending, while Enterprise adds advanced signer authentication and conditional fields.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
Features for IRS information returns
signNow connects document preparation, controlled signing, and record evidence for payer and payee workflows involving IRS information returns.
Field placement
Upload the IRS instructions or related return template, then place fields for taxpayer information, dates, signatures, and approvals without rebuilding the document.
Signer routing
Route the record to an authorized payer, contractor, or internal reviewer using defined signing order and recipient roles.
Audit trail
Capture timestamps, IP information, and action history so the completed information-return record has supporting execution evidence.
Reusable templates
Use templates for recurring payer and payee workflows while keeping the IRS-specific fields visible for review before signing.
Bulk sending
Business Premium includes bulk send, which can distribute substantially similar information-return documents to multiple recipients from a controlled workflow.
Data protection
TLS 1.2/1.3 in transit and AES-256 at rest protect stored taxpayer information within the signNow service.
Complete the IRS information return
Use this workflow to prepare the IRS instructions and related information-return records before filing or sharing them.
Confirm parties:
Confirm the payer and payee information before completing the applicable information return. Upload documents:
Upload the IRS instructions or return template to signNow. Review fields:
Review detected fields and add missing taxpayer information. Send and store:
Send the completed form for authorized signature and retain the final record.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Set up the information-return workflow
Configure signer verification, access controls, audit evidence, and tax-record retention before distributing IRS information-return documents.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification with SMS OTP |
| Signature type | Intent-based electronic signature |
| Audit trail | Capture timestamps, IP address, and action history |
| Document retention | 3 years from filing under IRC §6501(a) |
| Encryption and users | TLS 1.2/1.3, AES-256, role-based access |
Protect taxpayer information
Transport encryption:
Storage encryption:
Security certification:
Information security:
Electronic signatures:
Execution evidence:
Find and fill out the correct wwwirsgovinstructionsi1099gigeneral instructions for certain information irs tax forms
airSlate SignNow helps you fill in and sign documents in minutes, error-free. Choose the correct version of the editable PDF form from the list and get started filling it out.
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| IRS General Instructions for Certain Information Returns 2024 | 4.7 Satisfied (128 Votes) | |
| IRS General Instructions for Certain Information Returns 2022 | 4.8 Satisfied (912 Votes) | |
| IRS General Instructions for Certain Information Returns 2021 | 4.8 Satisfied (1225 Votes) | |
| IRS General Instructions for Certain Information Returns 2020 | 4.8 Satisfied (959 Votes) | |
| IRS General Instructions for Certain Information Returns 2018 | 4.8 Satisfied (4326 Votes) | |
| IRS General Instructions for Certain Information Returns 2017 | 4.7 Satisfied (805 Votes) |


Prepare, sign, and archive the return
The IRS deadline depends on the specific information return; Form 1099-NEC recipient and IRS copies are due January 31.
Prepare the return
Deliver to signer
Collect signature
Archive and file
Retain signed tax records
Retention depends on the filing history and omission or fraud conditions identified in IRC §6501; preserve a readable copy and its audit evidence.
Three years from filing
Six years after omission
Indefinite for fraud
Indefinite without filing
Longer applicable period
Avoid information-return privacy errors
A missing taxpayer identification number can prevent accurate information reporting and may require corrected records or backup-withholding review. Payer and recipient names may not match IRS records, creating reconciliation problems when the information return is prepared. Unrestricted access can expose taxpayer identification numbers, payment amounts, and signed IRS information-return records. A signature alone does not replace the payer’s obligation to file the correct information return by its applicable deadline.
Legal standing of electronic records
An electronically signed IRS information-return record can provide evidence of intent, attribution, and record integrity under ESIGN and applicable UETA rules, when consent and reproducible retention requirements are met. These laws do not replace IRS filing rules and exclude wills, certain court filings, and other protected notices.

Troubleshoot IRS information-return workflows
These answers address field accuracy, electronic-signature evidence, reporting thresholds, retention, and signNow plan capabilities for IRS information-return records.
signNow can place text, date, signature, and initial fields on an uploaded IRS information-return document. Review every detected field manually because field detection does not verify taxpayer-identification numbers, payment amounts, or IRS reporting classifications.
The Business plan includes legally binding eSignatures, audit trails, templates, and mobile apps at $8/user/month when billed annually. It does not include the Business Premium bulk-send feature, so repeated recipient workflows may require Business Premium at $15/user/month annually.
The IRS instructions do not make an electronic signature universally sufficient for every filing method. ESIGN and UETA generally recognize qualifying electronic signatures, but confirm the specific return’s IRS submission process and retain a reproducible signed record.
For tax records, retain the signed information-return record for at least three years from filing under IRC §6501(a). The period is six years when 25% or more of gross income is omitted, and longer retention can apply for fraud or no filed return.
The 2026 reporting threshold for Form 1099-NEC and related information-return payments is $2,000 per payee for payments made on or after January 1, 2026, under OBBBA, P.L. 119-21. Prior years use the $600 threshold.
signNow’s audit trail records signing events, timestamps, IP information, and action history. Its ESIGN and UETA compliance supports electronic execution evidence, but the payer remains responsible for IRS accuracy, filing, furnishing, and applicable withholding duties.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.